
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
3 Tanker Stocks to Watch as Diesel Prices Reshape Global Trade
U.S. diesel prices are ripping higher, Washington is openly weighing export limits, and global fuel trade routes are being redrawn in real time. That mix creates real risk for some investors and fresh upside for others as refined products are pushed farther and priced more sharply. This article breaks down how that shock could matter for your portfolio and profiles 3 tanker stocks exposed to the same story.
The three stocks profiled below are only a starter set from this refined-product tanker theme, and the full screen surfaced 9 more companies with equally compelling narratives that are not covered here. If you want to go straight to the source and identify which operators best match your risk, income, and time horizon, head into the Global Refined-Product Tanker Operators screener.
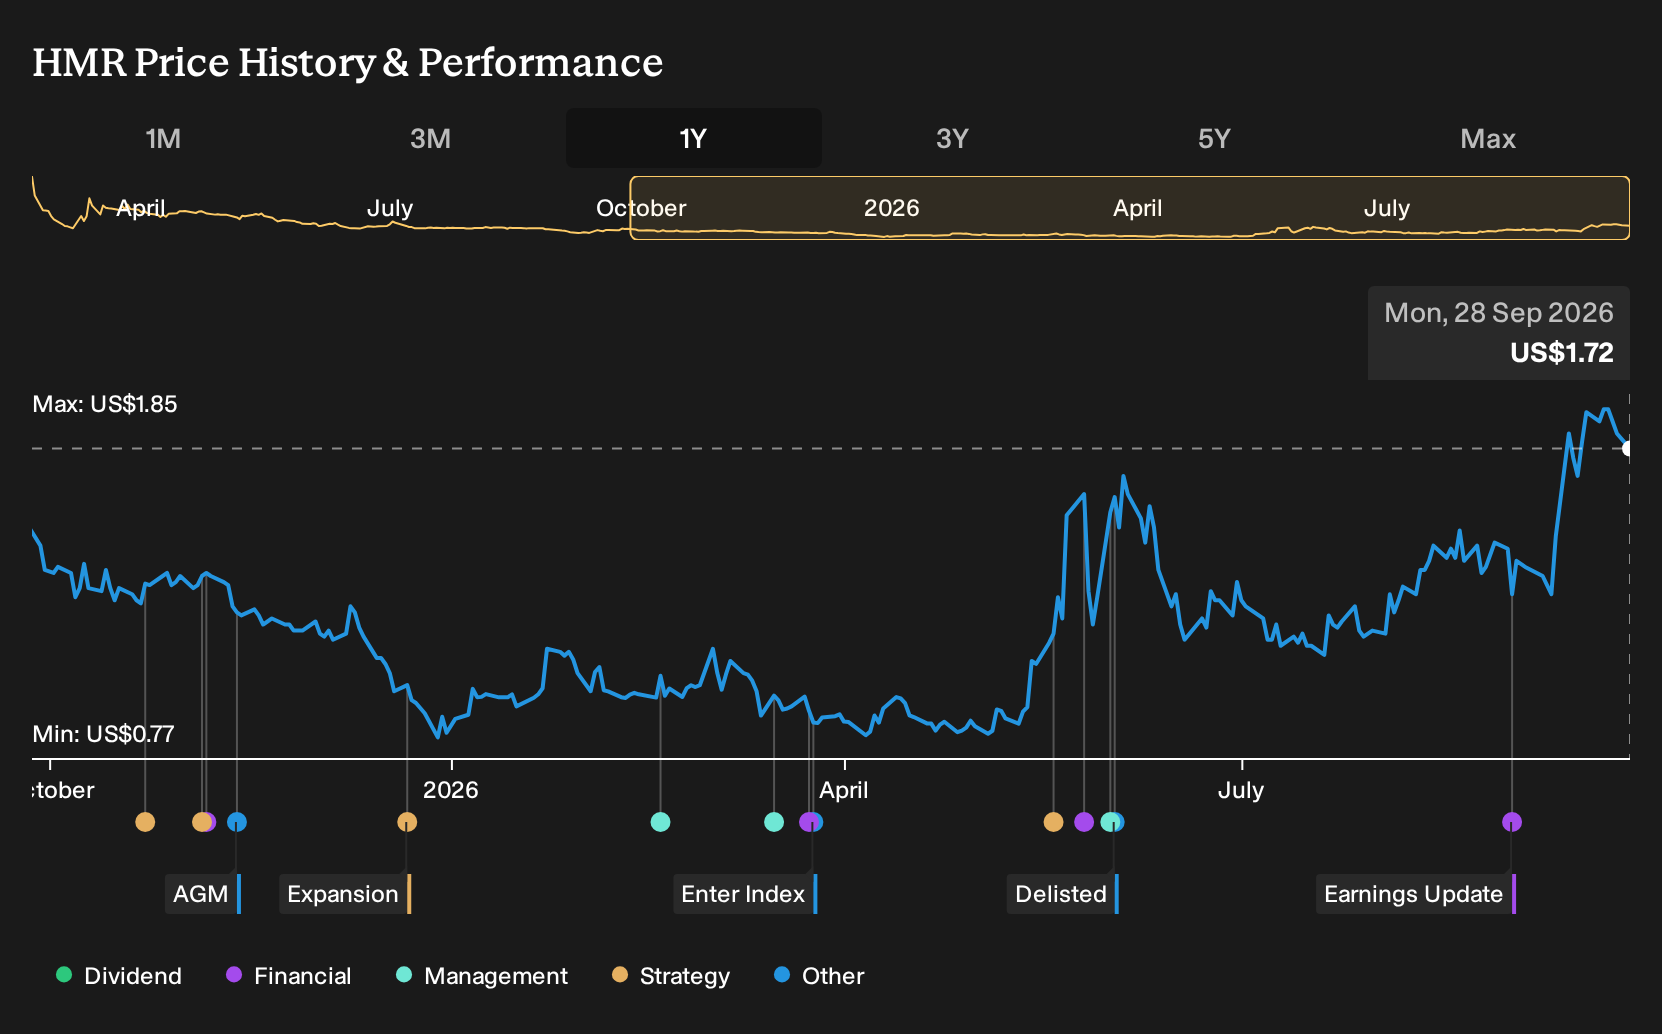
Heidmar Maritime Holdings (HMR)
Heidmar Maritime Holdings runs global tanker and dry-bulk pools that give investors direct exposure to refined-product freight markets, managing 50 vessels that include LR2, LR1 and MR product tankers. The group generated about US$88 million from transportation and shipping and currently has a market value of roughly US$104 million.
Heidmar Maritime Holdings sits squarely in the refined-product tanker theme because its pool model and commercial management are tightly linked to middle distillate trade routes, voyage lengths and freight rates. Recent swings in diesel flows and pricing give this stock clear sensitivity to changes in tanker demand and this will depend on how one unseen pressure plays out.
That unseen pressure is exactly what the 3 key rewards and 1 important warning sign evaluates so you can see how Heidmar Maritime Holdings might react if trade patterns keep stretching.
Calumet (CLMT)
Calumet, Inc. gives you exposure to refined fuels pricing rather than freight rates. This makes it a different kind of play inside this tanker-focused theme as diesel and jet spreads move around policy shifts and export noise.
Calumet, Inc. produces specialty chemicals and renewable fuels, with Specialty Products and Solutions bringing in about US$3.1b, Montana/Renewables roughly US$1.2b, and Performance Brands around US$341m, all from U.S. customers, and the stock is valued near US$4.7b.
"The MaxSAF 150 project is on track to start up in the first half of 2026, enabling Calumet to produce 120-150 million annual gallons of sustainable aviation fuel (SAF) at relatively low capital costs, capturing premiums of $1-$2/gallon over renewable diesel and tapping into surging mandated and voluntary SAF demand globally. This is likely to drive material step-up in revenues and EBITDA margin expansion once operational."
What happens to those potential gains if one key policy lever on cleaner fuels or diesel exports suddenly moves the other way?
If that policy risk matters to you, read the full narrative for Calumet to see how Calumet could accelerate or stall as diesel, SAF and exports decouple.

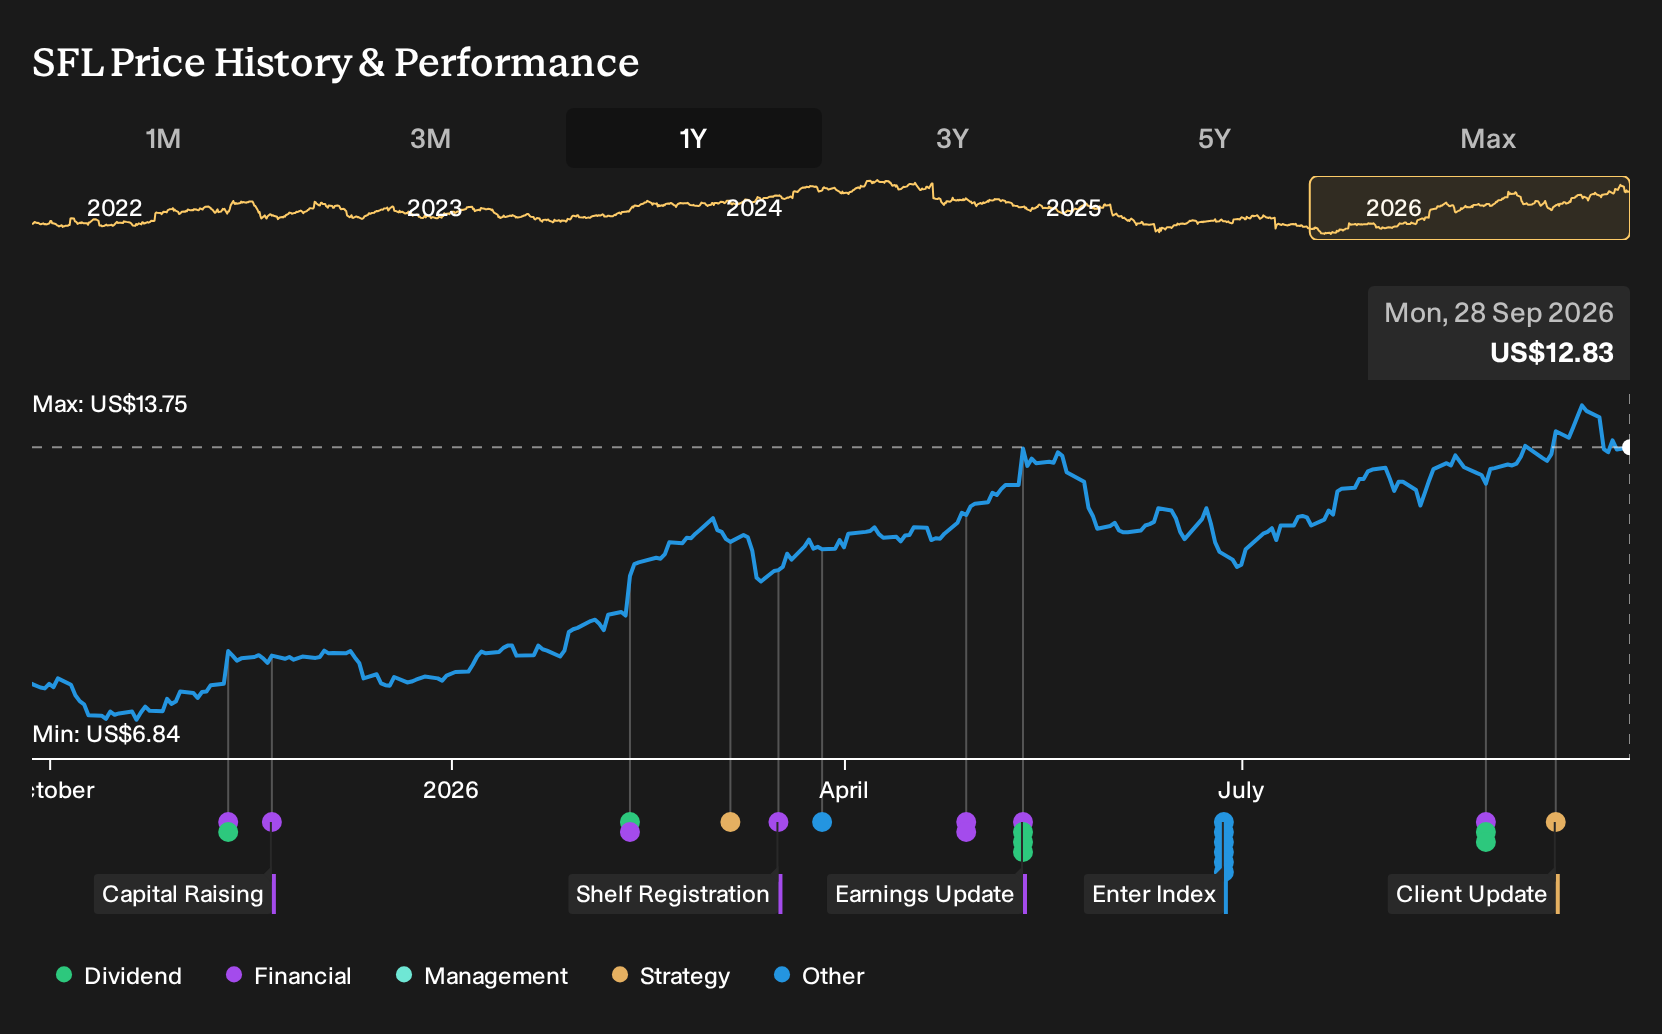
SFL (SFL)
SFL Corporation sits in this refined-product tanker theme as a diversified shipping owner whose tanker fleet and long haul charters plug directly into changing diesel and product trade routes, with about US$712 million from transportation and shipping on top of a roughly US$1.8b market value.
SFL Corporation gives you exposure to refined-product trade flows through a fleet that leans on long term charters, so periods of stretched diesel routes or altered export patterns can matter a lot for cash generation and payout potential.
"Although a $4 billion fixed rate charter backlog with mostly investment grade counterparties provides strong cash flow visibility, the long duration of these contracts may limit SFL’s ability to reprice vessels into higher rate environments, capping upside in revenue and EBITDA during shipping upcycles."
The real swing factor is what happens to that steady charter cover if one key assumption about future freight spreads or fuel rules breaks.
If that assumption is wrong in either direction, the full narrative for SFL shows how SFL’s backlog, rate optionality and payout profile could be quietly accelerating or stalling beneath the surface.
Seeking Alternatives Before The Crowd?
Fresh themes are lining up and the fastest movers usually set the tone. Catch the next breakout while it matters, before momentum gets fully priced in. Consider acting early if it suits your strategy.
- Target dependable income streams before yields get compressed by demand using the curated 6 dividend fortresses that screen strongly for balance sheet strength and payout support.
- Seek early upside where AI profits are already flowing, not just promised, with a focused set of 37 profitable AI stocks that aren't just burning cash vetted for real earnings power.
- Position ahead of potential electrification tailwinds by scanning the tightly filtered 16 top copper producer stocks tied to projects that could matter as grid and metals demand evolve.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com