
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Bolloré (ENXTPA:BOL) Posts Higher Half Year Sales, Is The Premium Still Justified?
Bolloré (ENXTPA:BOL) drew fresh attention on 16 September 2026 after its board meeting approved first half 2026 accounts, confirming higher sales of €1,644 million alongside net income of €132 million.
The fresh half year figures land while Bolloré’s share price has fallen 23.46% year to date and declined 9.91% over 90 days, even though the 1 year total shareholder return of 8.11% and 5 year total shareholder return of 8.05% suggest longer term holders have seen modest gains.
Scan how Bolloré compares by reviewing a hand picked group of companies on the 197 high quality undervalued stocks that couple solid fundamentals with more supportive share price trends.
Sales are higher, net income is lower and the Bolloré share price has already fallen hard this year. Has most of the repricing already happened, or is the real upside still in front of you?
Price-to-Earnings of 43.6x: Is it justified?
Bolloré closed at €3.65, and the current P/E of 43.6x sits far above peers, which suggests the market is paying a rich price for each euro of reported earnings.
The P/E ratio compares the share price to earnings per share and shows how much investors are willing to pay for the profit Bolloré generates today. For a diversified group with energy, communications and industrial activities, this metric often reflects how steadily those earnings are expected to continue rather than just what happened in a single year.
Here, the market is assigning a P/E of 43.6x while the peer average sits at 16.4x and the wider European oil and gas group sits at 13.9x. That is a steep premium. The estimated fair P/E for Bolloré is 18.6x, which is much closer to those reference points and indicates that the current multiple is well above the level the market could move toward if sentiment cools.
Explore the SWS fair ratio for Bolloré.
Result: Price-to-Earnings of 43.6x (OVERVALUED)
Still, the rich P/E sits against a year to date share price decline, and any reset in sentiment could hit Bolloré hard if earnings expectations soften.
Find out about the key risks to this Bolloré narrative.
Another View on Bolloré’s Value
The rich P/E tells one story, but the SWS DCF model tells another. At a share price of €3.65 the stock screens as expensive compared with an estimated future cash flow value of €3.05. That gap suggests there may be limited room for error if sentiment or forecasts change.
Look into how the SWS DCF model arrives at its fair value.
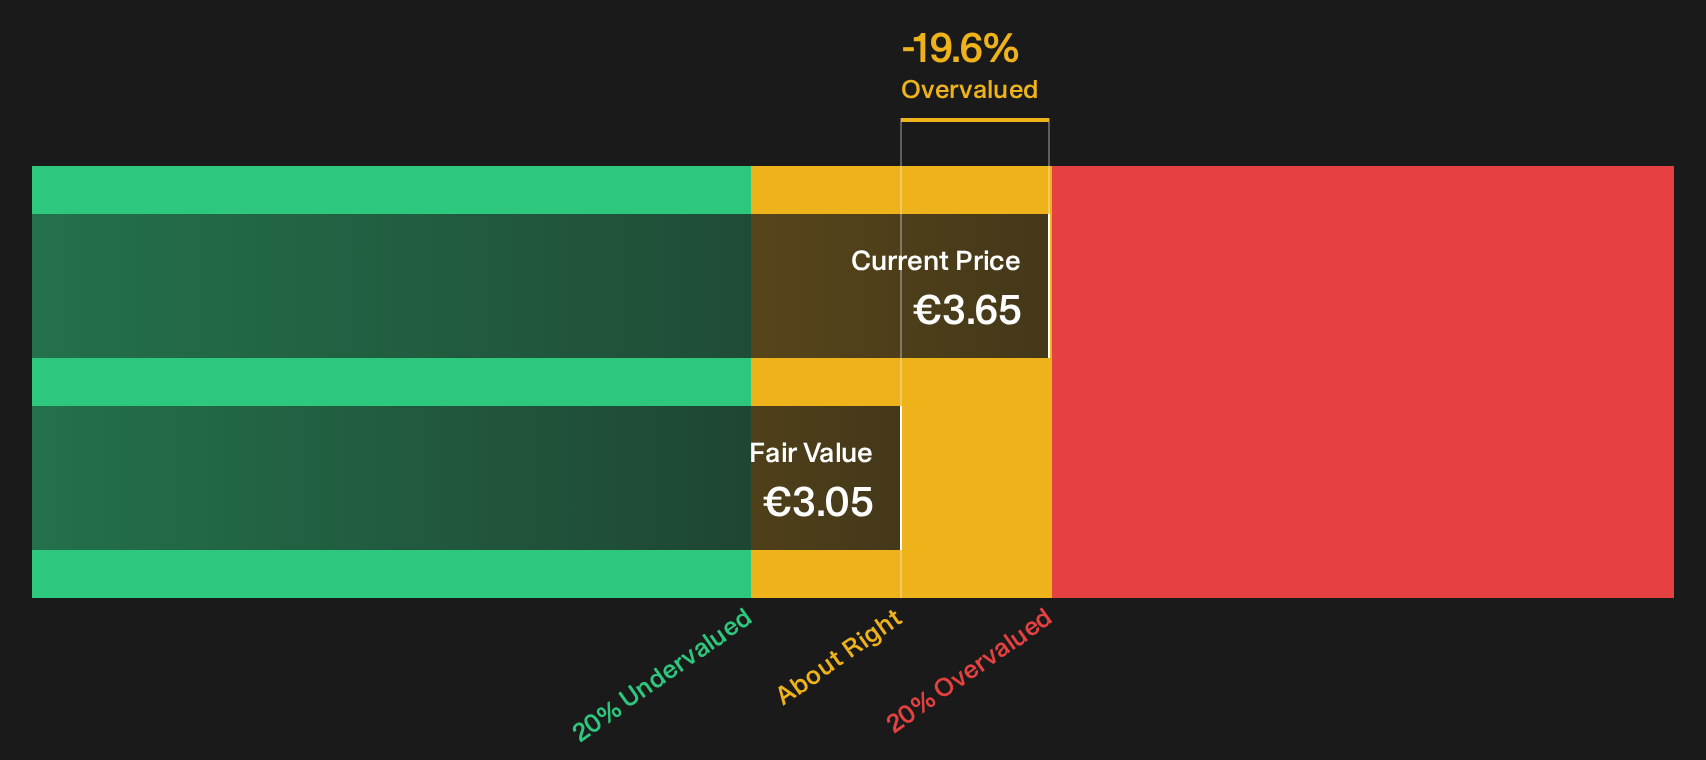
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Bolloré for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 197 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals on Bolloré so far, so do not sit on the fence when the data is right in front of you. Our work highlights both pressure points and bright spots in the story. Take a moment to weigh them and drill into the 2 key rewards and 1 important warning sign.
Looking for more Bolloré style investment ideas?
If Bolloré has you rethinking your watchlist, this is the moment to widen the lens and hunt for fresh opportunities before others move first.
- Target resilience by reviewing a list of solid balance sheet and fundamentals (202 results) that highlights companies with financial strength that can help support business performance through different market conditions.
- Spot mispriced opportunities by scanning a 618 high quality undiscovered gems of under followed businesses that pair robust fundamentals with relatively limited attention.
- Dial down volatility by focusing on a 221 resilient stocks with low risk scores that filters for companies with more stable characteristics that can help smooth portfolio swings.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com