
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Did Asset Sale Plans Just Shift GFL Environmental Stock's Investment Narrative?
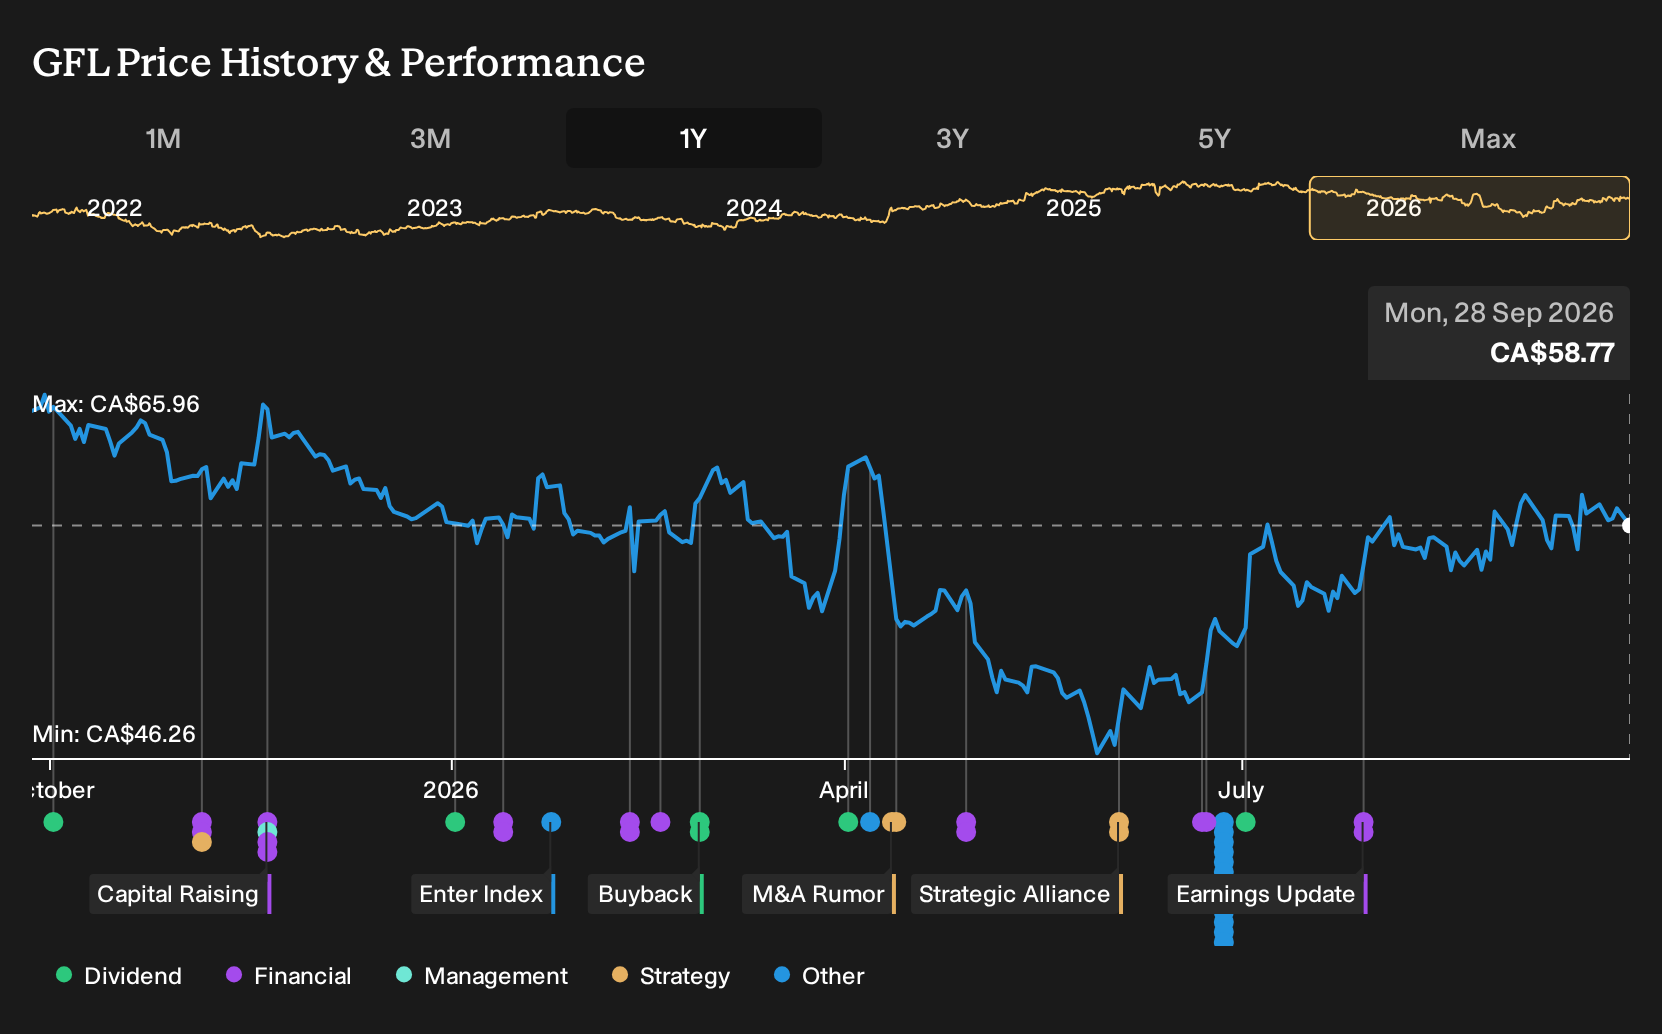
- GFL Environmental recently drew fresh attention after its shares closed at CA$59.72, as management advanced plans to sell the Environmental Services business and continued to fund extended producer responsibility and renewable natural gas projects.
- The combination of a potential Environmental Services unit divestiture and rising spend on extended producer responsibility and renewable natural gas indicates a pivot toward balance sheet flexibility and longer term sustainability driven revenue streams.
- We will now examine how GFL Environmental's planned Environmental Services divestiture could reshape its investment narrative and long term financial profile.
Scan other waste and infrastructure plays positioned for similar sustainability projects and balance sheet moves by checking the hand picked list of solid balance sheet and fundamentals (7 results) today.
GFL Environmental Investment Narrative Recap
To own GFL Environmental, you need to be comfortable with a story built on waste collection scale, pricing power, and a pivot toward sustainability projects like extended producer responsibility and renewable natural gas. The core idea is that these areas can support margins over time. The latest share move around CA$59.72 does not materially change that basic thesis.
In the near term, the key factor is execution on the Environmental Services sale and how cleanly that shift in mix flows through to earnings and leverage. The biggest operational risk remains exposure to weaker commodity and used motor oil pricing, with inflation and weather adding further uncertainty to volumes and profitability.
The planned disposal of the Environmental Services unit is the main development tied to this news. Management has described it as a way to reshape the balance sheet and free up capital, while placing more focus on core solid waste, EPR and RNG projects. The divestiture also removes a stream of revenue and profit that the market will watch closely.
For shareholders, the central issue is execution. Successful closing and reinvestment could support future margin initiatives, M&A capacity and potentially more consistent cash generation. Missteps or a weaker than expected profit profile after the sale would add to existing pressures from commodity prices, currency moves and inflation across GFL Environmental’s operating footprint.
GFL Environmental's narrative projects CA$9.2b revenue and CA$595.0m earnings by 2029. This reflects an assumed 9.9% yearly revenue growth and an earnings swing of about CA$792.8m from a loss of CA$197.8m today.
Uncover how GFL Environmental's fair value indicates a 23% potential upside to its current price before that discount closes.
Exploring Other Perspectives
For GFL Environmental, the sharpest contrast comes from bearish analysts who treat regulatory change as the real swing factor. They see faster zero waste rules and new recycling tech cutting into traditional landfill cash flows, with revenue only reaching about CA$8.6b and earnings about CA$308.9m by 2029. That outlook is far more cautious than consensus. Both sets of forecasts were built before this Environmental Services sale plan, so you should expect opinions to shift and you may want to explore several viewpoints before deciding how this story fits your portfolio.
Explore 4 other GFL Environmental fair value estimates, including one that suggests it could be worth just CA$57.00.
Form Your Own Verdict
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so trust your own research and judgment.
- A great starting point for your GFL Environmental research is our analysis highlighting 2 key rewards that could impact your investment decision.
- See our latest analysis for GFL Environmental. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, which makes it easier to evaluate GFL Environmental's overall financial health at a glance.
Looking for more investment ideas beyond GFL Environmental?
Once you have a handle on GFL Environmental, it can help to widen the lens and line it up against other opportunities that match your risk profile, income needs, or preference for balance sheet strength.
- If you want potential mispricing combined with quality fundamentals, scan through a curated set of 5 high quality undervalued stocks that might deserve a place on your watchlist.
- For investors who care about resilience first and returns second, filter the market using a 8 resilient stocks with low risk scores to see which businesses clear that bar.
- If income is a priority and you prefer companies that pay you regularly, focus on a hand picked pool of 1 dividend fortresses that may suit a dividend focused approach.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com