
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
What Is Drawing Attention To Axogen (AXGN)?
Axogen (AXGN) has drawn attention after recent trading, with the share price at $43.36 and a mixed return pattern that includes declines over the past month and past 3 months but strong gains over the past year.
That recent pullback, with the 30 day share price return down 15.76% and the 7 day move also weaker, sits against a much stronger backdrop. Axogen’s year to date share price return is up 39.87%, and the 1 year total shareholder return is 151.22%, hinting that shorter term momentum is cooling after a powerful multi year run in which total shareholder return has been a very large multiple of the starting value.
Scan beyond Axogen and see how it stacks up against a hand picked 16 high quality undiscovered gems with strong fundamentals and under the radar share price moves.
Axogen now trades about 11% below one estimate of intrinsic value and roughly 25% under the average analyst target after a sharp pullback. Is that discount caution well earned, or an opportunity that is being mispriced?
Most Popular Narrative: 19% Undervalued
Axogen’s most followed valuation narrative indicates a fair value of $53.22 compared with the recent $43.36 close. This frames the current pullback as a discount to that view and places more emphasis on the long term nerve repair story than on short term price swings.
Broad-based adoption of Axogen's nerve care algorithm across multiple markets (extremities, oral maxillofacial, breast) and momentum in activating high-potential accounts indicate that the addressable market for nerve repair is still substantially underpenetrated. This is described as suggesting a long runway for sustained double-digit revenue growth as awareness and adoption rise. Recent and ongoing commercial payer coverage changes, which are attributed to updated clinical evidence and increasing clinician advocacy, are presented as removing access barriers and expanding the pool of reimbursed patients. This is expected by the narrative’s authors to unlock incremental procedure volume and influence top-line revenue over the coming years as coverage moves closer to broad availability.
See why 8 investors see Axogen as 19% undervalued.
Result: Fair Value of $53.22 (UNDERVALUED)
Still, Axogen’s heavy dependence on its Avance Nerve Graft, along with the uncertainty around the BLA process and reimbursement decisions, could quickly challenge that undervalued thesis.
Find out about the key risks to this Axogen narrative.
Another Lens On Axogen’s Valuation
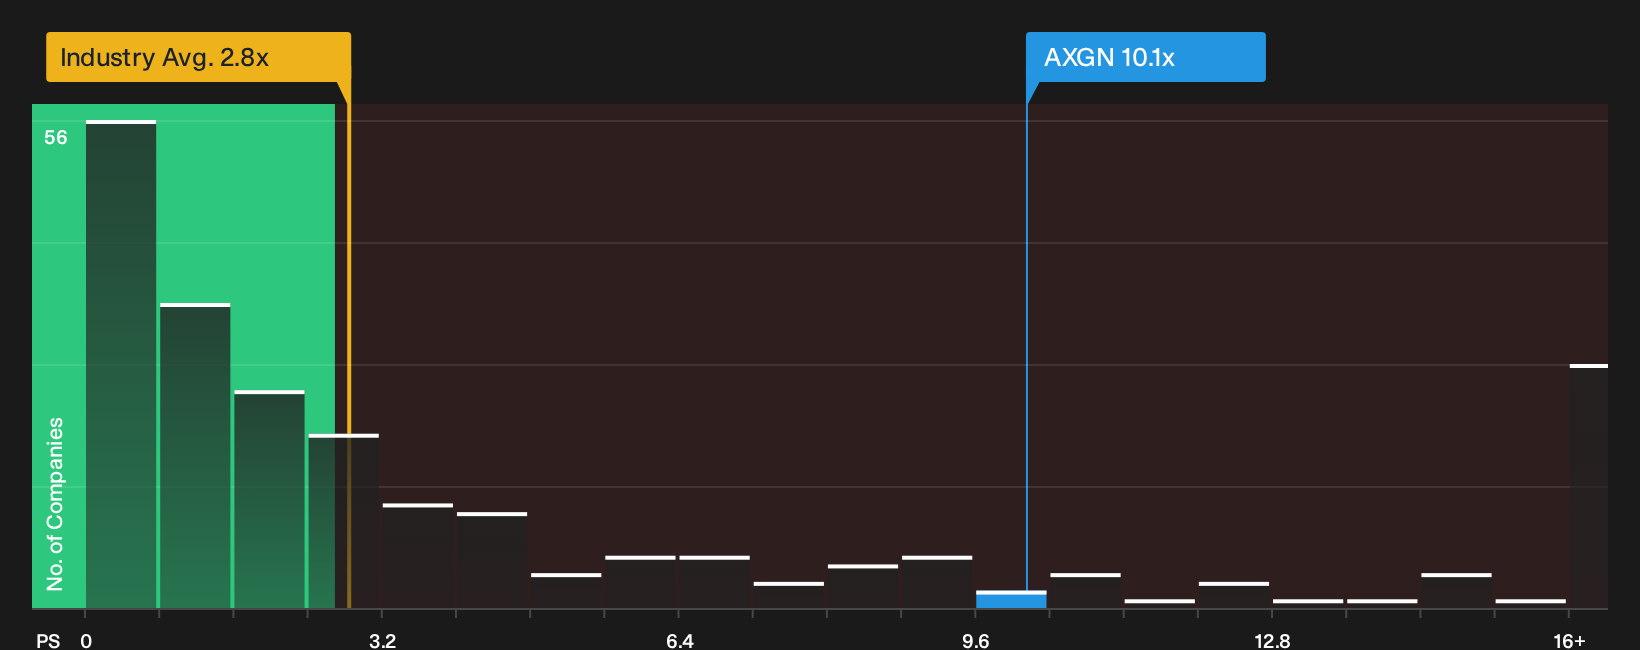
While the SWS DCF model points to Axogen trading about 11% below one estimate of fair value, the market is asking a very full price on sales. The current P/S ratio of 10.1x sits well above the US Medical Equipment industry at 2.8x, peers at 8.5x, and a fair ratio of 5.4x that the market could move toward. That gap raises a simple question for investors: is this a quality premium or valuation risk if sentiment cools?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals around Axogen’s value and risk profile can pull you in both directions, so move quickly, review the underlying data, and weigh the 3 key rewards and 1 important warning sign.
Looking for more Axogen sized investment ideas?
Do not stop at Axogen. Use the Simply Wall St screener to surface fresh ideas that match your risk comfort, income needs, and appetite for mispriced opportunities.
- Target potential bargains before they move by scanning a curated set of companies trading on quality and value signals through the 33 high quality undervalued stocks.
- Prioritise resilience by focusing on businesses with strong finances using a focused list of solid balance sheet and fundamentals (24 results) that filters for sturdier fundamentals.
- Build a more defensive watchlist by zeroing in on companies filtered through the 30 resilient stocks with low risk scores that may offer smoother rides through choppy markets.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com