
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Will Japan WAKIX Approval Change Viatris (VTRS) Stock Narrative
- Viatris reported that Japan's Ministry of Health, Labour and Welfare approved WAKIX for excessive daytime sleepiness in obstructive sleep apnea and for both types of narcolepsy, supported by domestic Phase 3 trials and international studies.
- This clearance gives Viatris access to a differentiated, non controlled sleep disorder therapy in Japan. It adds a branded asset in areas of unmet need where excessive daytime sleepiness can impair daily functioning even when airway obstruction is already treated.
- The next step is to examine how Viatris' investment narrative could shift as WAKIX gains approval in Japan for excessive daytime sleepiness.
Viatris Investment Narrative Recap
To own Viatris, you need to be comfortable with a large, global generics platform that is still working through pricing pressure, heavy competition, and the drag from an unprofitable base. The appeal is the mix of broad distribution and what management is trying to build on top of it, from complex generics to more differentiated brands like WAKIX.
In the near term, the key catalyst remains execution on cost efficiency and steadying margins while integrating past deals and remediating facilities. The biggest risk is that price erosion and regulatory pressure, including in Japan, continue to blunt any benefit from newer therapies. The WAKIX approval is helpful but not transformational on its own.
The WAKIX approval in Japan ties directly into Viatris’ push toward higher value products in chronic and specialty conditions. It sits alongside late stage efforts in areas such as ophthalmology and complex pain medicines, which analysts already flag as important for lifting overall mix quality and margins over time.
For you as an investor, the operational question is whether launches like WAKIX can meaningfully offset reliance on mature off patent drugs and intense generic competition. If execution on new products, emerging markets and cost savings keeps tracking to plan, these kinds of branded additions can gradually reduce exposure to pure price based pressure.
What The Current Viatris Forecasts Assume
Viatris' current analyst narrative points to forecast revenues of US$15.6b and earnings of US$765.4m by 2029. That path assumes revenue growth of 1.8% per year and an earnings swing of about US$1.18b, from a loss of US$410.7m today to the projected profit.
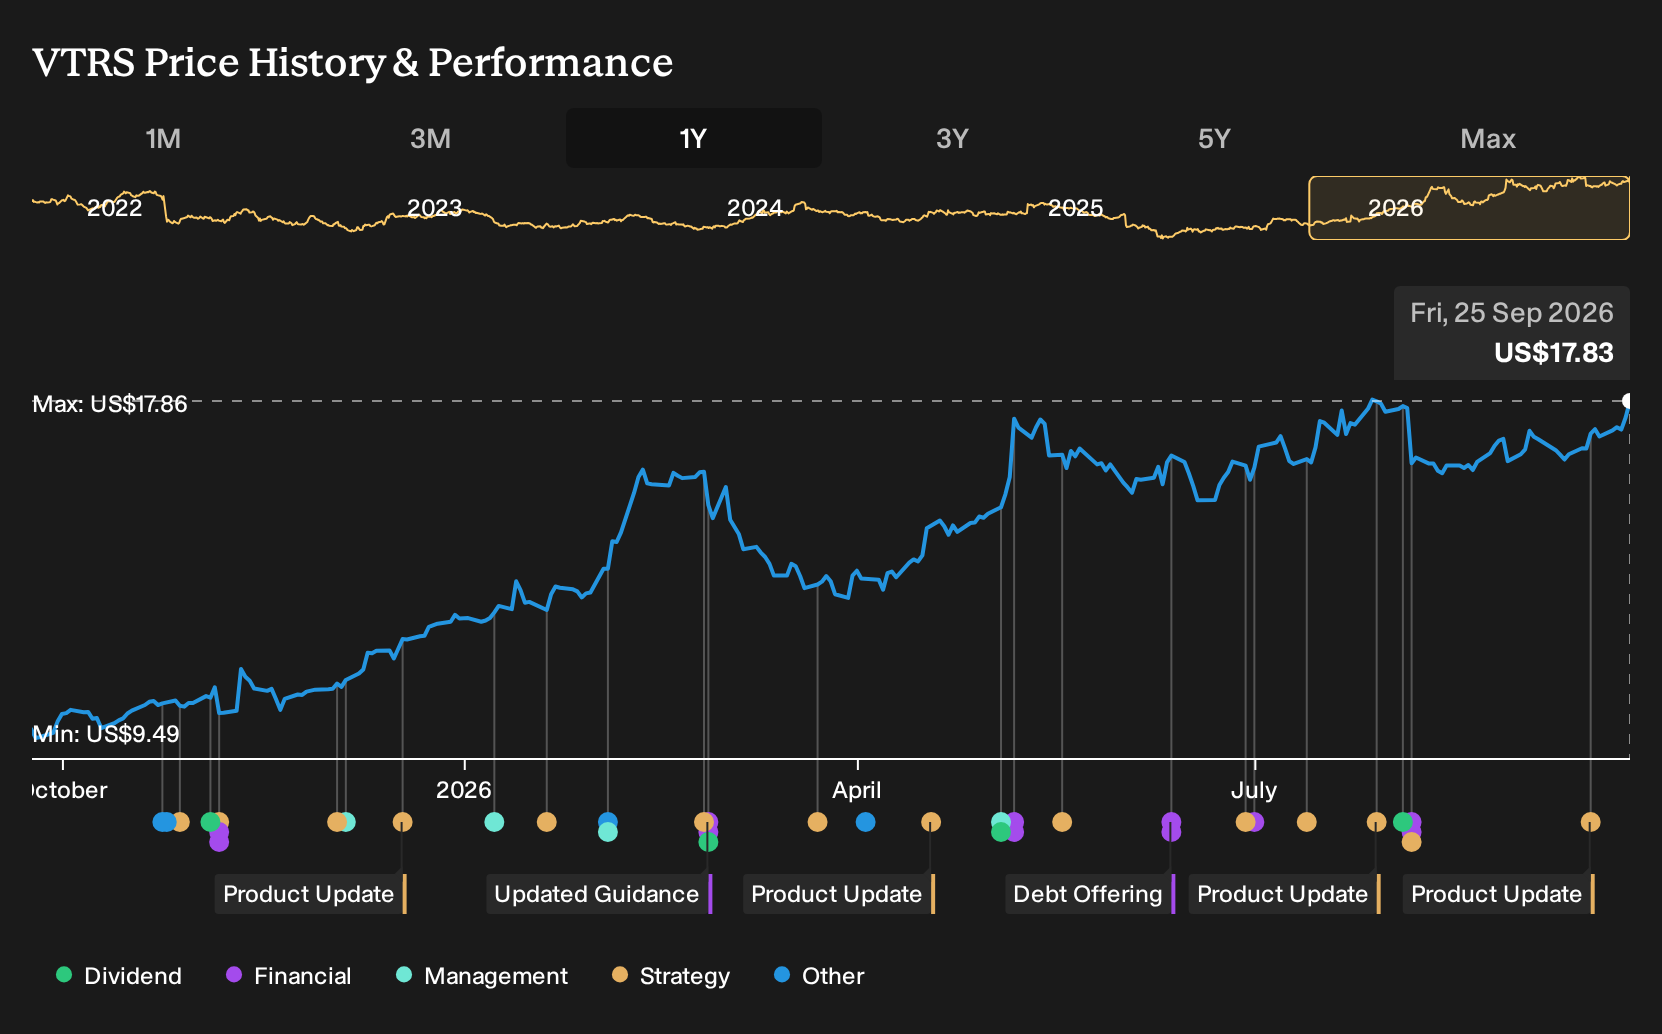
Discover how Viatris' fair value indicates a 4% potential upside to its current price that could close sooner than many investors expect.
Exploring Other Perspectives
One alternate take on Viatris leans hard into pricing risk. The most cautious analysts expected only 1.6% annual revenue growth and earnings of about US$541.8m by 2029, well below the US$765.4m consensus, even before this WAKIX news. Use that spread to stress test your own view and explore multiple possible paths from here.
Explore 5 other Viatris fair value estimates, including one that suggests it could be worth just $18.50.
The Verdict Is Yours
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Viatris research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Viatris. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Viatris' overall financial health at a glance.
Looking For More Ideas Beyond Viatris?
If the Viatris story has you thinking about how to balance risk, quality, and income in your portfolio, it can help to line it up against other opportunities with similar traits. The Simply Wall St Screener lets you quickly filter for different styles of stocks so you can build a watchlist that fits how you like to invest.
- If you want potential mispricings with solid fundamentals, start with a focused set of 32 high quality undervalued stocks that already combine quality with attractive valuations.
- For investors who care most about balance sheet strength, there is a targeted list of solid balance sheet and fundamentals (24 results) that can help you prioritise resilience before anything else.
- If you prefer businesses that fly under the radar, consider a curated pool of 16 high quality undiscovered gems that may not yet be widely followed.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com