
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Is Hagerty (HGTY) Undervalued As It Keeps More U.S. Underwriting Risk?
Investors are zooming in on Hagerty (HGTY) after the insurer moved Hagerty Re to retain 100% of underwriting risk on its U.S. book, alongside strong Q1 2026 financial results and a recent US$13.59 close.
Recent trading hints at building momentum for Hagerty, with a 90 day share price return of 14.01% and a year to date share price return of 3.35%. The 1 year total shareholder return of 15.86% and 3 year total shareholder return of 66.95% suggest longer term holders have fared materially better than short term traders.
Compare Hagerty's momentum and risk profile with a hand picked 30 resilient stocks with low risk scores that aim to balance steady fundamentals with tighter downside risk control.
The move to keep all U.S. underwriting risk and the gap between Hagerty’s US$13.59 share price and higher fair value estimates pull in opposite directions. Is most of the easy upside already spent, or is investors’ caution still excessive?
Most Popular Narrative: 15% Undervalued
Hagerty’s most followed narrative pegs fair value at $16.00, above the recent $13.59 close. This frames the current debate around how much of the insurer’s long term earnings power is already reflected in the share price.
The shift toward Hagerty Re retaining 100% of the underwriting risk on the U.S. book, combined with an 87% combined ratio and a 77% rise in adjusted EBITDA to US$85 million in Q1 2026, points to greater control over insurance economics that can support higher earnings and cash flow over time.
See why 0 investors see Hagerty as 15% undervalued.
Result: Fair Value of $16.00 (UNDERVALUED)
Still, the bullish Hagerty story runs into real friction if GAAP losses persist longer than expected or if collector car enthusiasm cools and weakens marketplace demand.
Find out about the key risks to this Hagerty narrative.
Another View On Hagerty’s Valuation
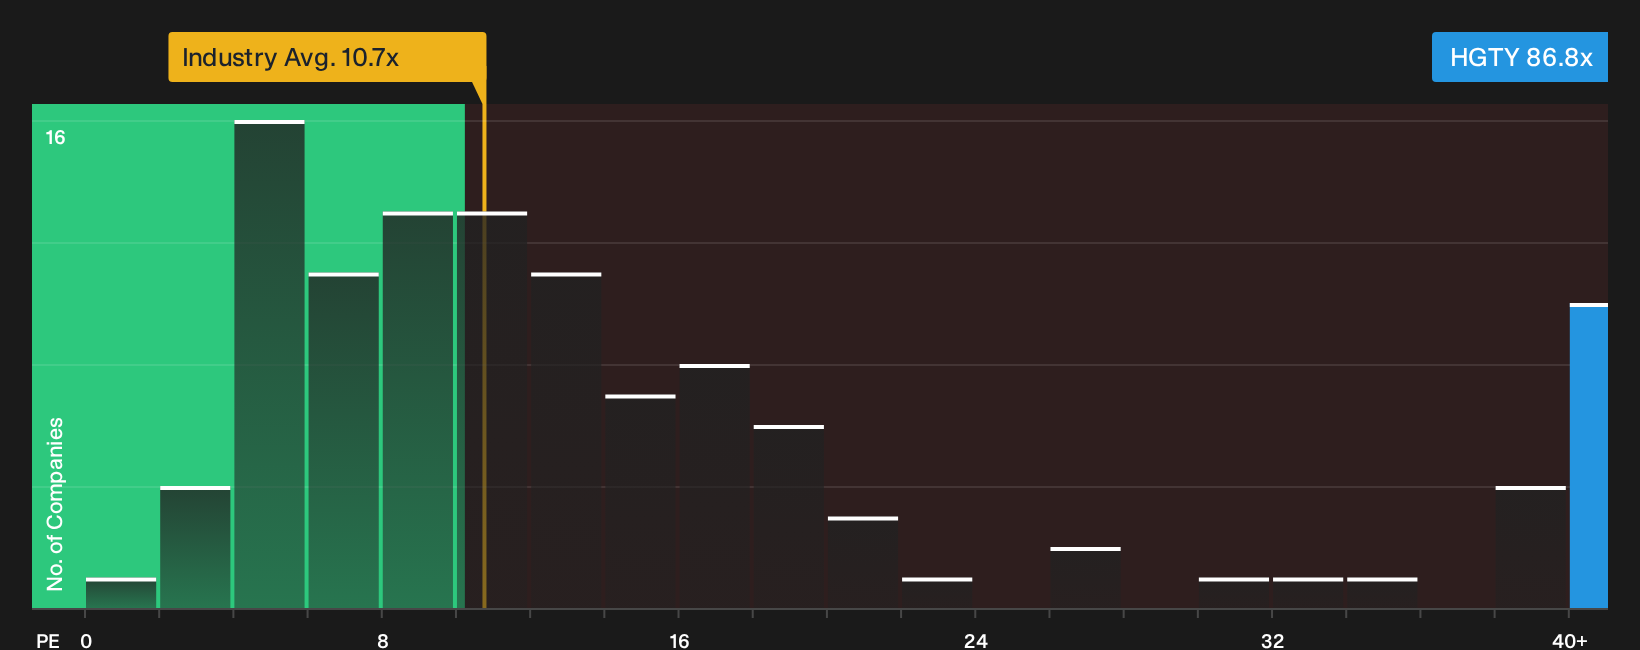
That $16.00 fair value narrative leans heavily on future earnings strength. Current trading tells a different story. Hagerty changes hands at a P/E of 86.8x, which is far richer than the US Insurance industry on 10.7x and its own fair ratio of 35.9x.
Such a wide gap means investors today are already paying a premium for execution that still needs to come through. The risk is that any disappointment sees the share price move toward that lower fair ratio rather than the upbeat targets.
For a closer look at how this earnings multiple stacks up and what the fair ratio implies for valuation risk, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals around Hagerty can make the story feel pulled in two directions, so check the details yourself and pressure test the trade off between enthusiasm and concern by starting with 1 key reward and 1 important warning sign.
Looking for more Hagerty sized opportunities?
If Hagerty has you thinking bigger about your portfolio, do not stop here. Fresh ideas today can set up the decisions you will be glad you made later.
- Target upside potential with a curated 16 high quality undiscovered gems that focuses on companies pairing strong fundamentals with limited market attention.
- Strengthen your portfolio core by scanning a list of solid balance sheet and fundamentals (24 results) that can help you stress test quality across different sectors.
- Lock in income ideas by reviewing a 7 dividend fortresses that focuses on higher yields with a focus on durability.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com