
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
What Cracker Barrel Stock Price Outlook Means For Shareholders
- Cracker Barrel Old Country Store reported fourth quarter sales of US$849.34 million and net income of US$12.2 million, while affirming a quarterly dividend of US$0.25 per share and issuing fiscal 2027 revenue guidance of US$3.325 billion to US$3.4 billion.
- The business is pairing value-focused pricing moves, including planned menu increases alongside food quality improvements, with an earnings profile that some analysts currently view as attractive relative to restaurant peers.
- We now look at how Cracker Barrel's new 2027 revenue outlook could reshape the investment narrative around its ongoing transformation.
Cracker Barrel Old Country Store Investment Narrative Recap
To own Cracker Barrel Old Country Store, you need to believe the refresh of the restaurants, menu and pricing can support steadier traffic and healthier margins despite a softer consumer backdrop. The latest quarter shows sales at US$849.34 million, slightly below last year, while quarterly net income rose to US$12.2 million, which helps the transformation story but does not settle it.
The key near term swing factor is whether planned price increases and food upgrades keep guests coming without hurting perceived value. The biggest risk remains pressure on spending plus higher costs, from supply chain to interest expense on refinancing, which together could offset operational improvements if traffic or check growth disappoints.
The new fiscal 2027 revenue outlook of US$3.325 billion to US$3.4 billion is the clearest operational signal in this update. It provides a yardstick to judge whether menu pricing, guest experience work and store remodels are actually moving the needle, especially after full year sales of US$3,318.71 million and lower annual net income of US$31.68 million.
For a catalyst driven thesis in Cracker Barrel Old Country Store, that guidance ties directly into execution on value focused pricing and cost efficiency. If reported revenue over the next few quarters tracks that range while cost pressures, supply issues and elevated corporate expenses stay contained, it would support the case that the current transformation is gaining traction.
Cracker Barrel Old Country Store's current analyst storyline points to revenue of US$3.6b and earnings of US$62.0 million by 2029, based on an assumed 2.6% yearly revenue growth rate and a move from US$31.7 million of earnings today. That implies roughly a US$30.3 million increase in earnings from current levels to the consensus forecast.
Uncover why Cracker Barrel Old Country Store's fair value points to a 4% potential downside to its current price, suggesting that this premium may not hold.
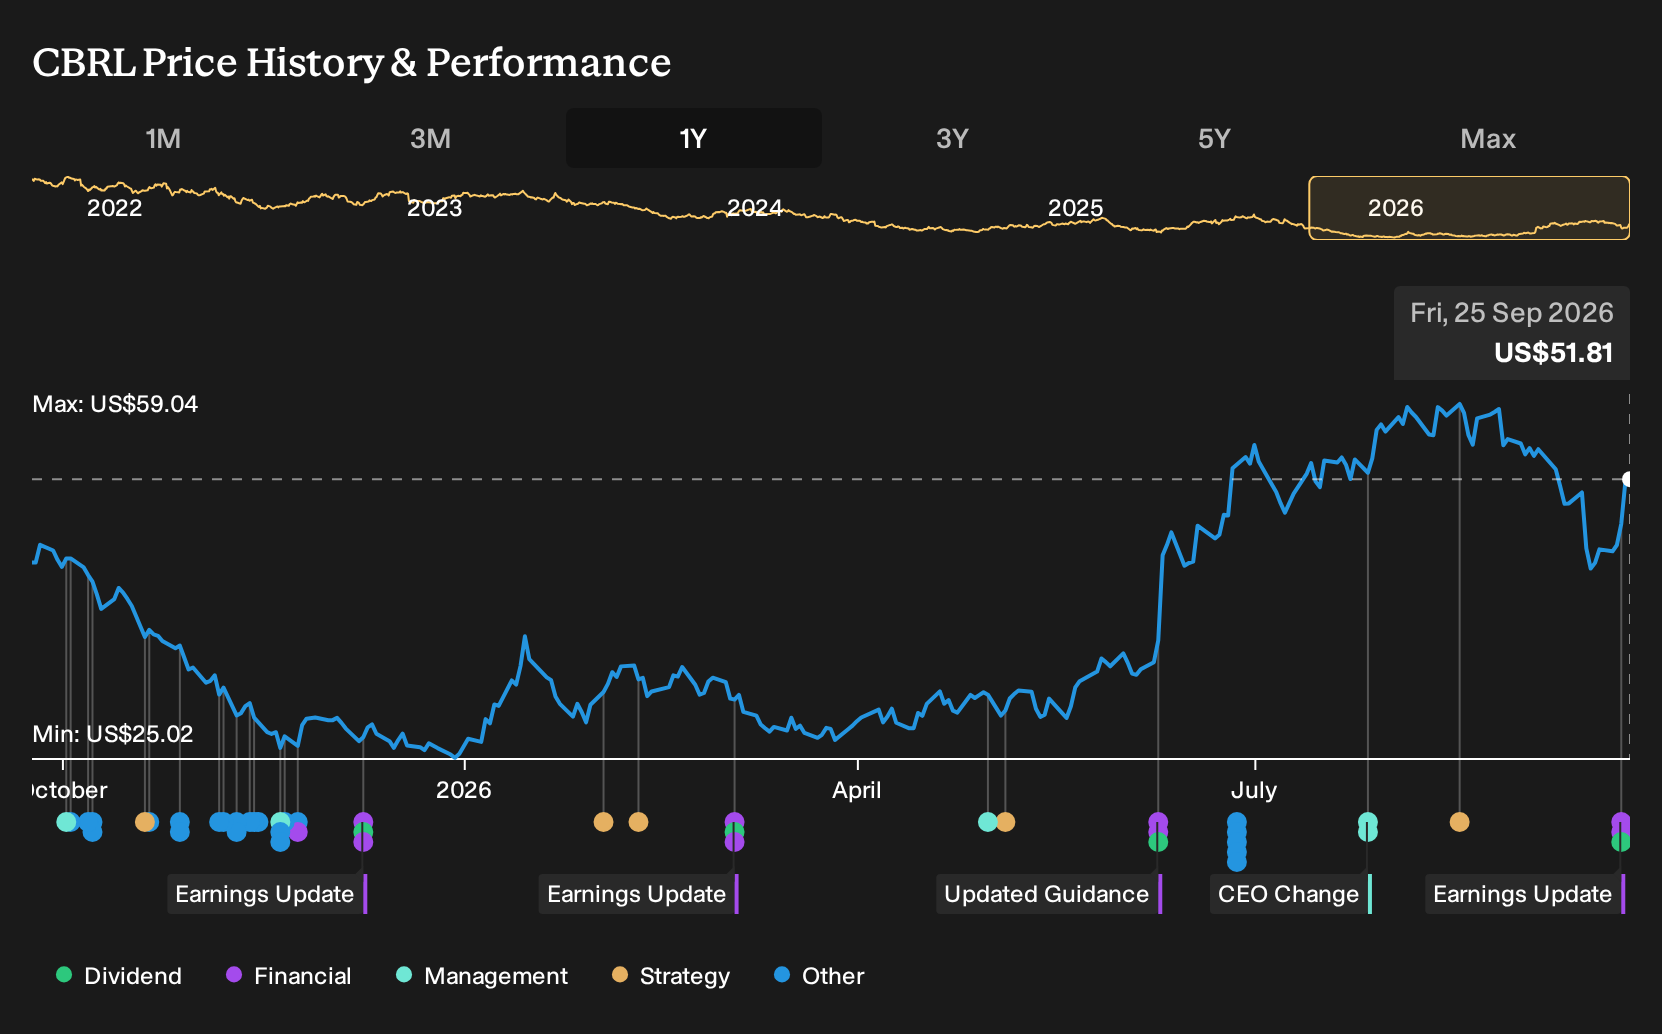
Exploring Other Perspectives
Some of the most optimistic analysts anchor their view to a very different catalyst. They focus on cost efficiencies and modernization at Cracker Barrel Old Country Store, expecting revenue of about US$3.6b and earnings near US$65.4 million by 2029. Those projections were set before this earnings release, so you should expect opinions to shift as new data comes through.
Explore 3 other Cracker Barrel Old Country Store fair value estimates, including one that suggests potential upside of as much as 15% from the current price.
Reach Your Own Conclusion
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Cracker Barrel Old Country Store research is our analysis highlighting 1 key reward and 3 important warning signs that could impact your investment decision.
- See our latest analysis for Cracker Barrel Old Country Store. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Cracker Barrel Old Country Store's overall financial health at a glance.
Looking for more investment ideas beyond Cracker Barrel Old Country Store?
If the Cracker Barrel Old Country Store story has sharpened your thinking on value, income and balance sheet strength, it can be useful to compare it with other opportunities using the Simply Wall St Screener.
- For investors looking for quality at a discount, compare Cracker Barrel Old Country Store with a broader pool of fundamentally strong stocks using the 32 high quality undervalued stocks.
- If income resilience matters to you, consider Cracker Barrel Old Country Store's payout alongside companies identified as 7 dividend fortresses that may offer more dependable yield profiles.
- To focus on financial durability, compare Cracker Barrel Old Country Store with businesses highlighted in our 30 resilient stocks with low risk scores and see which balance sheets you are most comfortable owning.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com