
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Origin Bancorp (OBK) Could Be 8% Undervalued As Valuation Debate Builds
Origin Bancorp (OBK) has drawn fresh attention after recent trading left the shares around $53.64, with investors weighing its roughly $1.65b market value against its annual revenue and net income figures.
Recent trading puts Origin Bancorp on a firm upward path, with a year to date share price return of 42.5% and a 90 day share price gain of 4.9% pointing to building momentum rather than a short spike. In that context, the 1 year total shareholder return of 56.5% and 3 year total shareholder return close to a 2x gain show how dividend income and price appreciation have combined over time as investors reassess both growth potential and risk around the bank’s earnings profile.
Scan other regionally focused lenders that show similar momentum and balance sheet scale using the hand-picked list of solid balance sheet and fundamentals (24 results).
After a run that has taken Origin Bancorp close to its recent price target and lifted multi year returns, the real tension now sits in the valuation: is most of the upside already in the rearview mirror, or not yet priced in?
Most Popular Narrative: 7.5% Undervalued
Against the last close at $53.64, the most followed valuation narrative for Origin Bancorp points to a fair value of $58, which frames the current share price as modestly below that estimate and puts the focus on what might justify the gap.
The analysts have a consensus price target of $58.0 for Origin Bancorp based on their expectations of its future earnings growth, profit margins and other risk factors. In order for you to agree with the analysts, you would need to believe that by 2029, revenues will be $574.7 million, earnings will come to $178.8 million, and it would be trading on a PE ratio of 11.9x, assuming you use a discount rate of 7.1%.
See why 0 investors see Origin Bancorp as 8% undervalued.
Result: Fair Value of $58 (UNDERVALUED)
Still, Origin Bancorp’s heavy tilt toward Southern regional markets and sizeable commercial real estate exposure could quickly challenge this 7.5% undervalued story.
Find out about the key risks to this Origin Bancorp narrative.
Another View On Origin Bancorp’s Valuation
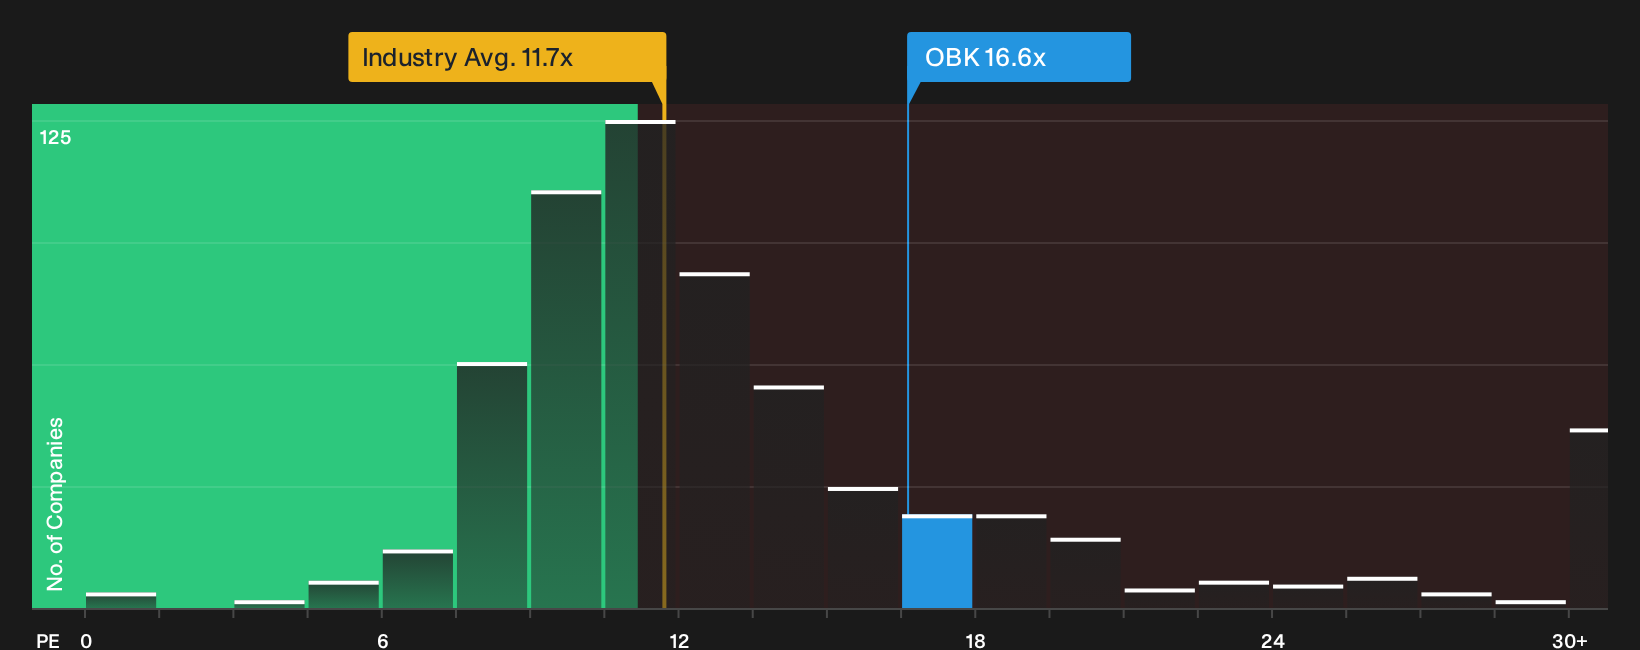
The most followed story casts Origin Bancorp as modestly undervalued, yet its P/E of 16.6x tells a different story. That figure is higher than the US Banks industry at 11.7x and above a fair ratio of 13.1x, which points to richer pricing and less room for error if sentiment cools.
For a deeper look at what this pricing gap might mean in practice, including how earnings, risk and return expectations line up with that P/E, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
If this Origin Bancorp story feels finely balanced, act promptly and test the assumptions against your own expectations using the 3 key rewards.
Looking for more investment ideas beyond Origin Bancorp?
Do not stop your research with Origin Bancorp. Broaden your watchlist now by running a few focused screens that surface fresh opportunities before they move.
- Target resilience first and hunt for companies with strong balance sheets and clean fundamentals using the list of solid balance sheet and fundamentals (24 results).
- Spot potential value gaps early and sift through companies that appear attractively priced with the 32 high quality undervalued stocks.
- Build a cash flow focused watchlist and zero in on companies via the 7 dividend fortresses.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com