
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Ahead of Micron Earnings, Here's What Barchart Data Says Comes Next for MU Stock
Micron Technology (MU) stock has been pushing higher ahead of the memory chipmaker’s fiscal Q4 earnings scheduled to be released on Sept. 30. Consensus is for MU to record $31.24 per share of earnings for its fourth financial quarter, which would represent a rather remarkable 992% increase on a year-over-year basis.
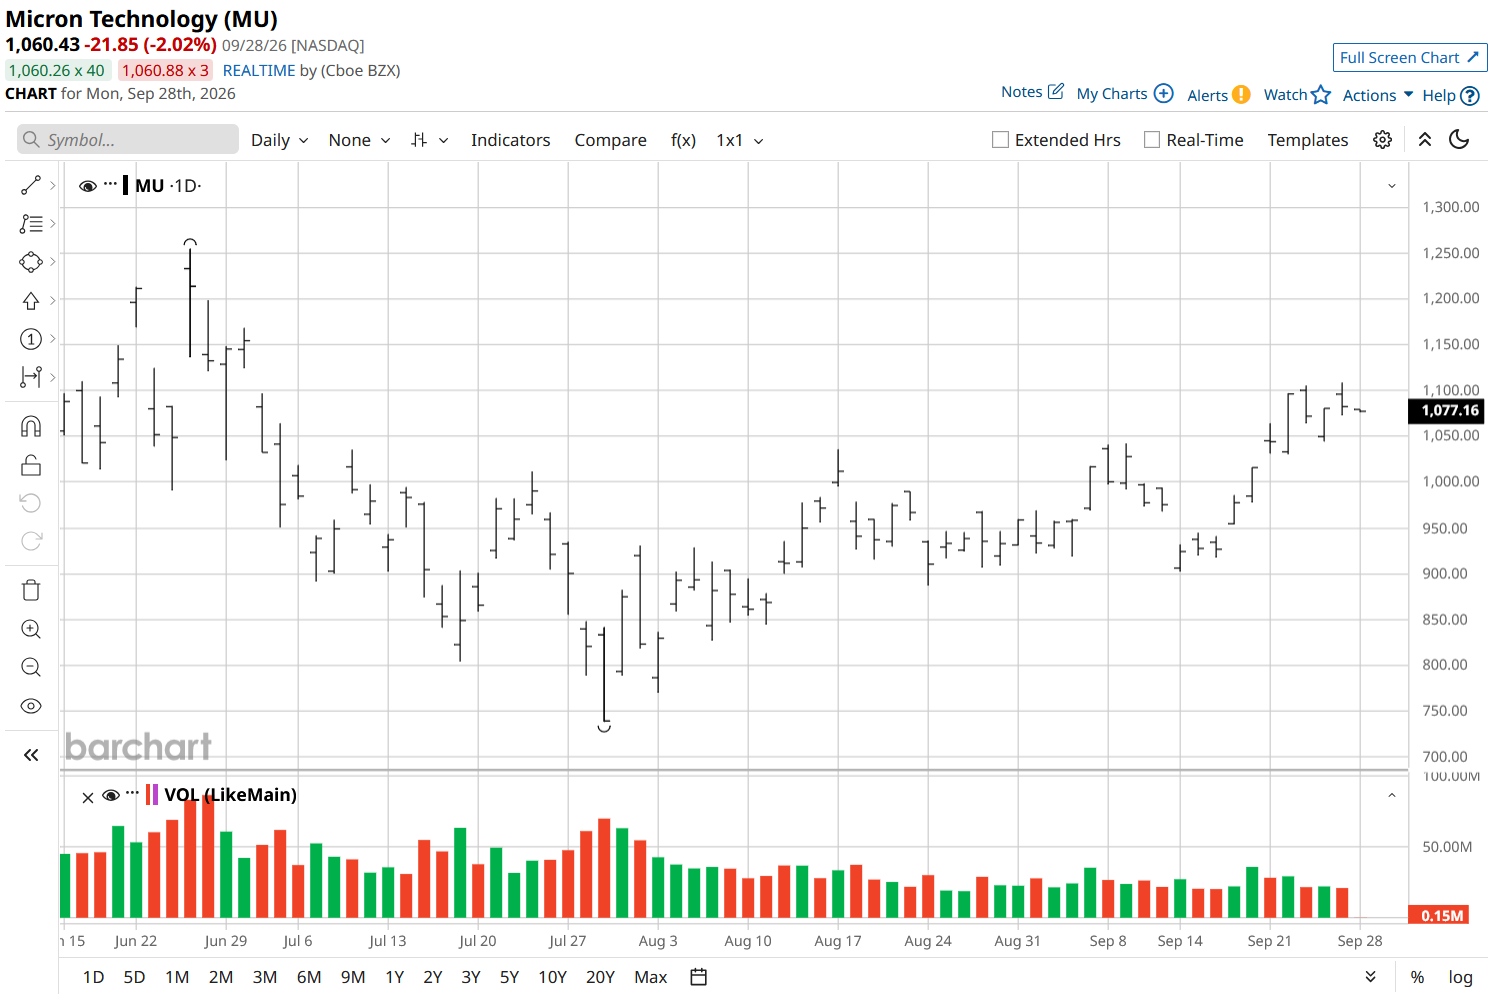
Heading into the quarterly print, Micron shares are trading at more than 3x their price at the start of 2026.
Options Sentiment Is Bearish for the Near Term
Given the outstanding year-to-date performance, the options market believes Micron’s quarterly report will likely trigger a classic sell-the-news reaction in the near term.
According to Barchart, the put-to-call ratio on contracts expiring Oct. 2 sits at 1.7x as of writing, indicating a very strong bearish skew. The data also pegs the lower price on those derivative contracts at $1,003, signaling potential for a more than 7% decline immediately after the Q4 release.
Investors should also note that MU shares’ relative strength index (RSI) currently sits in the mid-60s, pointing to approaching overbought conditions that often trigger profit-taking in the near term.
Baird Remains Bullish on Micron Stock
In the medium- to longer-term, however, Micron stock remains just as attractive, according to Baird’s senior analyst Tristan Gerra.
In a research note just days ahead of the quarterly release, Gerra maintained his “Outperform” rating on the Boise-headquartered firm and raised his price target to $1,520.
He attributed the bullish view to “1) the recent surge in agentic AI demand driving CPU demand and which we expect will be ongoing next year, 2) a deceleration in DRAM supply bit growth outlook industrywide for 2027, 3) a higher margin profile expected for HBM next year.”
Micron Technology has a history of closing each of the final three months of the year in the green — a seasonal pattern that makes it even more attractive for the near term.
What’s the Consensus Rating on MU Shares?
Other Wall Street analysts also agree with Baird’s constructive stance on Micron Technology.
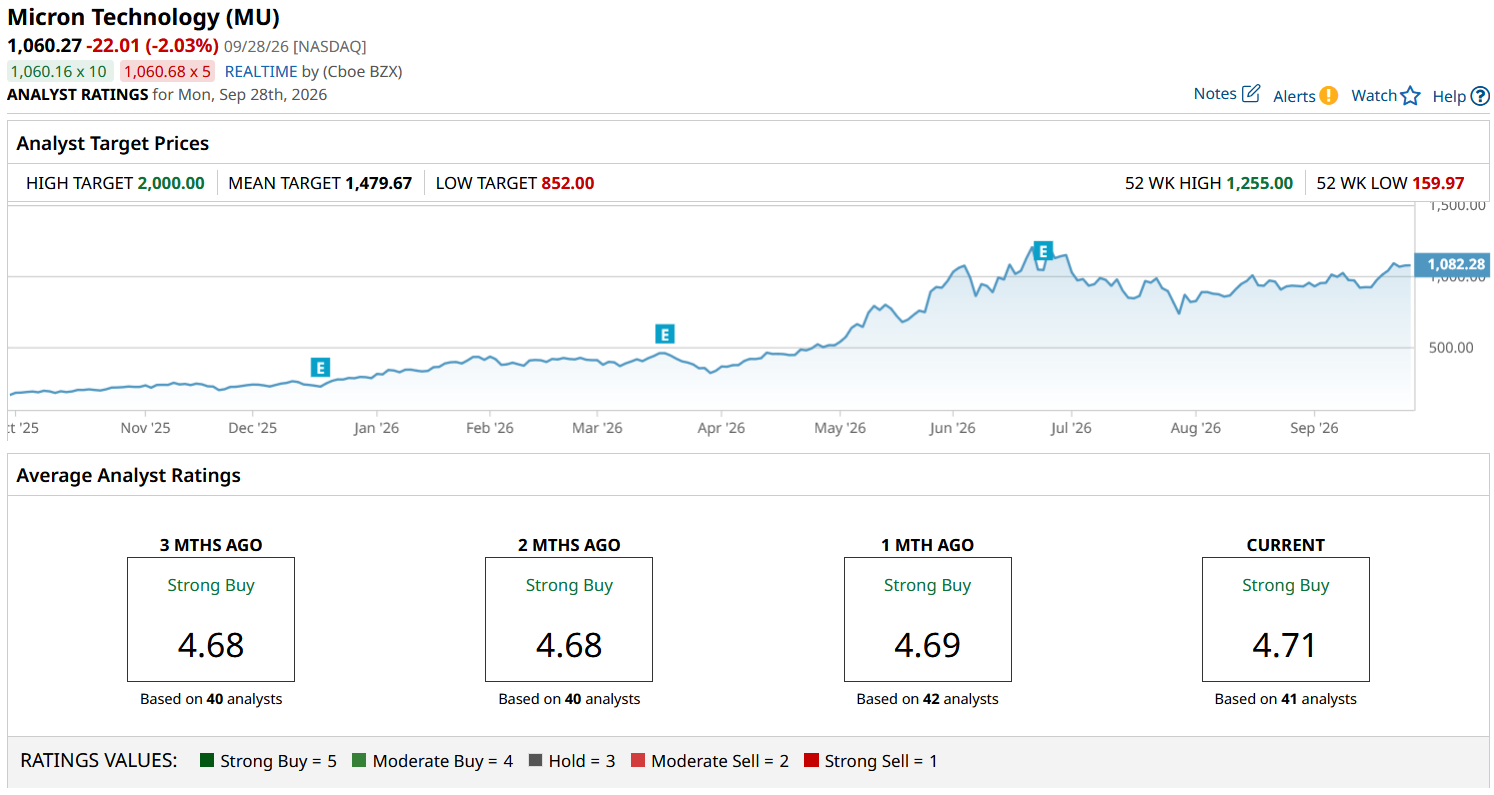
The consensus rating on MU stock sits at “Strong Buy,” with the mean price target of about $1,480 indicating potential upside of more than 35% from current levels.
On the date of publication, Wajeeh Khan did not have (either directly or indirectly) positions in any of the securities mentioned in this article. All information and data in this article is solely for informational purposes. For more information please view the Barchart Disclosure Policy here.