
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
3 US Stocks With Steady Cash Flow When Inflation Stays Stubborn
Inflation that refuses to settle, higher tariffs feeding through to prices and oil disruptions pushing up everyday costs all keep pressure on both households and the Federal Reserve. That mix creates stress for some companies and a potential opening for others that throw off cash and pay investors regularly. This article walks through three stocks from a defensive, cash-generating US screener that appear especially exposed to these Trumpflation themes.
The three examples below are just a sample from this theme, with the full screen surfacing 18 more US companies with equally compelling cash generation and balance sheet stories that are not covered here. To go straight to the source and identify which ideas best fit your own risk and income goals, analyze the Defensive, Cash-Generating Value Stocks in the US screener.
Cabot (CBT)
Overview: Cabot Corporation supplies specialty carbons and performance materials used in tires, batteries and industrial products, giving income-focused portfolios exposure to cash generative industrial demand.
Operations: Cabot generates about US$2.2b from Reinforcement Materials and US$1.3b from Performance Chemicals, with meaningful exposure across Asia Pacific, the Americas and EMEA.
Market Cap: US$4.1b
Cabot matters for this defensive, cash-generating screen because it couples a long-established industrial footprint with the sort of recurring cash flows and dividends that can help steady a portfolio when inflation and rates stay higher for longer.
"Rising energy and transportation costs and potential further volatility in oil linked feedstocks, even with pass-through mechanisms and recent price increases of up to 20% in Specialty Carbons and Specialty Compounds, could outpace Cabot's ability to reprice contracts and weigh on segment gross profit per ton and overall net margins."
What ultimately happens to Cabot’s income profile could hinge on how one less visible cost pressure plays out against that cash engine.
If that cost pressure is the real swing factor, read the full narrative for Cabot to see how Cabot could still accelerate its cash engine under Trumpflation.

STERIS (STE)
Overview: STERIS provides infection prevention equipment, chemistries and services to hospitals and drug manufacturers, giving portfolios healthcare exposure with recurring cash flows.
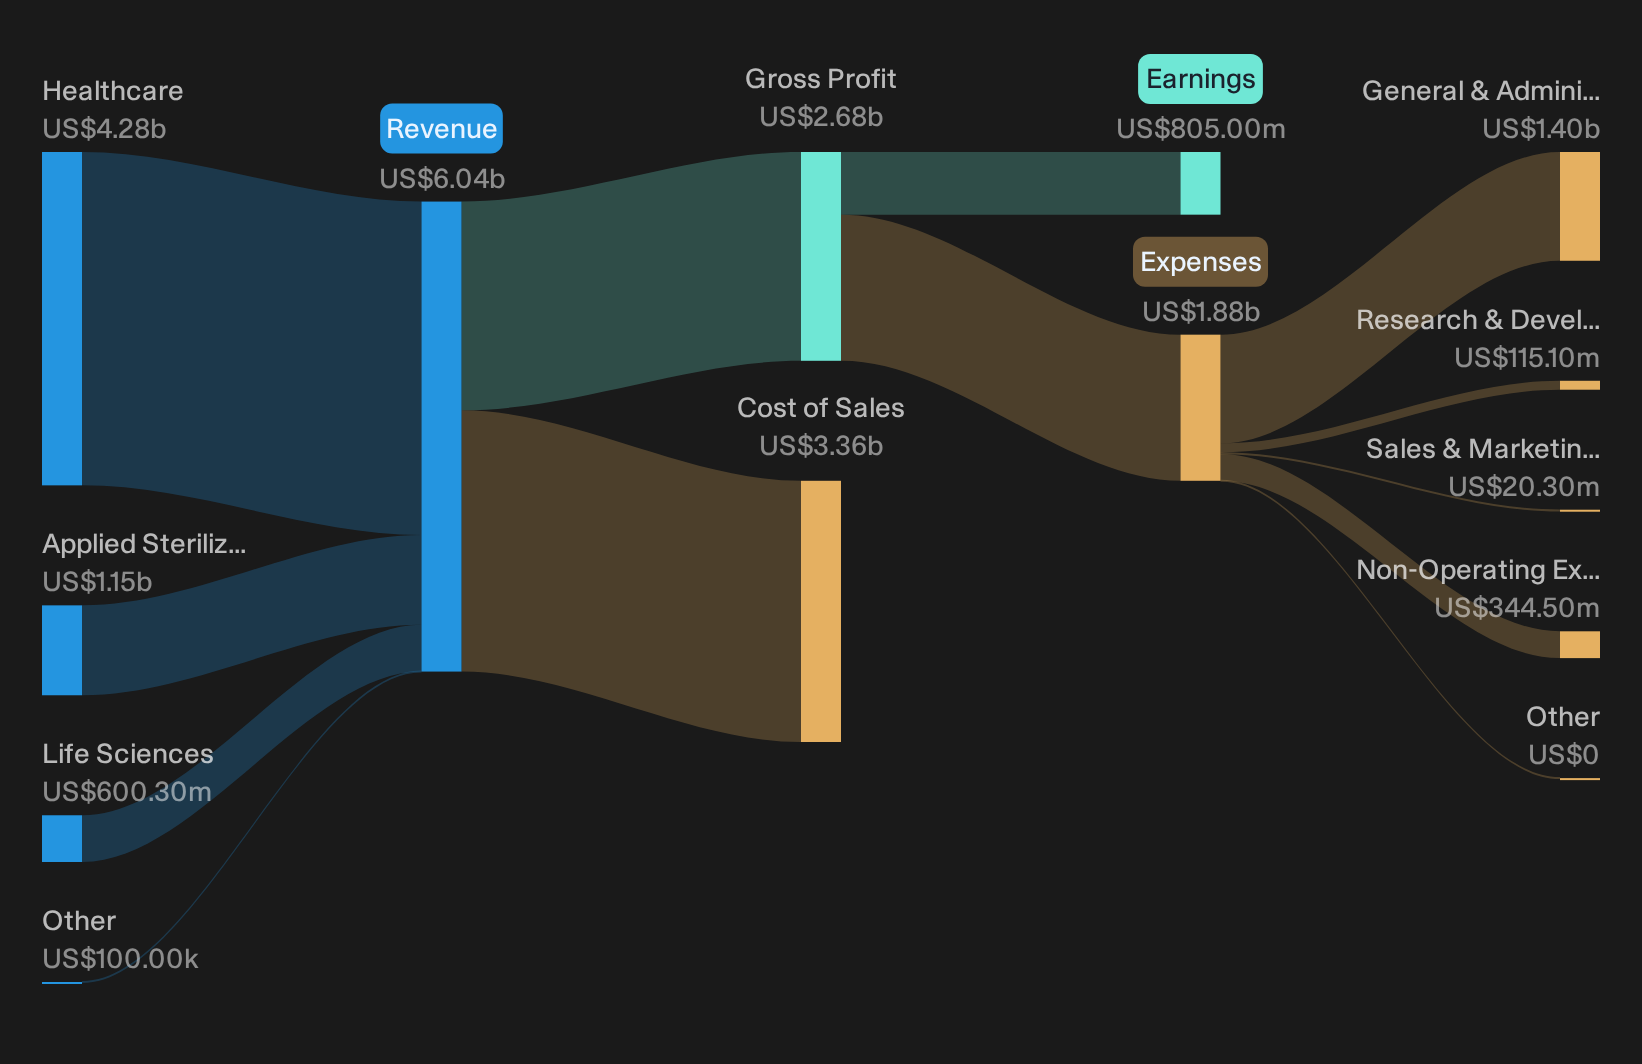
Operations: STERIS generates about US$4.3b from Healthcare, US$1.2b from Applied Sterilization Technologies and US$600 million from Life Sciences, with US$4.4b from the United States.
Market Cap: US$20.4b
STERIS fits this defensive, cash-generating theme because hospitals, device makers and drug producers still need infection control even when inflation, tariffs and higher-for-longer rates squeeze budgets elsewhere.
"Continued mix shift toward recurring chemistries and services, which now account for roughly 80% of STERIS revenue versus about 20% a decade ago, can add stability to organic revenue and support operating leverage into earnings."
How a single cost pressure might quietly undercut that earnings leverage will be an important factor in determining how defensive STERIS ultimately feels.
That quiet pressure is exactly where the story gets interesting, and the full narrative for STERIS shows how STERIS could keep recurring revenue accelerating, even if costs creep higher.
Kraft Heinz (KHC)
Overview: Kraft Heinz is a global packaged food and beverage producer whose brands stock everyday kitchens, cafeterias and restaurants worldwide.
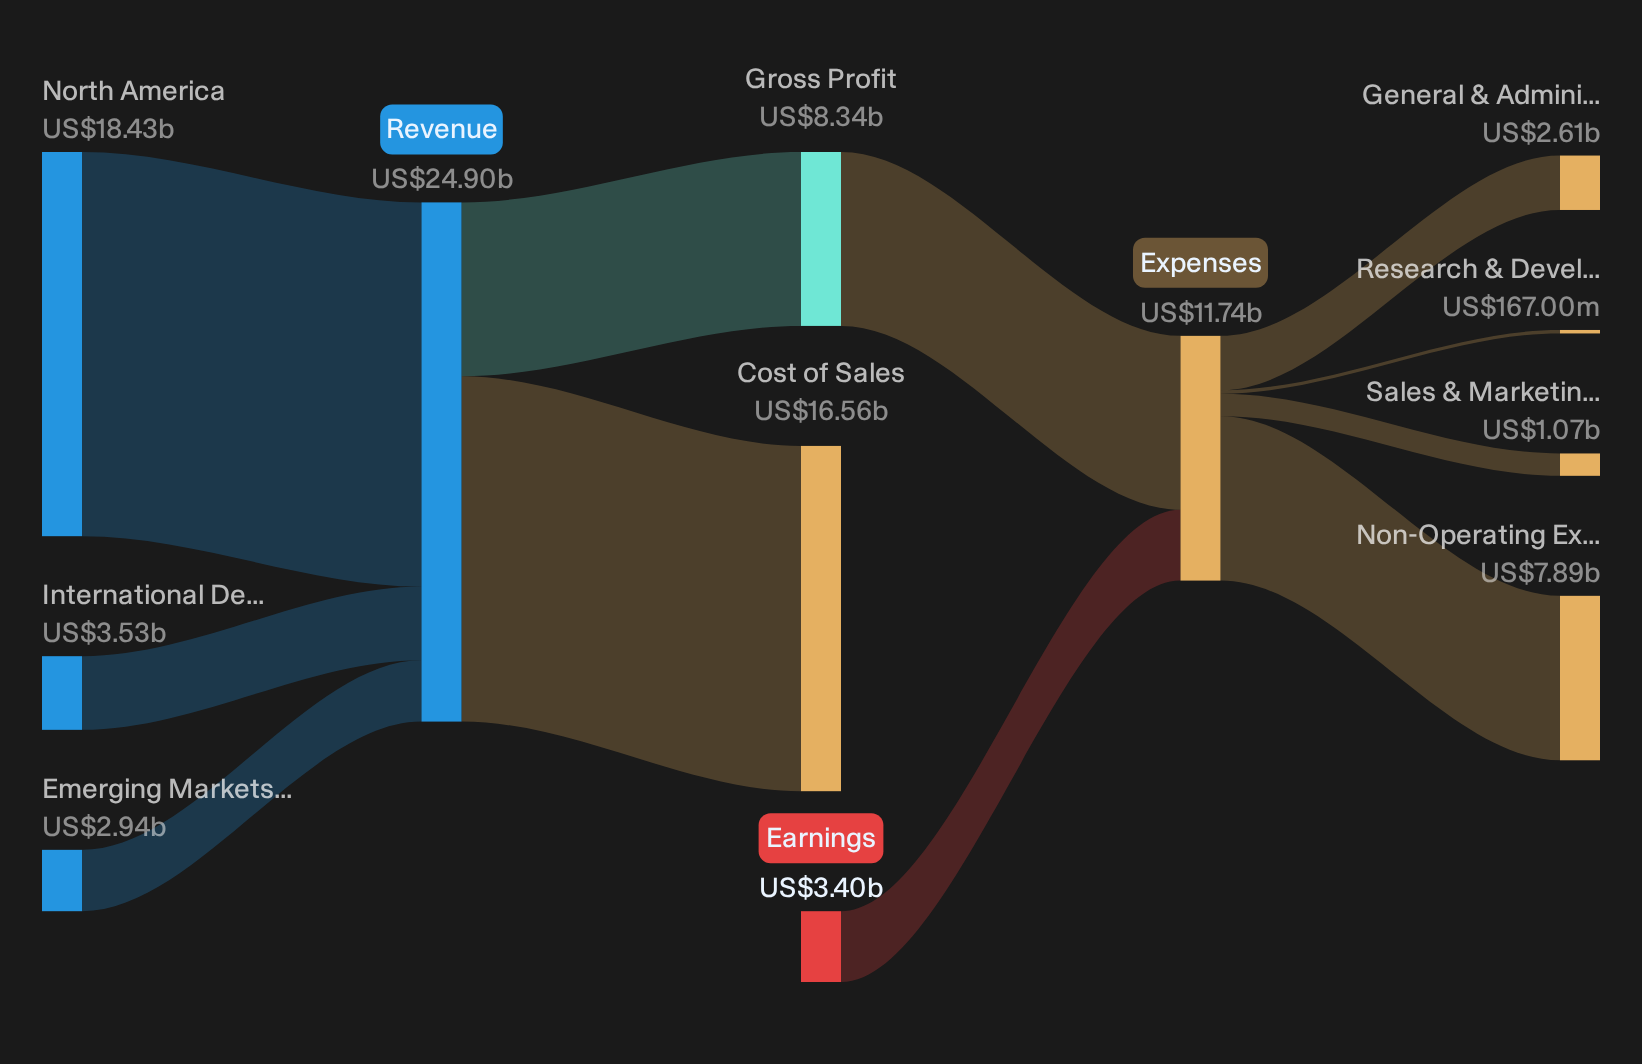
Operations: Kraft Heinz generates about US$18.4b of revenue from North America, US$3.5b from International Developed Markets and US$2.9b from Emerging Markets.
Market Cap: US$28.0b
For a defensive, cash-generating screen, Kraft Heinz matters because everyday staples like ketchup, cheese and coffee often keep selling even when rates stay high and inflation keeps nibbling at household budgets.
"The company continues to emphasize productivity, cash generation, debt reduction, and leverage discipline, with net leverage expected to be no higher than 3.3x this year and a stated path back to target within roughly two years."
What investors really need to watch is how one less visible cost pressure shapes the balance between that discipline and long term margin resilience.
That quiet cost pressure is exactly why the full narrative for Kraft Heinz lays out how Kraft Heinz could keep cash generation resilient while margins evolve under Trumpflation.
Curious To Explore Powerful Alternatives?
Fresh stock ideas can move from quiet to breakout fast, and opportunities are often identified by early movers. Scan these curated screens before the crowd and consider your next steps.
- Target durable income streams while inflation bites by reviewing a curated group of high payout opportunities through the 7 dividend fortresses.
- Look for potential future compounders by scanning a tight shortlist of resilient balance sheets with the list of solid balance sheet and fundamentals (24 results).
- Explore the early momentum in infrastructure demand by checking a focused basket of enablers through the 40 power grid technology and infrastructure stocks.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com