
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Enbridge (TSX:ENB) Stock Looks Fully Valued At Current Earnings Levels
Enbridge has delivered a strong 82.2% share price gain over the past three years, which naturally raises the question of whether today's valuation still lines up with the earnings power behind the stock. For investors who already own Enbridge, or are considering it, the key issue now is how much of that earnings profile is already reflected in the current price.
- The 82.2% move over three years puts real weight on the question of whether Enbridge's earnings can support the current share price.
- With a business built around long term energy infrastructure and contracted cash flows, the durability and timing of those earnings can influence how much you might be willing to pay for each dollar of profit.
- Your read on Enbridge is one view; the desks covering it have another. See what analysts think Enbridge's shares could be worth.
The issue now is whether Enbridge's current share price of $66.13 is justified by the earnings it generates today and what investors expect those profits to look like over time.
If you are weighing Enbridge against other earnings focused ideas, it can help to see how similar themes show up in a broader set of stocks using the 5 high quality undervalued stocks
Is Enbridge Fairly Priced on Earnings?
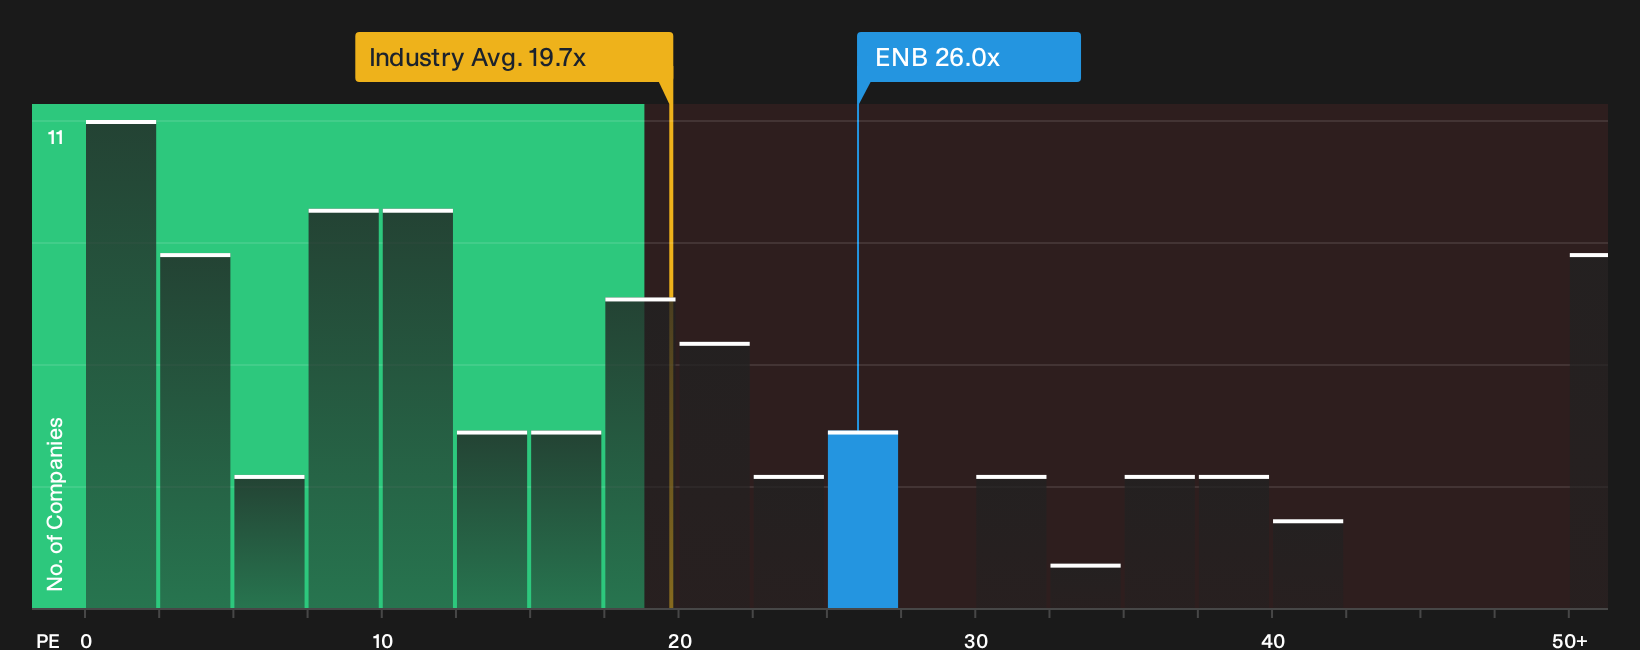
The P/E ratio is a useful lens here because Enbridge is already profit generating, so you can compare what you pay today with each dollar of earnings. On this measure, the stock trades on roughly 26.0x earnings, very close to both its peer average of about 25.9x and above the broader Oil and Gas sector on roughly 19.7x.
The valuation model suggests a P/E level that already reflects Enbridge's mix of growth profile, margins, size and risk. The current multiple sits near that implied range. That leaves you weighing whether the stability of its long-term infrastructure assets and contracted cash flows justifies paying a similar earnings multiple to peers, even though the sector as a whole trades on lower ratios. Explore the numbers behind Enbridge's P/E valuation.
The Enbridge Narrative: What Would Justify Today's Price?
Simply Wall St Narratives pick up where the Enbridge valuation puzzle leaves off by setting out which paths for future earnings, profit margins and growth would need to play out for the stock to be worth materially more or materially less than today’s price. Rather than relying on a single P/E or one model output, each scenario lays out the assumptions that sit behind its view of fair value so you can compare those expectations with Enbridge's actual results on the Community page as they come through.
Community views on Enbridge are split between those who see regulated assets and projects as underappreciated and those who think quality is already reflected in the price.
Bull case: 17% undervalued
"Early investment in decarbonization initiatives such as hydrogen, renewable natural gas, and storage and the ability to secure blue-chip customers like Meta, Amazon, and AT&T for long-term contracts diversifies and grows revenue streams."
Discover why this Narrative puts Enbridge at 17% undervalued.
Bear case: 41% overvalued
"The company benefits from scale and low-cost advantages, but its exposure to commodity prices limits its pricing power, making the moat acceptable but not exceptional."
Explore why this Narrative puts Enbridge at 41% overvalued.
Before you move on, there is one more angle on Enbridge to check
Enbridge's valuation story is only part of the picture, because recent research has also picked up specific risk checks that could influence how you weigh the trade off between price and quality. Take a closer look at 2 warning signs (2 major) before settling on a valuation.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com