
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Why Everyone Is Watching Mitsubishi Estate (TSE:8802) Today
Mitsubishi Estate (TSE:8802) continues to attract attention as investors weigh its recent share performance, including a decline of about 5% over the past month and roughly 12% over the past 3 months.
That recent slide fits into a mixed picture for Mitsubishi Estate, with the latest share price at ¥3,639 and short term share price momentum fading, while longer term total shareholder returns over 1, 3 and 5 years remain positive and relatively strong.
See how Mitsubishi Estate compares to other real estate developers by reviewing a curated set of list of solid balance sheet and fundamentals (22 results).
Mitsubishi Estate has slid while analyst targets and intrinsic estimates still point higher, creating a wide gap between market mood and calculated worth. Where does fair value realistically line up in that spread?
Price-to-Earnings of 15.3x: Is it justified?
Mitsubishi Estate closed at ¥3,639 with a P/E of 15.3x, which puts the stock on a richer valuation than many real estate peers and signals investors are paying up for each unit of current earnings.
The P/E ratio compares the share price with earnings per share and helps you see how much the market is willing to pay for the company’s current profit stream. For property developers and landlords, this often reflects expectations around rental income resilience, asset recycling, and how steady cash generation might be.
For Mitsubishi Estate, a 15.3x P/E is described as expensive against both the Japan real estate industry average of 10x and a peer group average of 12.3x. The fair P/E estimate of 16.1x is slightly higher than where the shares trade, which suggests the ratio could still move closer to that level if earnings and sentiment line up with this assessment.
Explore the SWS fair ratio for Mitsubishi Estate.
Result: Price-to-Earnings of 15.3x (OVERVALUED)
Still, that richer P/E can come under pressure if Mitsubishi Estate sees weaker demand in its core Marunouchi offices or slower rental activity across commercial properties.
Find out about the key risks to this Mitsubishi Estate narrative.
Another View on Mitsubishi Estate’s Value
The first lens makes Mitsubishi Estate look expensive on a P/E of 15.3x, yet the SWS DCF model tells a slightly different story. On that framework, the current price of ¥3,639 sits just above an estimated future cash flow value of ¥3,609.46, which points to a mildly overvalued reading. Which signal should carry more weight for you?
Look into how the SWS DCF model arrives at its fair value.
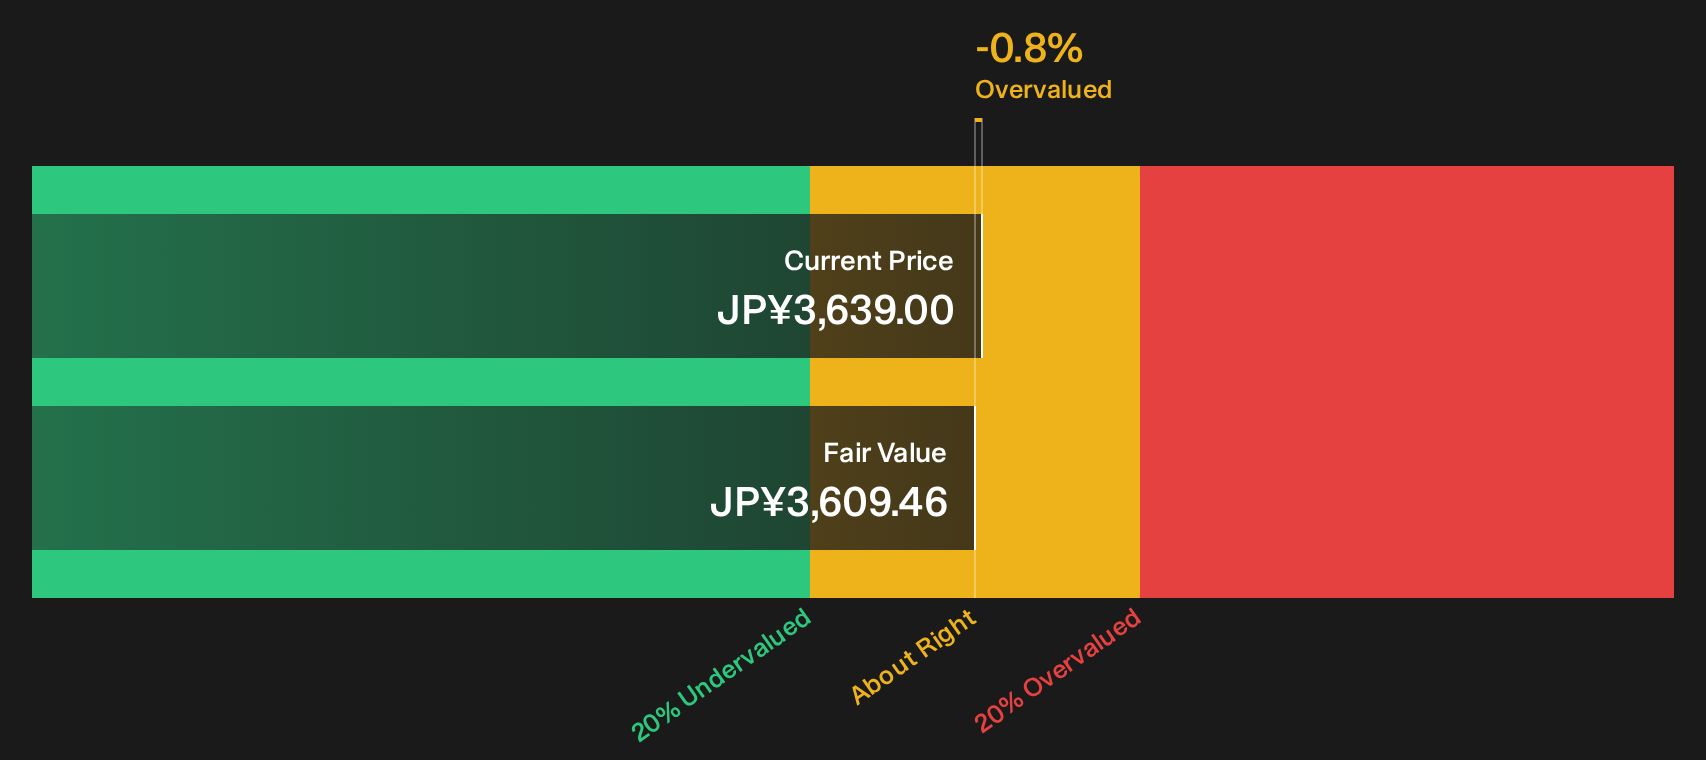
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Mitsubishi Estate for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 17 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals around Mitsubishi Estate’s valuation and outlook only matter if you act on them. Take a closer look at the data, weigh the concerns and positives side by side, then ground your next move in the 3 key rewards and 2 important warning signs
Looking for more Mitsubishi Estate investment ideas?
If Mitsubishi Estate has you reassessing your watchlist, use this moment to refresh your wider opportunity set with a few focused stock ideas.
Broaden your opportunity set and hunt for potential mispricings with the 17 high quality undervalued stocks.
Strengthen the income side of your portfolio by reviewing the 16 dividend fortresses.
Reduce portfolio stress and concentrate on resilience with the 21 resilient stocks with low risk scores.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com