
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Will Tax Tool Upgrades Change SEI Investments Stock Narrative
- SEI Investments announced upgrades to its integrated tax management for separately managed and unified managed accounts, expanding asset eligibility, transition options, and advisor control over capital gains realization and tax-loss harvesting.
- The focus on systemized gains budgets and broader security coverage highlights how SEI Investments is trying to align its technology platform more closely with the real-world tax planning needs of advisors and their clients.
- This article examines how SEI Investments' investment narrative is influenced by these new advisor tax controls within its portfolio platforms.
SEI Investments Investment Narrative Recap
To own SEI Investments, you need to believe that its fee based platforms, outsourcing and data tools can keep attracting assets while margins hold up as the mix tilts toward ETFs and managed accounts. The latest tax management upgrades look incremental for operations rather than a game changer, fine tuning how advisors use SEI rather than redefining the business.
In the near term, the key swing factor remains demand for outsourced administration and advisory platforms, especially from large asset managers. The biggest watchpoint is fee pressure as flows move into lower cost vehicles, which could matter more to the story than either product tweaks or recent insider selling headlines.
The tax management announcement is the clearest operational link to SEI Investments forward narrative right now. By widening coverage to mutual funds alongside ETFs and individual securities, and by systemizing gains budgets, the platform leans harder into after tax portfolio management, an area where advisors are actively looking for scalable tools.
For catalysts, this matters most if it increases stickiness of the Advisors and Institutional segments and supports attachment of higher margin services like SEI Data Cloud and professional services. The risk is that investors embrace the tax features but still push for lower all in pricing, which would keep the trade off between volume growth and fee compression front and center.
SEI Investments' current analyst script assumes revenue growth of 7.2% a year, with earnings rising from $706.9 million today to a consensus of $864.8 million by 2029. This represents an increase of about $157.9 million, alongside forecast revenues of $3.0 billion in the same year.
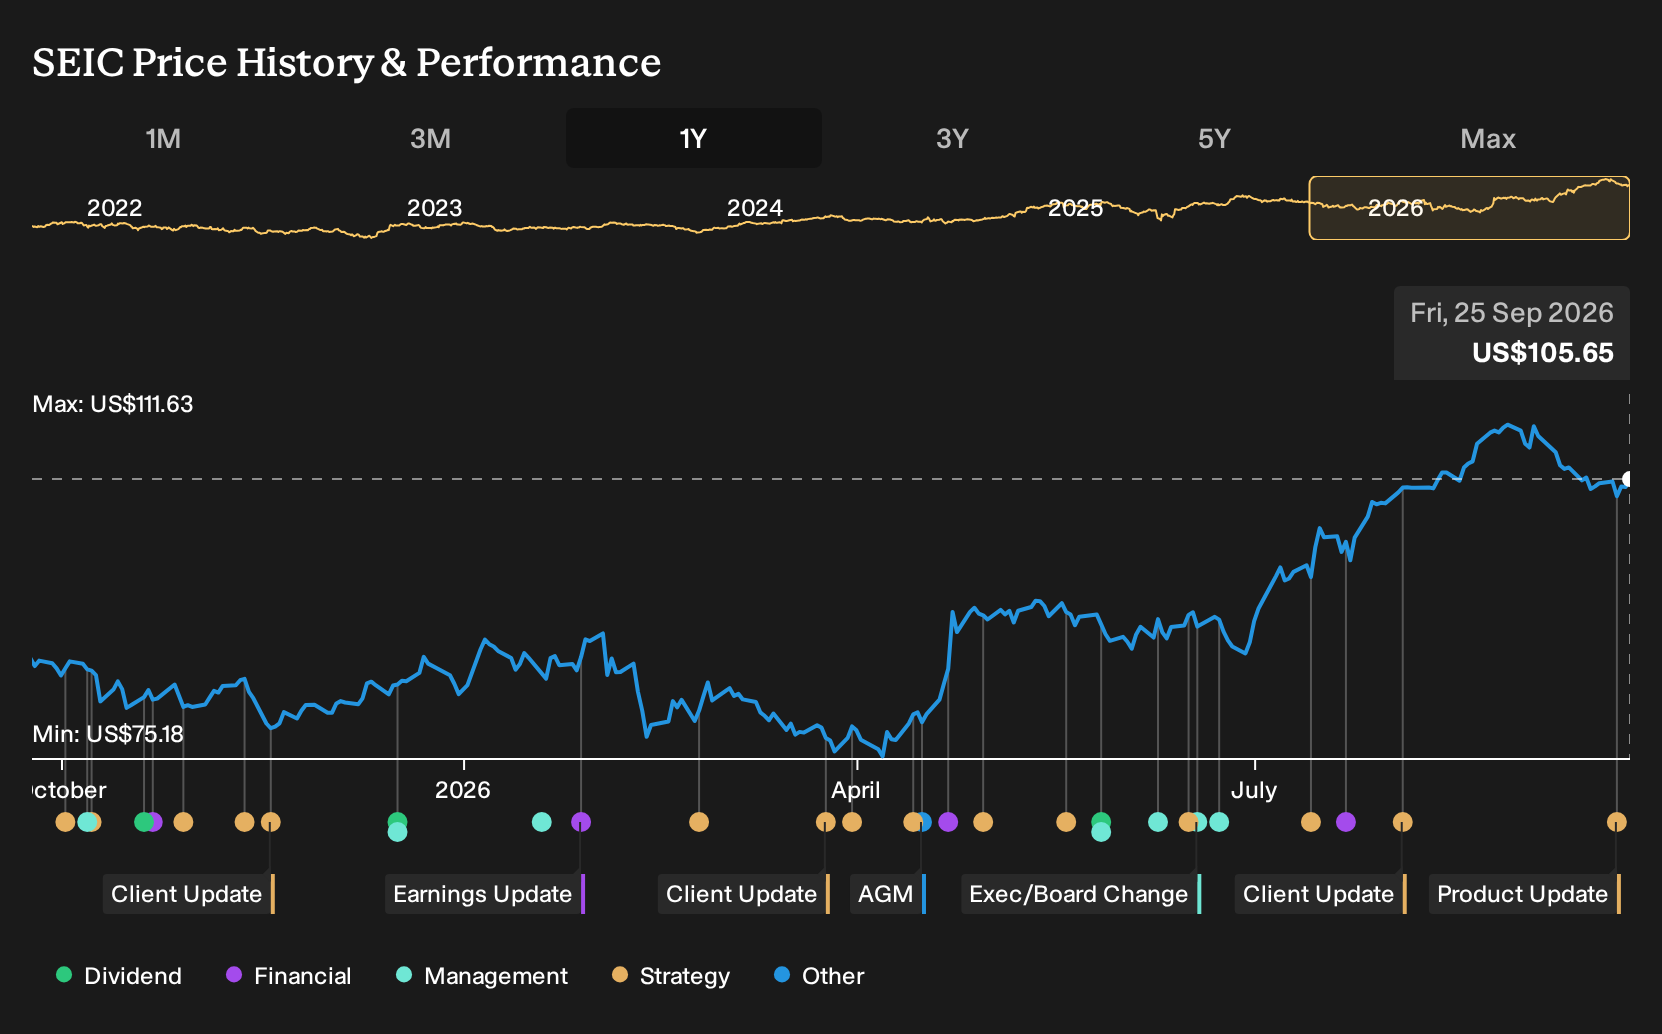
Uncover why SEI Investments' fair value indicates a 10% potential upside to its current price that could narrow quickly.
Exploring Other Perspectives
One alternate view focuses less on tax tools and more on rate sensitive income. The most pessimistic SEI Investments analysts were working off roughly 6.5% revenue growth and earnings of about $830.9 million by 2029 before this announcement, reflecting concerns about cash spread compression. That shows how sharply opinions can differ and why it helps to test several narratives yourself as new information arrives.
Explore 3 other SEI Investments fair value estimates, including one that suggests it could be worth just $101.60.
Reach Your Own Conclusion
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your SEI Investments research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for SEI Investments. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate SEI Investments' overall financial health at a glance.
Looking for more investment ideas beyond SEI Investments?
If SEI Investments has sharpened your focus on tax aware platforms and quality fundamentals, it can help to widen the lens and compare it with other opportunities that share traits like solid balance sheets, resilient cash flows, or differentiated return profiles.
- For investors who want financial strength to be the starting point, filter for companies with robust balance sheets and dependable fundamentals using our list of solid balance sheet and fundamentals (24 results).
- If value is your priority and you are hunting for quality at a sensible price, scan the 32 high quality undervalued stocks to see which stocks currently screen as high quality yet priced below their estimated worth.
- Income focused investors who care about both yield and resilience can review a curated pool of potential income payers through our 8 dividend fortresses.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com