
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
3 Copper Stocks With P E Under 31
Oil has pushed above US$108 a barrel as conflict around the Strait of Hormuz disrupts energy routes and raises costs for heavy industry. That kind of squeeze on traditional fuels makes copper even more central to data centers, power grids, and electric transport. Investors looking for exposure to this long-term buildout can use this copper-focused stock screen. This article walks through three of the strongest candidates.
The three stocks below are just a sample of what surfaces when you filter for low cost copper producers with solid balance sheets. The full screen highlights 14 more companies with equally compelling narratives that are not covered here.
If you want to identify and analyze the highest conviction opportunities right now, head straight into the Top Copper Stocks screener.
Ero Copper (TSX:ERO)
Overview: Ero Copper is a Vancouver based miner focused on Brazil, with Caraíba supplying copper concentrates and gold and silver by products.
Operations: The business generates revenue from Caraíba in Brazil at about $437 million, Tucumã $375 million, and Xavantina $232 million.
Market Cap: CA$5.6b
Ero Copper matters for this copper screen because Caraíba is a pure-play source of concentrate that directly feeds electrification and data infrastructure demand.
"The company is transitioning multiple assets (Tucumã, Xavantina, and Caraíba) to higher production and improved operational consistency after significant foundational upgrades, including mechanization and technology rollouts. These changes are expected to result in higher production volumes and improved cost control in H2 2025 and into 2026, supporting revenue growth and potentially stronger margins."
What really moves the needle for Ero Copper now is how one pressure on future profitability ultimately reshapes those margin outcomes.
That margin reset is only half the story, and the full narrative for Ero Copper shows how Ero Copper’s upgrades, capital choices, and risk pressures could be quietly reshaping future returns.

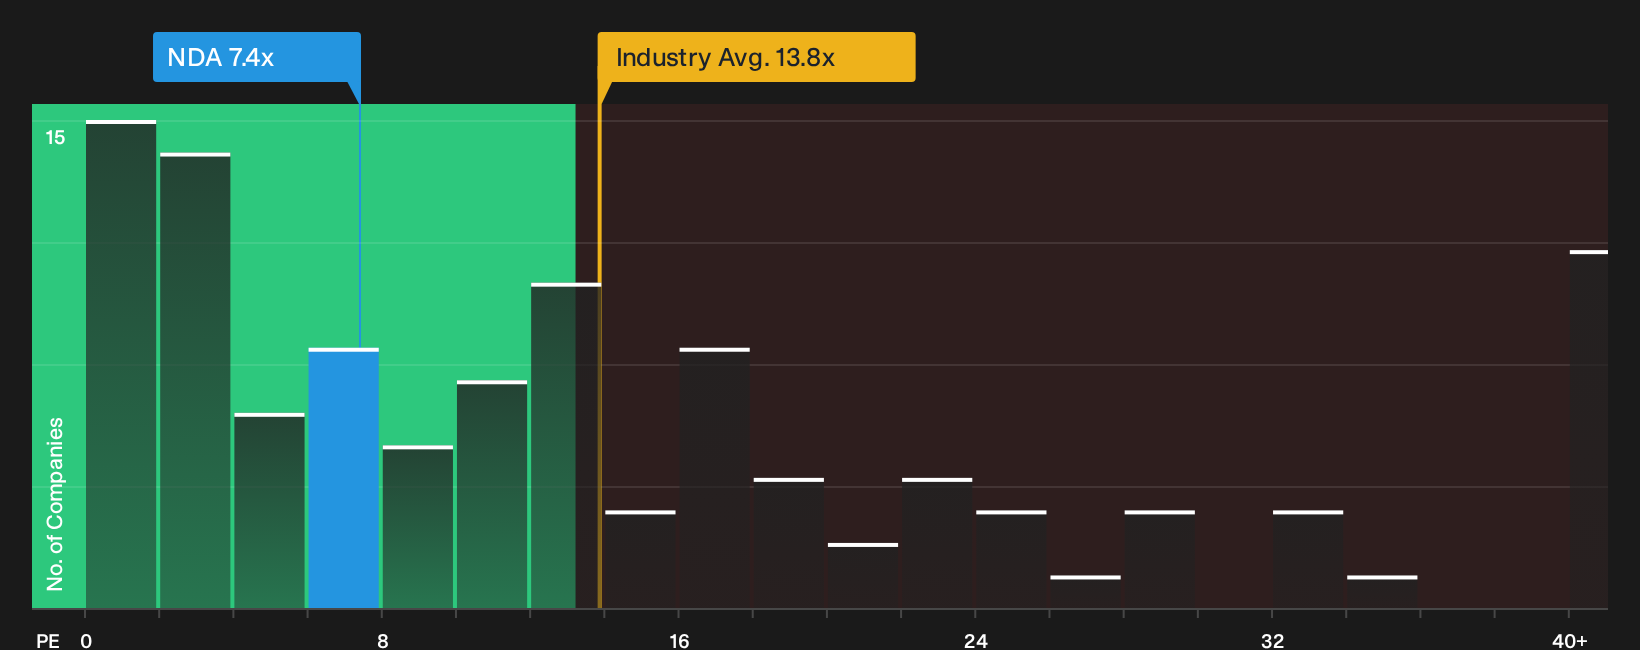
Aurubis (XTRA:NDA)
Overview: Aurubis is a Hamburg based metals processor that turns copper concentrates and recycled scrap into refined copper products and multimetal outputs.
Operations: The business generates revenue mainly from Custom Smelting & Products at €22.0b and Multimetal Recycling at €5.6b, plus a €516 million segment adjustment.
Market Cap: €7.3b
Aurubis matters for this copper screen because its large scale smelting and recycling network directly feeds refined copper into power, data, and transport supply chains.
"There is an underappreciated risk that global moves towards higher recycling rates and circular economy models, as well as potential substitution of copper in key end-markets (such as EVs and power infrastructure), could cap or reduce long-term topline growth, with these headwinds not adequately reflected in current valuation multiples or sales expectations."
What really shapes the Aurubis story now is how one pressure on future pricing power will filter through to margins when copper supply tightens.
When that pricing power starts to shift, the full narrative for Aurubis shows how Aurubis might still compound value as recycling, spreads and project timing decouple.
Southern Copper (SCCO)
Overview: Southern Copper runs large open pit mines and integrated smelting and refining facilities that turn copper ore into finished copper products.
Operations: The business generates revenue mainly from Mexican Open Pit at US$9.1b, Peruvian Operations at US$6.0b, and the IMMSA unit at US$1.1b.
Market Cap: US$172.2b
Southern Copper matters for this copper screen because its low cost open pit operations and in house processing chain are closely connected to the physical copper shortfall behind AI infrastructure and electrification.
"Southern Copper has announced substantial capital investments totaling over $15 billion, including projects in Mexico and Peru, which are expected to support future production growth and potentially increase revenue."
What really decides how much of that copper theme upside reaches shareholders is how one quiet pressure shapes future profitability.
That pressure makes it worth reading the full narrative for Southern Copper to see how Southern Copper’s investment pipeline, risk profile, and payout ambitions might be quietly decoupling.

Seeking Alternatives Before The Crowd?
Fresh ideas can move quickly when momentum builds and valuations start flying. Before these picks are caught by every screen and headline, review them while it matters and get in early.
- Scan for resilient businesses that could ride the next risk off swing with the 8 resilient stocks with low risk scores. This is useful before market attention tightens around defensive balance sheets.
- Spot potential breakout payers whose income streams might hold up even if prices start dropping, using the curated 1 dividend fortresses while yields remain under the radar for now.
- Track future facing infrastructure players supplying tools for the next AI buildout with the focused 85 AI infrastructure stocks before capital floods into the same tickers.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com