
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
3 Canadian Quality Stocks With ROE Of At Least 26%
With bond markets edging closer to a classic warning signal for the US economy, investors in Canadian equities are again paying attention to balance sheet strength instead of headlines. When growth scars appear, capital often flows toward businesses with high return on equity, resilient cash generation and low financial strain. This article spotlights three Canadian stocks from a quality-focused screener that prioritises robust fundamentals and cleaner balance sheets.
The three stocks highlighted next are just a sample. The full quality screen surfaced four more businesses with equally compelling balance sheet and profitability stories that are not covered here.
If you want to identify and analyze those extra candidates alongside your own ideas, head straight into the Solid Balance Sheet and Fundamentals screener.
Lundin Gold (TSX:LUG)
Overview: Lundin Gold is a Canadian miner whose fully owned Fruta del Norte project in Ecuador drives its gold and silver production and supports the solid balance sheet profile investors focus on in this screener.
Operations: Lundin Gold generates US$2.02b of revenue from the Fruta Del Norte operation, its flagship high grade gold mine in Ecuador.
Market Cap: CA$22.15b
Lundin Gold matters for this screen because Fruta del Norte converts high grade ore into robust cash generation, which feeds directly into return on equity and balance sheet strength.
"Market expectations appear to reflect high conviction that record gold prices will persist and continue to drive Lundin Gold's revenues and margins at current exceptional levels, neglecting the risk that gold's function as an inflation/geopolitical hedge could soften with evolving macroeconomic or technological trends, potentially exposing a downside to future revenue and earnings."
What happens to Lundin Gold’s otherwise strong fundamental story if just one external pressure quietly starts to compress its rich margin profile?
If that margin pressure question is on your mind, read the full narrative for Lundin Gold to see how Lundin Gold’s cash engine could keep accelerating or stall under different gold cycles.

Sprott (TSX:SII)
Overview: Sprott is a Toronto based asset manager that runs physically backed precious metals funds and ETFs alongside other investment products.
Operations: Sprott generates about US$224 million from Exchange Listed Products, US$95 million from Managed Equities and US$80 million from Private Strategies, mostly in Canada.
Market Cap: CA$4.5b
Sprott appears in this solid fundamentals screen because a 25.6% ROE, 26.4% net margin and strong earnings growth are all linked to a fee based, physically backed precious metals platform. This structure can support both high profitability and a clean balance sheet, depending on how one unseen pressure on that model plays out.
That hidden pressure point is exactly what the analysis report for Sprott unpacks, so you can see where Sprott’s fee engine might accelerate or stall next.

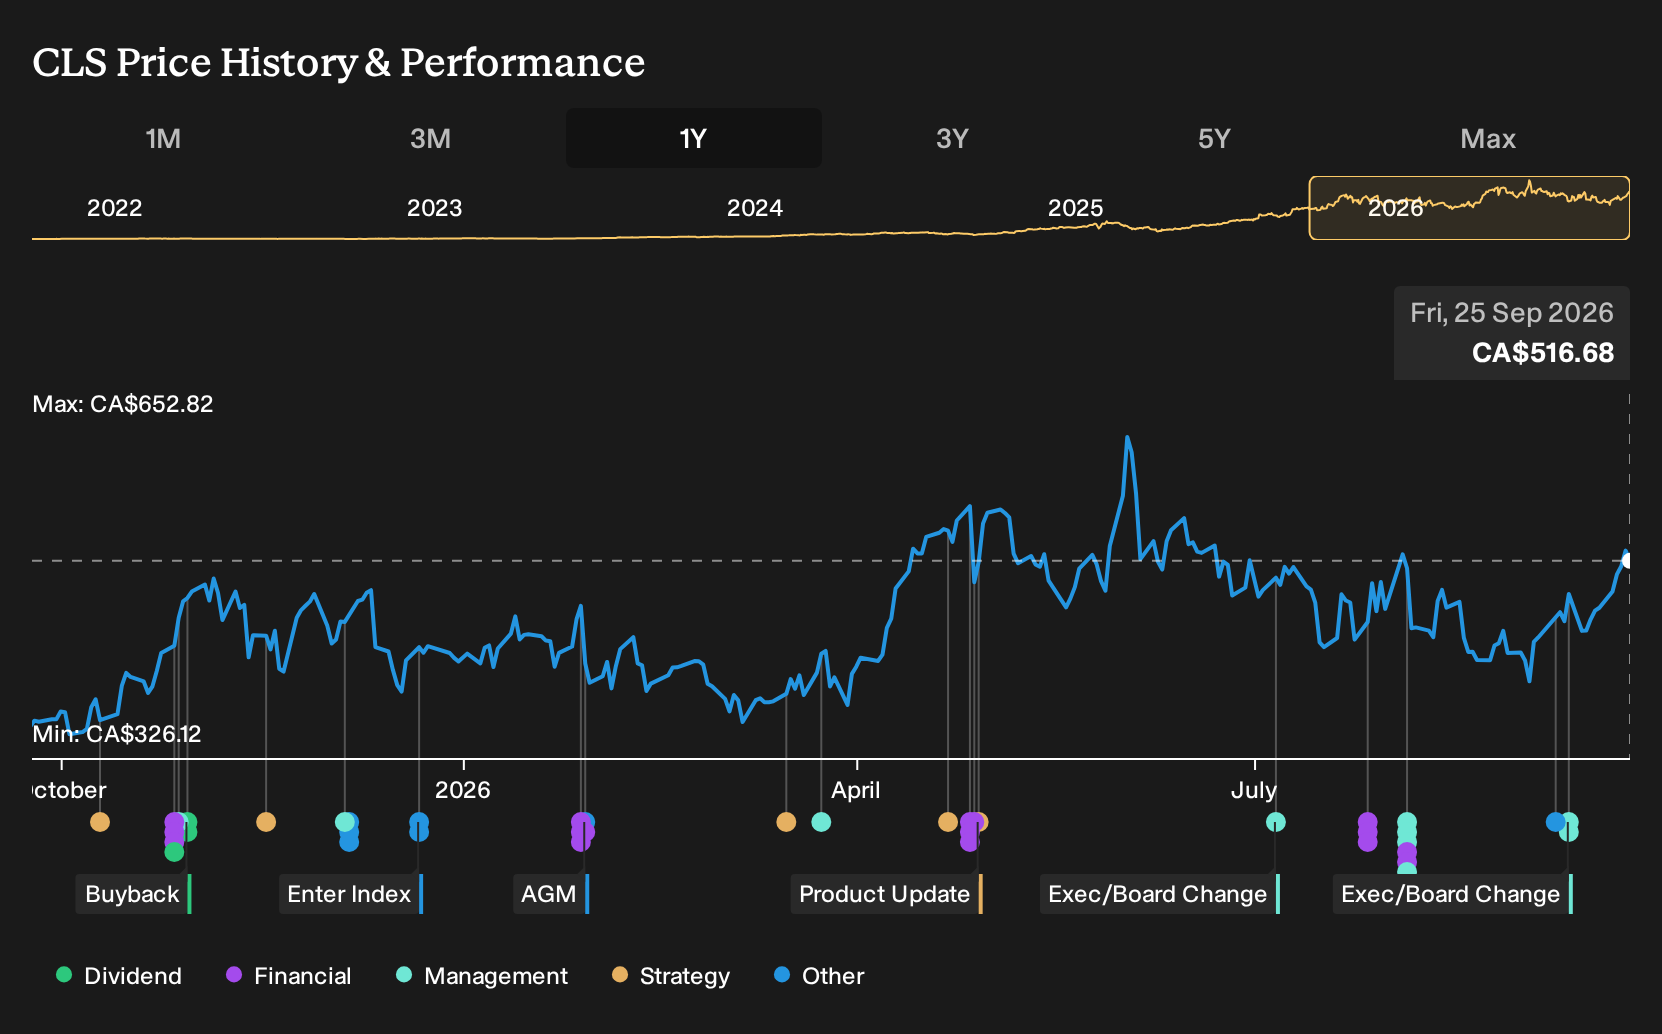
Celestica (TSX:CLS)
Overview: Celestica provides design, hardware platform, and end to end manufacturing services for hyperscalers, cloud providers, and other complex industries.
Operations: Celestica generates US$3.3b from Advanced Technology Solutions and US$12.3b from Connectivity & Cloud Solutions, anchored in large-scale manufacturing services.
Market Cap: CA$59.4b
Celestica matters for this solid balance sheet screener because its cloud and AI hardware platform work with hyperscalers links high return projects to disciplined manufacturing, which can translate design wins into resilient cash generation and support for a cleaner financial position.
"Accelerated demand for advanced networking and AI infrastructure by hyperscaler customers is driving rapid growth in Celestica's CCS segment, with multiple new 800G and upcoming 1.6T program ramps, supporting robust revenue expansion and greater operating leverage over the next 12 to 24 months."
The key question is how reliable those high intensity AI buildout orders remain if a single large customer changes pacing or shifts supplier mix.
If that customer risk is what you are weighing, read the full narrative for Celestica to see how Celestica’s AI buildout momentum could keep accelerating or quietly stall.
Seeking Alternatives Before The Crowd?
Fresh opportunities do not wait. Breakout stories gain momentum, weak ideas may lose value, and what is under the radar for now can change quickly. Consider conducting your research early.
- Spot potential breakout yield opportunities before they receive broader attention by scanning the curated 1 dividend fortresses.
- Explore early momentum in companies focused on building AI infrastructure and data capacity by reviewing the focused 85 AI infrastructure stocks.
- Track under the radar mining companies that could be affected if gold sentiment shifts by reviewing the hand picked 36 elite gold producer stocks.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com