
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Does Dividend Payout Change The Bull Case For American Tower Stock (AMT)?
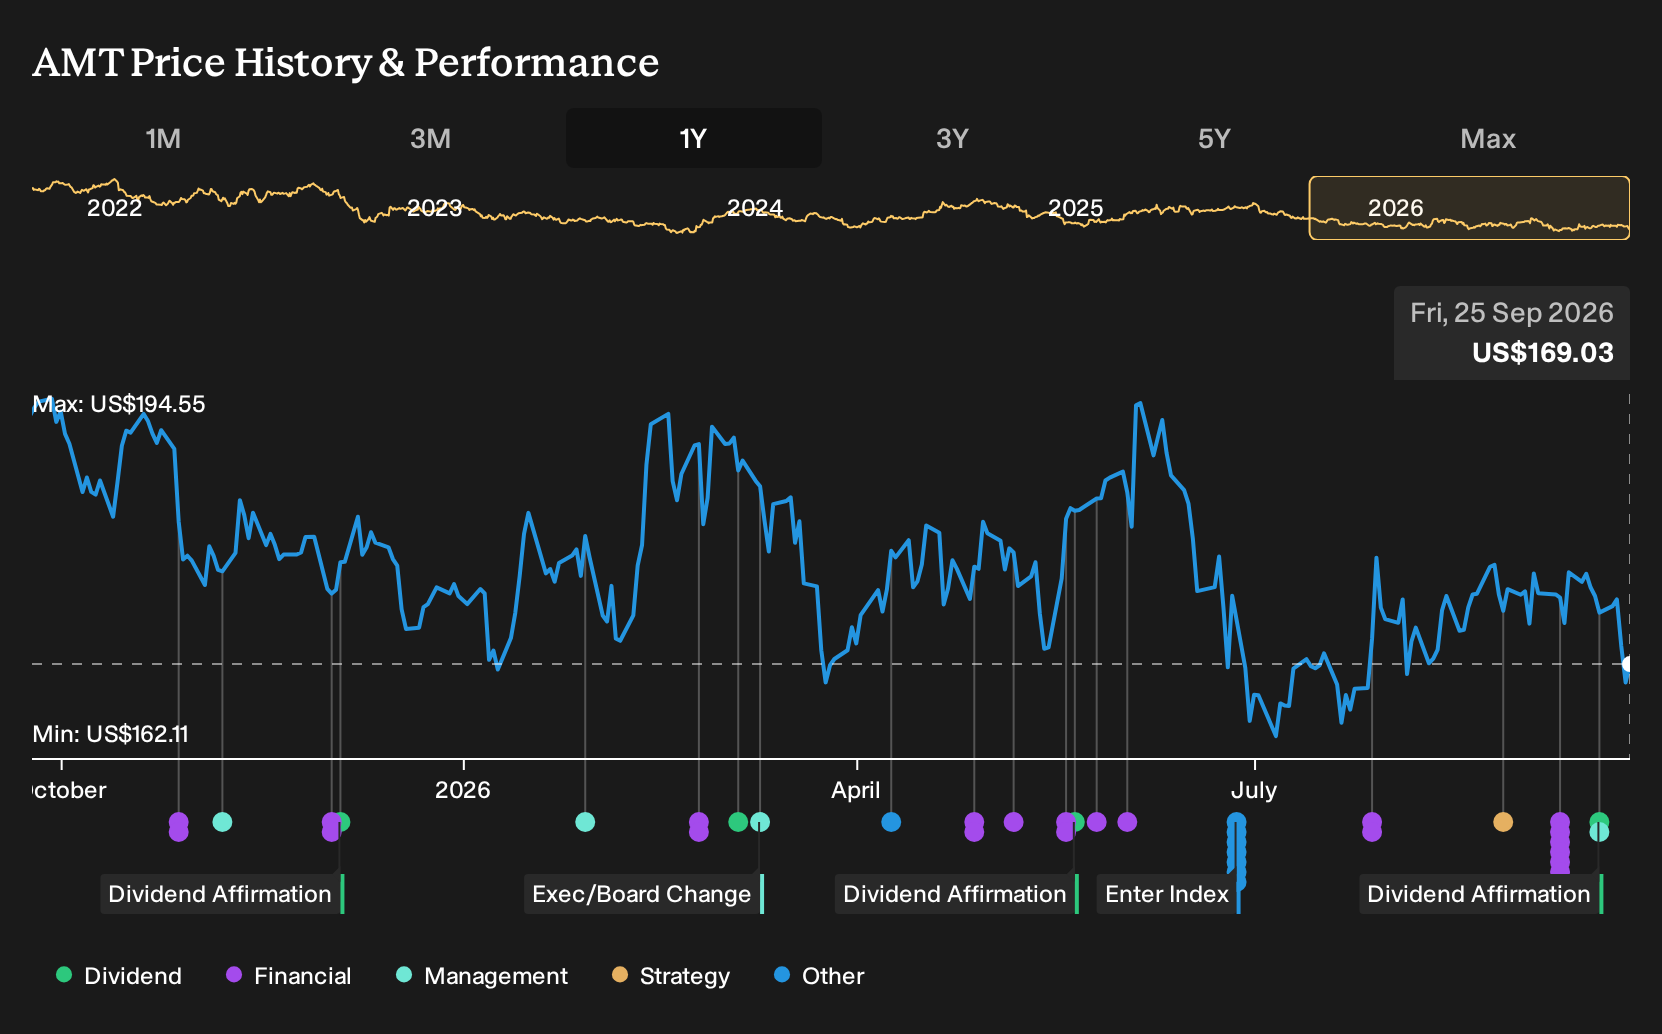
- American Tower declared a quarterly cash dividend of $1.79 per share, payable on October 20, 2026, to shareholders of record on September 30, 2026. In September 2026, the company also added Kristen M. Ludgate to its Board and to its Compensation and Human Capital Committee.
- The combination of a maintained cash payout and the appointment of a director with experience in human capital and governance reflects how American Tower is managing capital allocation and talent as it supports wireless and data center infrastructure demand.
- We will now look at how American Tower's affirmed dividend policy could influence the broader investment narrative for the business.
Scan other income-focused infrastructure plays that pair recurring payouts with boardroom experience by reviewing the hand picked list of 8 dividend fortresses before you move on.
American Tower Investment Narrative Recap
To own American Tower, you need to believe that carrier network upgrades, 5G densification and cloud infrastructure demand can keep tenant billings and data center leasing supported, even if they grow at a moderate pace. The affirmed US$1.79 quarterly dividend points to a focus on consistent cash returns rather than a near term reset in capital priorities.
The most immediate swing factor is how quickly carriers translate network plans into amendments and colocations, while data center leasing at CoreSite remains sensitive to AI and cloud demand. The biggest risk stays the same. Higher interest costs and debt that is not well covered by operating cash flow could constrain reinvestment if funding markets stay tight.
Among the recent announcements, Kristen M. Ludgate joining American Tower’s Board and Compensation and Human Capital Committee looks most relevant for execution on those catalysts. Her background across HR, legal, communications and enterprise transformation at HP and 3M aligns with the need to manage talent, governance and risk in a capital intensive REIT focused on connectivity and data centers.
For you as an investor, this board addition matters less as a headline and more as a tool for handling churn, refinancing pressure and capital allocation toward developed markets. Strong governance and human capital oversight can help the business balance dividend commitments, debt management and data center growth plans while it works through carrier consolidation and interest rate headwinds.
American Tower’s current analyst playbook points to revenues of US$12.5b and earnings of US$3.8b by 2029, based on 4.4% yearly revenue growth and an increase in earnings of about US$0.4b from US$3.4b today.
Uncover why American Tower's fair value indicates a 28% potential upside to its current price before that valuation gap closes.
Exploring Other Perspectives
The Simply Wall St Community currently delivers three fair value views for American Tower, ranging from roughly US$216 to US$293 per share. That spread shows how far private investors can disagree. When you factor in risks around carrier spending, data center leasing and interest costs, you have a strong reason to compare multiple viewpoints yourself.
Explore 2 other American Tower fair value estimates, including one that suggests it could be worth just $215.70!
Form Your Own Verdict
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your American Tower research is our analysis highlighting 6 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for American Tower. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate American Tower's overall financial health at a glance.
Looking For More Ideas Beyond American Tower?
Once you have a handle on American Tower, it can help to compare it with other income and quality focused opportunities using the Simply Wall St Screener.
- If you want payouts backed by strong financial profiles, scan a list of solid balance sheet and fundamentals (24 results) that might appeal to more cautious investors.
- For those hunting for potential mispricing, review a 32 high quality undervalued stocks that combine quality fundamentals with more appealing valuations.
- If you prefer steadier rides over sharp swings, sort through a 30 resilient stocks with low risk scores that may better match a capital preservation mindset.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com