
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Is Expected EPS Growth Altering The Investment Case For NRG Energy Stock?
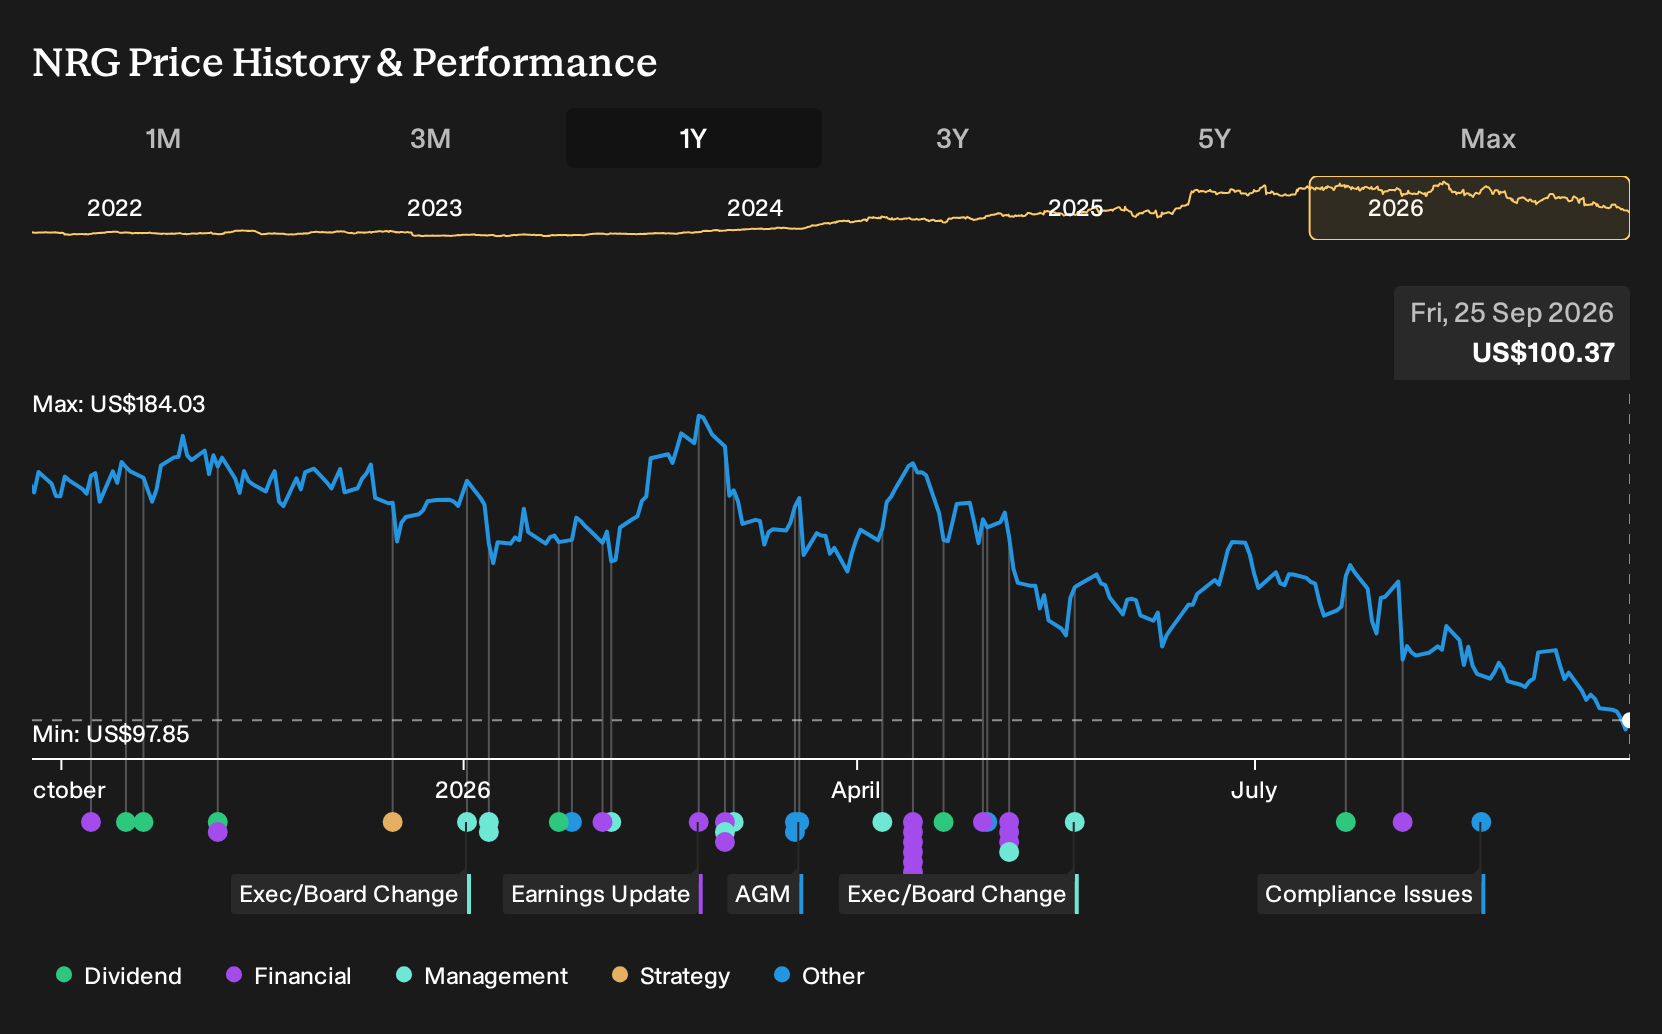
- NRG Energy has been in focus after recent earnings related news highlighted a sharp swing in sentiment around its profit outlook and the efficiency of its generation and retail operations, as investors reassessed how current earnings multiples line up with the underlying business.
- An additional angle is how NRG Energy’s exposure to data center power demand, electrification and long dated power delivery contracts is feeding into expectations for 26.55% EPS growth and raising questions about whether earnings quality justifies its sector premium.
- The discussion has now shifted toward how NRG Energy's investment narrative aligns with renewed attention on expected EPS growth driven by data center demand.
Compare NRG Energy's data center and electrification story with a hand picked list of power grid and infrastructure plays using the 40 power grid technology and infrastructure stocks to see who could benefit next.
NRG Energy Investment Narrative Recap
To own NRG Energy, you need to believe that data center power demand, electrification and long dated supply contracts can translate into durable earnings, not just a one quarter story. The recent share price swings around the expected 26.55% EPS growth have sharpened focus on how efficiently NRG runs its generation and retail operations in the near term.
The key short term catalyst is whether upcoming results confirm that higher load from data centers and contracted volumes are flowing through to high quality earnings and margins. The biggest risk is that heavy reliance on natural gas assets and higher debt costs squeeze net income, which would weaken that growth narrative.
The headline development is the renewed focus on NRG Energy’s expected EPS growth, tied to data center demand and electrification trends. That attention puts a spotlight on how well the current fleet, including the 13 GW of acquired gas generation and virtual power plant assets, is being dispatched and hedged against power price volatility.
This matters for catalysts because long term, premium margin power delivery agreements only create value if NRG consistently converts them into cash after interest, fuel and carbon related costs. Execution risk around integrating Vivint, expanding residential VPP offerings and managing higher interest obligations sits alongside that EPS story and shapes how reliable the growth path looks.
What The Current Forecasts Assume For NRG Energy
Analysts outline a fairly specific earnings arc for NRG Energy. The story links data center demand, electrification, and long-dated power deals to higher profit margins and a much larger earnings base by the end of the decade.
On the top line, the consensus work assumes revenue expands by 5.2% each year over the next three years. Profitability assumptions are even more aggressive, with margins projected to move from 2.4% today to 6.5% in roughly the same period. That margin expansion is doing a lot of the heavy lifting in the current EPS growth narrative that is associated with data center exposure.
On the earnings line, the analyst group expects NRG Energy to lift net income from US$782.0m today to US$2.5b by about 2029, with earnings per share of US$13.3. That implies a value increase of roughly US$1.7b in profit. The spread between the most bullish forecast at US$3.2b and the most cautious at US$2.1b shows how wide the debate still is around execution, fuel mix risk, and the durability of data center related demand.
These profit assumptions then flow into the implied valuation framework. To line up with the consensus view, investors would need to accept NRG Energy trading on a P/E of 24.1x those projected 2029 earnings, compared with 29.9x today and a current US Electric Utilities sector P/E of 20.3x. In other words, the thesis does not lean on multiple expansion. It relies instead on closing the gap between low current margins and the higher return profile analysts have outlined.
NRG has also been modeled with 7.0% annual growth in the share count over the next three years. That matters for anyone focused on per share outcomes rather than headline earnings, because issuing more equity or paying stock based compensation can dilute the impact of any future EPS growth connected to data center and electrification themes.
The discount rates used in these models sit in the 7.2% to 7.24% range. Those rates influence how much weight analysts give to profits expected several years from now compared with current cash generation, especially when capital is tied up in gas generation assets and home services integrations that still need to prove their return profile.
NRG Energy's narrative projects US$38.6b revenue and US$2.5b earnings by 2029. This assumes 5.2% yearly revenue growth and an earnings increase of roughly US$1.7b from US$782.0m today.
Uncover why NRG Energy's fair value indicates an 88% potential upside to its current price that could narrow quickly.
Exploring Other Perspectives
One alternate view focuses on Texas power price volatility rather than data center demand. In that story, bearish analysts saw only 2.7% yearly revenue growth and US$2.1b earnings by 2029, well below the US$2.5b consensus path. With the latest NRG Energy price swings, those pre news assumptions may shift meaningfully.
Explore 3 other NRG Energy fair value estimates, including one that suggests it could be worth just $188.56!
Reach Your Own Conclusion
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your NRG Energy research is our analysis highlighting 3 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for NRG Energy. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate NRG Energy's overall financial health at a glance.
Looking for more investment ideas beyond NRG Energy?
If the NRG Energy story has sharpened your focus on where future earnings might come from, you may wish to cast the net a little wider using the Simply Wall St Screener. You can filter for different types of opportunities, compare fundamentals side by side, and build a watchlist that fits your own risk and return preferences.
- For investors hunting for potential value opportunities with quality fundamentals, take a look at 32 high quality undervalued stocks that could be worth adding to your shortlist.
- If capital preservation and steadier profiles appeal more, you can focus on 30 resilient stocks with low risk scores that show more resilient characteristics on key risk metrics.
- Those looking for companies with strong financial footing can review the list of solid balance sheet and fundamentals (24 results) to find businesses with balance sheets that may better support their long term plans.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com