
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
US stock outlook | Futures of the three major stock indexes fell sharply, oil prices rose, technology stocks generally fell before the market, Meiguang's earnings report, PCE, and non-agricultural industries hit together this week
Pre-market market trends
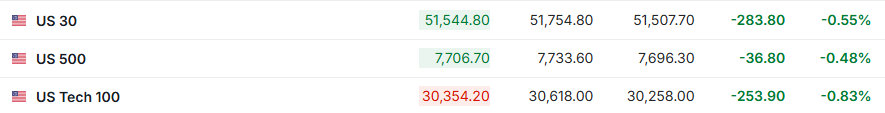
1. On September 28 (Monday), the futures of the three major US stock indexes fell sharply before the US stock market. As of press release, Dow futures were down 0.55%, S&P 500 futures were down 0.48%, and NASDAQ futures were down 0.83%.
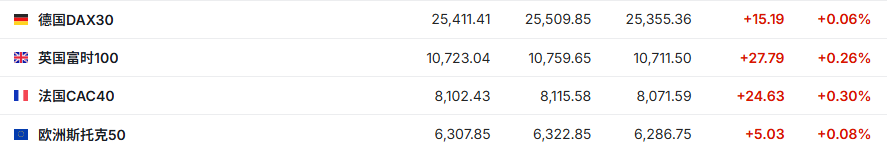
2. As of press release, the German DAX index rose 0.06%, the UK FTSE 100 index rose 0.26%, the French CAC40 index rose 0.30%, and the European Stoxx 50 index rose 0.08%.
3. As of press release, WTI crude oil rose 3.56% to $95.70 per barrel. Brent crude rose 3.16% to $100.52 per barrel.

Market news
Micron Technology's financial report tests that the AI infrastructure is complete. OpenAI and the White House AI talks resonate, and PCE fixed interest rates for October. This week, market focus will shift to earnings reports and macro data. After the US stock market on Wednesday EST, memory chip giant Micron Technology will announce its fourth fiscal quarter results. This is seen as a key point in testing whether AI infrastructure transactions can continue. In the past two weeks, transactions related to AI infrastructure have fluctuated, and memory chips have become one of the most prominent bottlenecks in the expansion of AI computing power. Investors will focus on finding evidence that demand for memory continues to be strong. OpenAI is expected to preview GPT-6 Cyber and launch managed smart-related products on DevDay in San Francisco on Tuesday; US President Trump, House Speaker Mike Johnson, and tech industry CEOs will meet to discuss AI on September 29, local time. Together, the three form a triple verification of AI transactions from model and supervision to profit. At the macro level, this week is a typical “employment and inflation week.” The Federal Reserve's preferred inflation indicator PCE will be released on Wednesday, and the September non-farm payrolls report will be released on Friday. The two will jointly determine the market's pricing for the Federal Reserve's October meeting and even the 2026 policy path. In addition, JOLTS job vacancies, ISM manufacturing index, Eurozone CPI, and RBA decisions will also distract market attention.
The prospects for US-Iran negotiations are uncertain. According to foreign media reports, US President Trump said on September 27 that he expects the US and Iran to resume negotiations within the next week. Trump also said that he “has been considering” whether to resume military attacks on Iran, while the US military is assisting in transporting “large amounts of oil” from the Strait of Hormuz. The media quoted regional sources as saying that it is expected that the US and Iran will hold a new round of indirect talks as early as the 28th. Qatar and other mediators are mediating, but there are huge differences between the US and Iran on key issues. Iran wants to focus negotiations on opening the Strait of Hormuz and lifting the US maritime blockade against Iraq, while the Trump administration demands that Iran agree to make concessions on the nuclear issue. However, Iranian media reported on the 28th that the Iranian delegation has no plans to hold talks with the US in New York. According to previous reports, Iran proposed that if the US lifts the maritime blockade, lifts oil sales sanctions, and resumes a regional cease-fire, Iran will reopen the Strait of Hormuz within seven days and restart nuclear negotiations. However, Trump confirmed to the media on September 26 that he had rejected Iran's proposal.
Goldman Sachs: US stocks are showing a “strong index, weak confidence” pattern, which may make up for the rise in the market and become the main line in the next phase. Goldman Sachs said that the US stock market is currently showing an unusual pattern — the index is showing strong performance, but investor confidence is weak, which means that the market still has the potential to rise further, and individual stocks left behind by leading AI stocks in the early stages are expected to make up for the rise. The S&P 500 index rose 14% this year, but Goldman Sachs's US stock sentiment index fell to -0.9, which is the same as the March low. Goldman Sachs strategist Ben Snyder and his team said in a September 25 report that this reading means there is still room for investors to increase their exposure to stocks if the macroeconomic environment improves. Meanwhile, Goldman Sachs's preferred market breadth index has fallen to its lowest level since the Internet bubble era. For investors, this differentiation could be significant if uncertainty about interest rates and economic growth subsides. Goldman Sachs believes that there is room for an overall rise in the market and a rebound in backward stocks, but the abnormally narrow market breadth may also cause momentum trading to continue to fluctuate.
J.P. Morgan is optimistic that US technology stocks will once again be favored by capital: positions cool down and valuations fall to free up space. The J.P. Morgan strategist team believes that as position congestion declines, profit performance is strong, and valuations become more realistic, technology stocks will regain some of the momentum lost since the end of the first half of the year, and investors are expected to re-enter the sector. The team, led by Mislav Matejka, wrote in a report released on Monday that gains have been suspended over the past three months, making the position structure cleaner, and stock prices are no longer expensive. Combined with rising capital expenses and continued strong profits, “it should support investors to re-participate in this sector.” Technology stocks are still leading the S&P 500 index by a large margin this year, but gains have cooled down in recent months, and the market is worried that huge investment in AI may not bring the returns that optimists assume. Matejka wrote, “We doubt there will be any significant slowdown in the end, as this is still a game about survival and winner-take-all.” J.P. Morgan said that although the increase in the first half of the year is unlikely to be repeated, opportunities still exist.
Retail investors left the market and institutions took over! Under the US debt storm, “smart money” continues to advance: $18.4 billion in options capital flows into US stocks, and AI is still the first choice. According to the latest data, institutional investors are taking over the dominance of the US stock market. After years of strong buying, retail traders seem to be gradually leaving the market. Meanwhile, data from Vanda Research shows that in the face of soaring US Treasury yields, large investors are still holding stocks steadily. Vanda global market strategist Viraj Patel wrote in a report to clients on Friday: “Institutional investors have shown surprising resilience in the face of increased macro volatility this week.” According to the data, the volume of option capital inflows from institutional investors (US$18.4 billion) is about three times the average in September of previous years. Patel said that although 10-year and 30-year US Treasury yields climbed to their highest level in more than a decade, the inflow of large capital has continued to rise over the past five trading days. He believes that under the broader safe-haven narrative, this is a “quite constructive signal” hidden in institutional investors' risk appetite. He mentioned that in the midst of market turbulence, institutional traders are choosing to place artificial intelligence (AI) related targets on merit.
Morgan Stanley: The US bond market is experiencing a “perfect storm.” Morgan Stanley pointed out that economic growth resilience, inflationary stickiness, energy market intervention risks, the Federal Reserve's transition to the Eagle, corporate debt issuance, fiscal deficits, and uncertainty about the Treasury's operations all drive up yields. Since March, the yield on 2-year, 5-year, and 10-year US Treasury bonds has increased cumulatively by about 120-150 basis points; after the Federal Reserve raised interest rates by 25 basis points in September, the market has taken into account additional contraction of close to 100 basis points. Morgan Stanley believes that the market may overestimate the final rate hike, but there is a lack of a fundamental catalyst to drive the expected shift in pigeons in the short term.
Individual stock news
US technology stocks generally fell before the market. Before the US stock market on Monday, as of press release, SK Hynix (SKHY.US) and SanDisk (SNDK.US) fell more than 3%, Intel (INTC.US) and Meta (META.US) fell nearly 3%, Western Digital (WDC.US), Oracle (ORCL.US), and AMD (AMD.US) fell more than 2%, and Micron (MU.US) and Seagate (STX.US) fell nearly 2%. In terms of optical communications stocks, Credo Technology (CRDO.US), Astera Labs (ALAB.US), Maywell Technology (MRVL.US), Corning (GLW.US), and Coherent (COHR.US) all fell more than 2%, while Nokia (NOK.US) and Lumentum (LITE.US) fell more than 1%.
Big buyback from Nvidia (NVDA.US)! Nvidia announced that it will increase the share repurchase authorization by 150 billion US dollars, bringing the total repurchase plan to 235 billion US dollars; the company expects to implement the repurchase plan by 2028 fiscal year. Nvidia CEO Hwang In-hoon said, “Nvidia's growth is due to an unprecedented platform transformation, a shift to artificial intelligence and accelerated computing. Our abundant cash flow allows us to invest in the technology driving this transformation and provide returns to our shareholders. This authorization shows our confidence in the long-term opportunities ahead.” As of press release, Nvidia's US stock rose nearly 1% before the market on Monday.
Starlink, moon landing, and space computing power all rely on it! SpaceX (SPCX.US) Starship 14 aims to enter orbit for the first time and deploy a new generation of satellites. SpaceX plans to launch its giant Starship rocket early on Monday local time in an attempt to launch the spacecraft into orbit for the first time. The US Federal Aviation Administration (FAA) confirmed via email that the agency issued the “SpaceX Starship Super Heavy Flight 14 Launch and Re-entry Operation License” on September 26. With Starship's 14th test flight, Elon Musk's aerospace and defense company also plans to deploy 26 new Starlink V3 satellites. Starships are the core carrier of SpaceX's expansion strategy. The company is counting on this giant rocket to expand the scale of its Starlink (connected business). As of the second quarter, Starlink was SpaceX's largest and only profitable sector.
The 1999 dollar folding screen iPhone is ready to be launched, yet Apple (AAPL.US) has been sued by more than 5.7 billion US dollars in patent claims. US consumer electronics giant Apple is facing a patent compensation ruling of more than 5.7 billion US dollars for tactile technology while increasing its folding screen iPhone and AI business. On September 25, a California federal jury found that Apple's Taptic Engine for some iPhones and Apple Watch infringes on two Taction Technology patents. Apple denied using each other's technology and made it clear that it would appeal. This is a jury ruling that may still be affected by subsequent judicial proceedings, and the market did not finally understand that Apple had paid compensation. For investors, the focus is on ultimate liability and its impact on cash flow, rather than directly judging a reversal in the competitiveness of Apple's core products.
Total (TTE.US) repurchases increased to 2.5 billion US dollars in the fourth quarter, promising an annual dividend increase of more than 5% by 2030. Total promised to increase dividends by more than 5% per year by 2030 and increase share buybacks. The French energy giant said in a statement on Monday that it will buy back 2.5 billion US dollars of shares in the fourth quarter of 2026 and buy back 2 billion to 2.5 billion US dollars in the first quarter of 2027. This is higher than the previously planned $1.5 billion buyback for the July-September quarter. The company expects its debt-to-debt ratio to be less than 10% by the end of this year. Although Total Energy and some of its peers have been forced to stop oil and gas production around the Persian Gulf since the outbreak of the US-Iran war at the end of February this year, they are benefiting from soaring crude oil and fuel prices in the Middle East and the Russia-Ukraine conflict.