
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Dear Marvell Stock Fans, Mark Your Calendars for Oct. 6
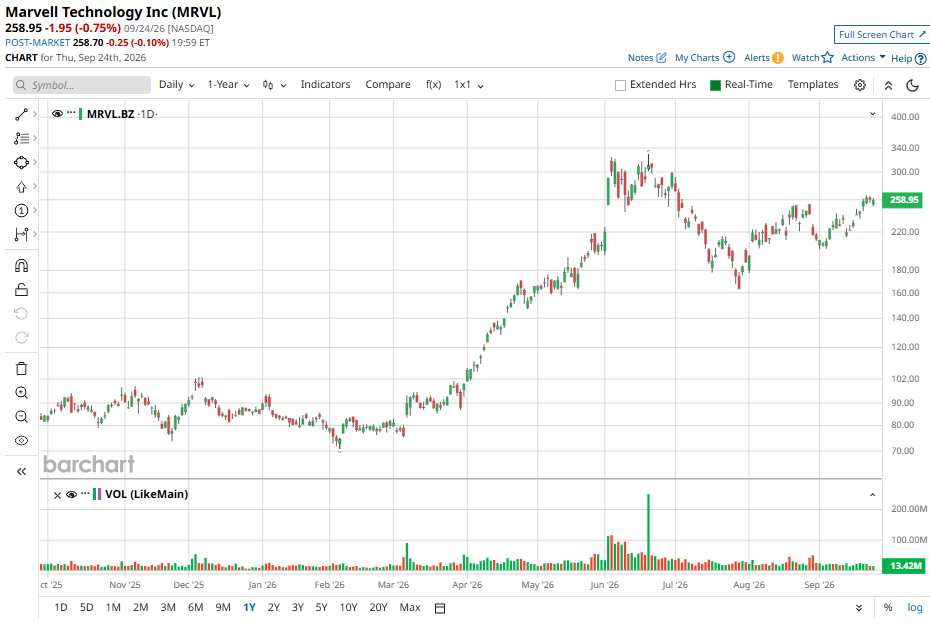
Marvell Technology (MRVL) has been one of the top artificial intelligence (AI) infrastructure plays in 2026. MRVL stock has gained over 204% year-to-date (YTD) as data center infrastructure continues to expand, driving demand for its interconnect products and custom chips.
The next catalyst could come on Oct. 6, when Marvell is scheduled to hold its Investor Day. The event could offer investors greater visibility into the company’s longer-term strategy, including its expectations for AI-driven demand, custom chip opportunities, and data-center infrastructure growth through the remainder of the decade.
Marvell Raises Its Fiscal 2027 and 2028 Growth Expectations
Marvell Technology’s latest quarterly results suggest that its growth trajectory is strengthening. The semiconductor company’s decision to raise its fiscal 2027 and 2028 revenue outlook reflects accelerating demand for AI infrastructure and improving prospects across the AI ecosystem.
For the second quarter of fiscal 2027, Marvell reported $2.74 billion in revenue, up 13% sequentially and 37% year over year (YOY). Adjusted EPS rose 40% YOY to $0.94. More importantly, management raised its fiscal 2027 revenue forecast to about $12 billion, implying about 45% annual growth, up from its earlier expectation of roughly $11.5 billion.
Marvell’s data center business is the primary growth driver, generating $2.17 billion in revenue in Q2, up 18% sequentially and 46% YOY. Looking ahead, Marvell now expects its data center business to grow approximately 60% in fiscal 2027, up from its previous forecast of 50%. The outlook also points to accelerating momentum in the second half of the year, with Q3 revenue expected to increase 20% sequentially and approximately 75% YOY.
The upward revision is being supported by increasing AI-related capital spending among hyperscalers. Marvell is positioned across several critical areas of AI infrastructure, including high-speed optical interconnects, networking and switching, and custom silicon.
Interconnect will play a significant role in driving its growth. Strong demand for 800G optical products and increasing adoption of 1.6T solutions, which could become increasingly significant in fiscal 2028, will support its revenue. In scale-out switching, Marvell’s business remains on track to more than double this year, driven by the strong ramp of its 51.2T products across an expanding customer base.
Custom semiconductors represent another significant growth opportunity. The business is expected to ramp substantially during the second half of fiscal 2027, more than double in fiscal 2028, and continue expanding in fiscal 2029.
The fiscal 2028 outlook indicates solid medium-term growth. Marvell expects $18 billion in revenue, $1.5 billion above its earlier forecast. This implies 50% YOY growth. Custom semiconductor revenue is expected to more than double in fiscal 2028, with significant acceleration anticipated in fiscal 2029.
Overall, Marvell’s opportunity appears to be broadening. Moreover, its expanding relationship with Alphabet’s (GOOG) (GOOGL) Google could materially increase the company’s custom-silicon opportunity, with some of that incremental revenue potentially beginning in fiscal 2029.
The Key Takeaway
Marvell’s revenue trajectory for fiscal 2027 and 2028 remains solid. Demand for high-speed optical connectivity and networking switches, along with the expansion of its custom silicon business, provides multiple avenues for sustained revenue growth as AI data center investment continues to accelerate.
The key issue, however, is valuation. After a substantial appreciation in Marvell’s share price, the stock appears to be pricing in much of its expected growth. Its forward P/E multiple of 85.9 remains elevated.
Against this backdrop, the Oct. 6 Investor Day could serve as an important catalyst. Investors are likely to focus on management’s longer-term revenue targets, visibility into customer commitments, and evidence that AI-related demand can remain durable. Additional clarity around interconnect business and custom silicon operations could strengthen the market’s confidence in Marvell’s long-term earnings outlook.
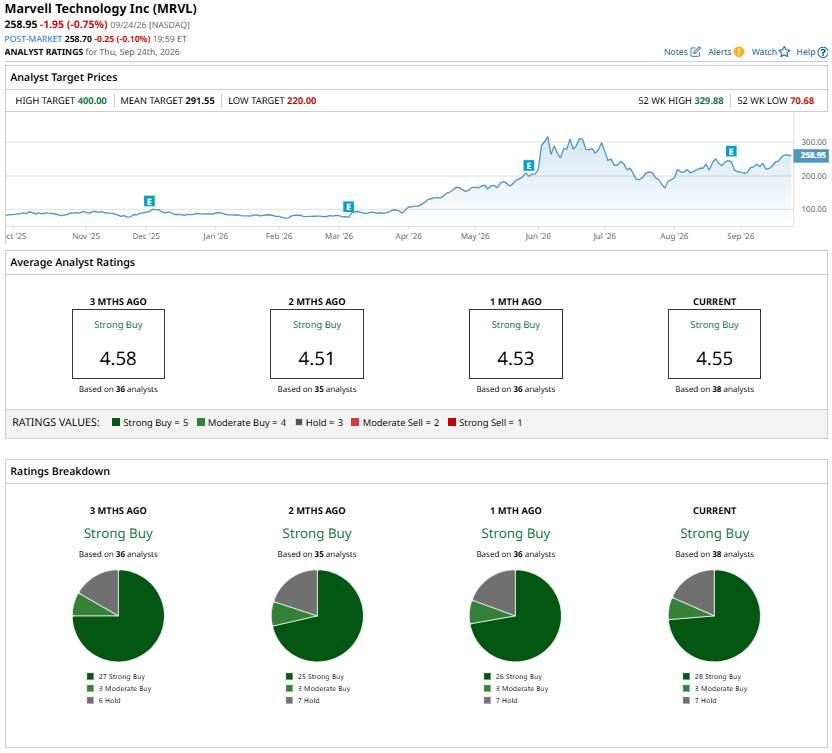
Analyst sentiment remains positive, with MRVL stock carrying a “Strong Buy” consensus rating.
On the date of publication, Amit Singh did not have (either directly or indirectly) positions in any of the securities mentioned in this article. All information and data in this article is solely for informational purposes. For more information please view the Barchart Disclosure Policy here.