
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
A.G. BARR And 2 British Undervalued Stocks To Watch
Bond yields are climbing as oil trades above $108 a barrel, pushing up borrowing costs and putting pressure on richly priced stocks. Cash rich British businesses that generate steady inflows but trade below what discounted cash flow models suggest can look interesting in that setting. This article highlights three such UK opportunities from a value screen built around cash generation and pricing, so you can judge whether any belong on your watchlist.
The three ideas below are only a sample from this cash flow value theme. The full screen surfaces 11 more UK businesses with similarly interesting cash profiles and pricing that are not covered here. To go straight to the source, analyze, compare, and identify your own highest conviction setups using the Undervalued Stocks Based On Cash Flows screener.
A.G. BARR (LSE:BAG)
A.G. BARR is a £659.2 million drinks group that manufactures, distributes, and sells branded soft drinks and cocktail mixes. Its Soft Drinks arm, which produced about £382 million of the £437.3 million segment total, is the key cash engine behind its undervalued cash flow profile.
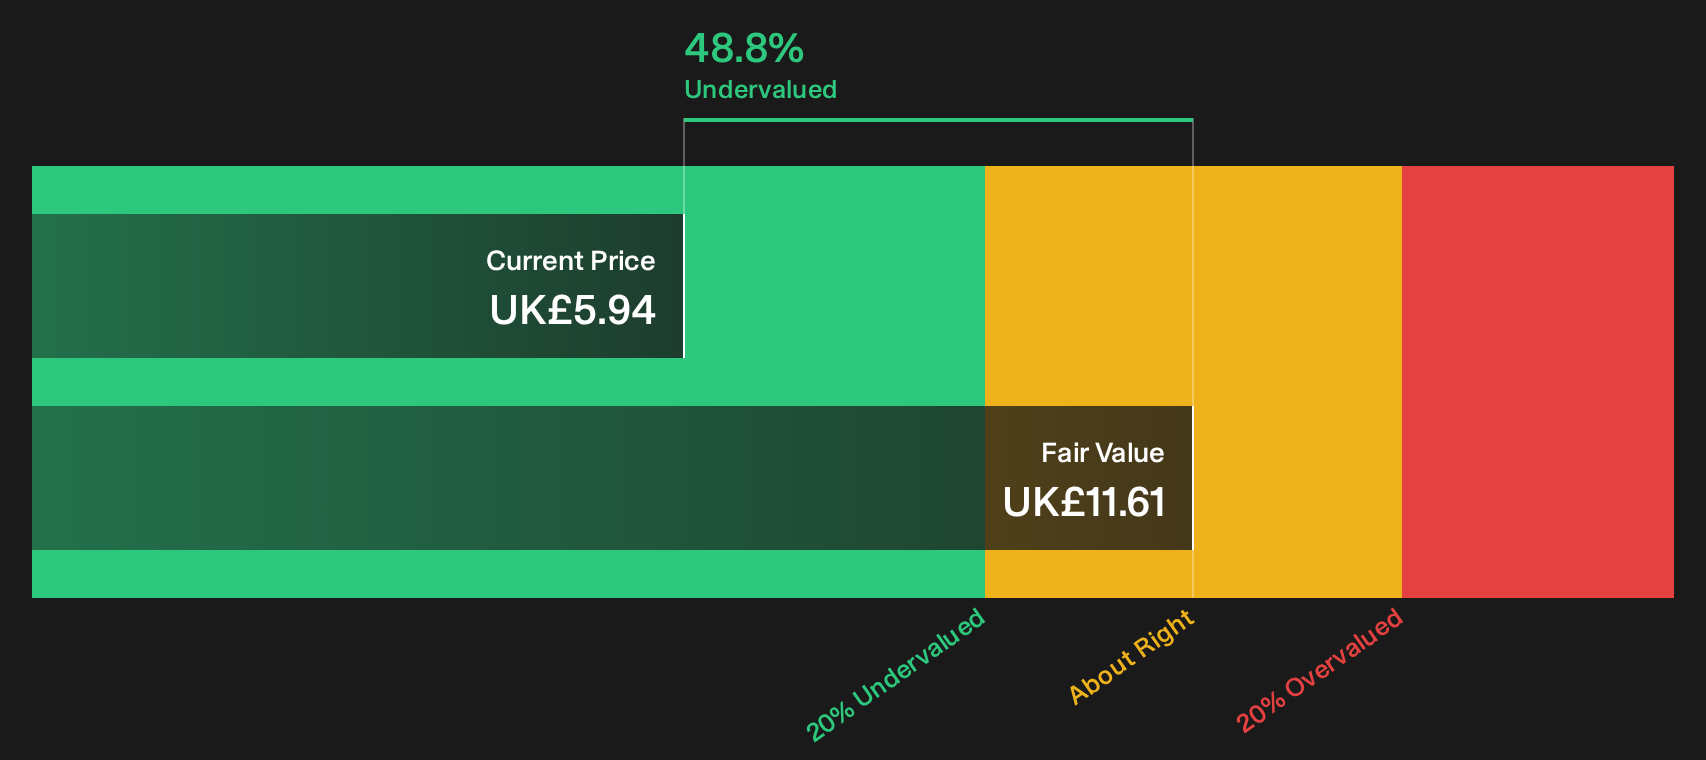
A.G. BARR trades at a P/E of 14x versus a European beverage sector on 17x, while SWS DCF analysis flags the shares at roughly a 48.8% discount to estimated fair value. That discount is anchored in steady cash from IRN-BRU and other brands, yet could hinge on how one unseen funding pressure evolves.
That hidden funding question is exactly what you want to stress test with the 5 key rewards and 1 important warning sign while you gauge whether A.G. BARR's cash engine is being mispriced.
LSL Property Services (LSE:LSL)
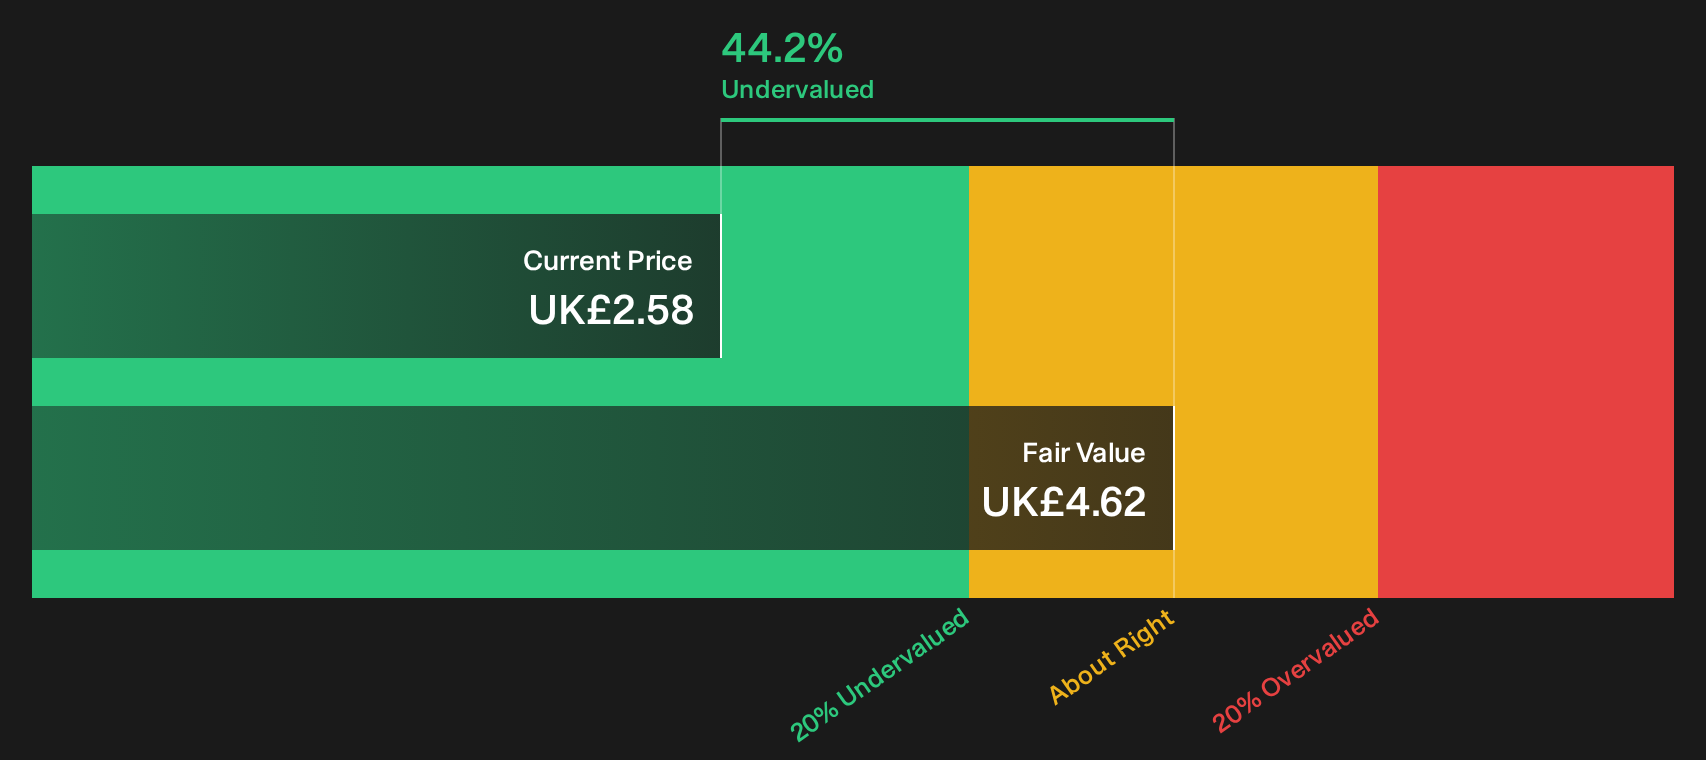
LSL Property Services is a £253.7 million, capital light property services group in the UK. Its cash-flow theme is most visible in the Surveying & Valuation arm, which produces £110.7 million of surveyor-led fees, alongside £48.2 million from Financial Services and £26.7 million from franchised estate agency.
LSL Property Services gives this cash-flow screen a different flavour, since much of its income comes from repeat survey and valuation work that is closely tied to mortgage activity rather than pure house price moves.
"Rising mortgage refinancing activity, with large volumes of two year and five year products maturing, should sustain higher new lending flows through LSL’s adviser network and underpin continued growth in Financial Services revenue and earnings."
The real swing factor for LSL Property Services is how one cost and funding pressure shapes the payoff from that recurring fee engine.
That funding pressure is exactly what the full narrative for LSL Property Services unpacks, showing how LSL Property Services could turn accelerating refinancing flows into a more resilient fee engine.
Foresight Group Holdings (LSE:FSG)
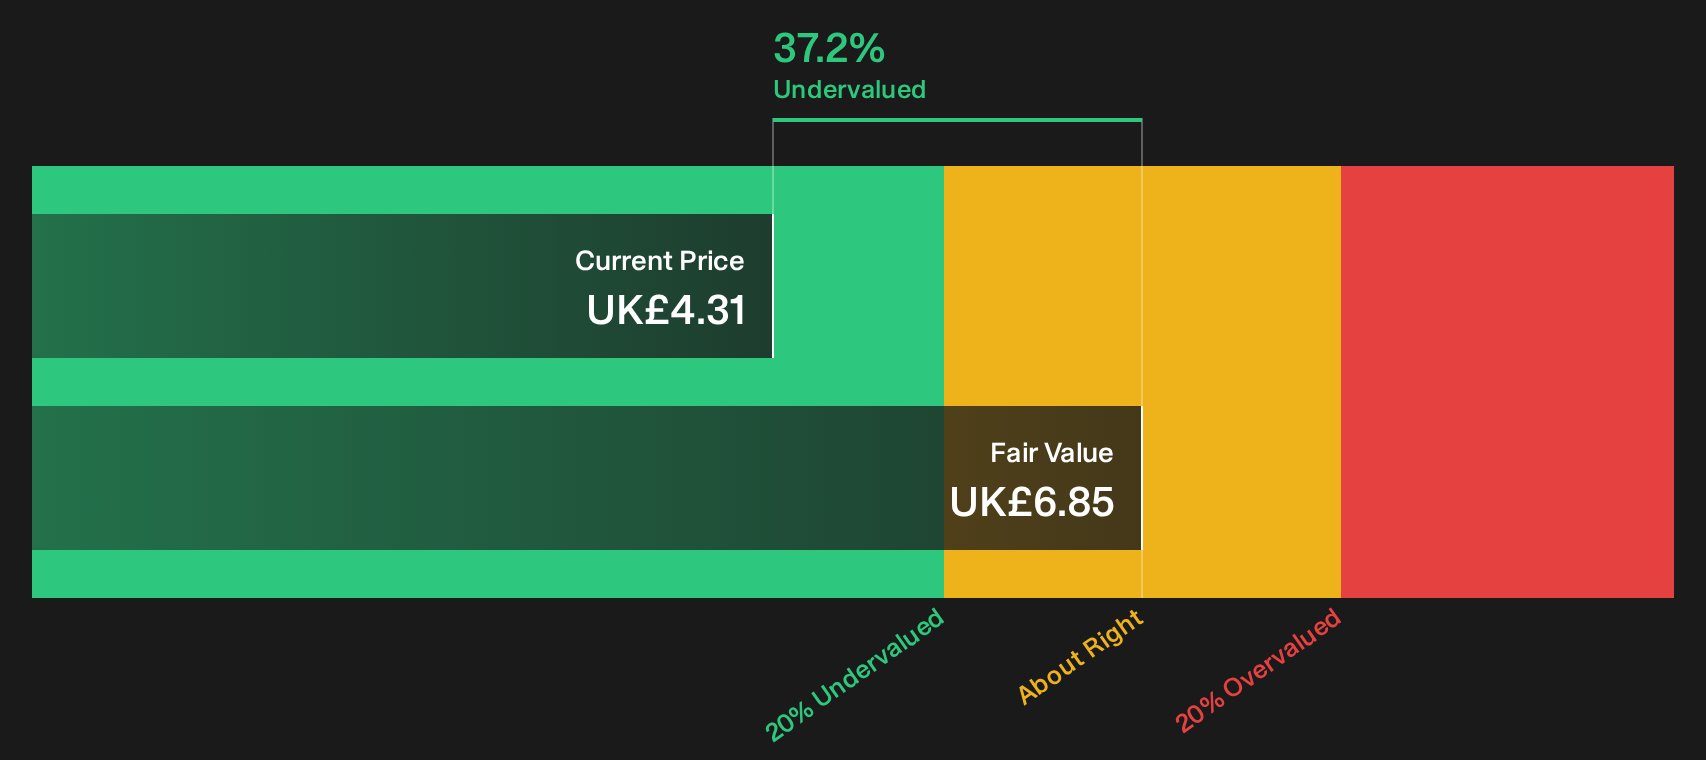
Foresight Group Holdings is an infrastructure and private equity manager where the Real Assets division, tied to renewables-focused infrastructure funds, generates £114.8 million of the £164.9 million total, with Private Equity at £50.1 million and a market value of about £476 million.
Foresight Group Holdings taps into the cash flow theme through its renewables infrastructure platform, where long-term contracts and asset-backed income streams feed into a broader investment engine that is now being reshaped by how management recycles capital and sizes new opportunities.
"The combination of public-to-private acquisitions (such as Harmony Energy Income Trust), performance-driven fund launches, and ongoing buybacks (where buybacks are outpacing share-based dilution) is described as a driver of compounding EPS growth and potentially higher dividend per share increases, as capital is recycled into accretive, high-ROIC strategies and the return of capital accelerates."
The real question for investors is how one emerging pressure on future fee income shapes the payoff from that cash rich renewables platform.
That pressure point is exactly what the full narrative for Foresight Group Holdings lays out, showing how accelerating capital recycling could reshape fee durability and dividend firepower.
Seeking Alternatives Before The Crowd Moves
Fresh ideas move first. Slow research gets caught chasing momentum once prices are already flying. Scan under the radar for now, while it matters, and get in early.
- Target reliable income streams by reviewing the 1 dividend fortresses and see which high yield opportunities still trade at levels that reward patient capital.
- Hunt for resilient quality by checking the list of solid balance sheet and fundamentals (10 results) so you can focus on businesses where strong finances back up the story.
- Track the next wave of infrastructure demand by scanning the 40 power grid technology and infrastructure stocks before more investors notice where the capital is quietly shifting.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com