
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Agilysys (AGYS) On Casino Resort Expansion And The Undervalued Narrative
Agilysys (AGYS) drew fresh attention on 22 September 2026 after Angel of the Winds casino resort expanded its use of the firm’s hospitality platform across property management, online booking and food and beverage point-of-sale systems.
Set against that customer win, Agilysys’ recent share price performance has cooled, with the stock down about 15% over the past 30 days and lower year to date, even though the 3-year total shareholder return of roughly 51% and 5-year total shareholder return of about 86% still reflect a much stronger, longer-run journey.
Spot other hospitality and software specialists that may be building similar momentum to Agilysys with our handpicked 16 high quality undiscovered gems.The question now is whether Agilysys’ recent pullback reflects a reassessment of its business progress or a swing in sentiment, and how that backdrop compares with where the valuation sits today.
Most Popular Narrative: 25% Undervalued
Agilysys is currently trading at $99.64. The most followed narrative anchors on a fair value estimate of $133.67 that uses an 8.55% discount rate and explicitly ties that gap to a mix of subscription growth, margin assumptions and execution risks.
Rapid adoption of cloud-native, subscription-based hospitality software and the company's shift toward a SaaS revenue model is creating significantly higher and more predictable recurring revenue streams, positioning Agilysys for ongoing improvements in earnings and margin expansion as legacy perpetual license sales decline.
See why 7 investors see Agilysys as 25% undervalued.
Result: Fair Value of $133.67 (UNDERVALUED)
Still, the Agilysys narrative leans heavily on hospitality spending and ambitious point of sale targets, so any slowdown in bookings or tougher competitive wins could quickly challenge those assumptions.
Find out about the key risks to this Agilysys narrative.
Another View: Agilysys Through A P/E Lens
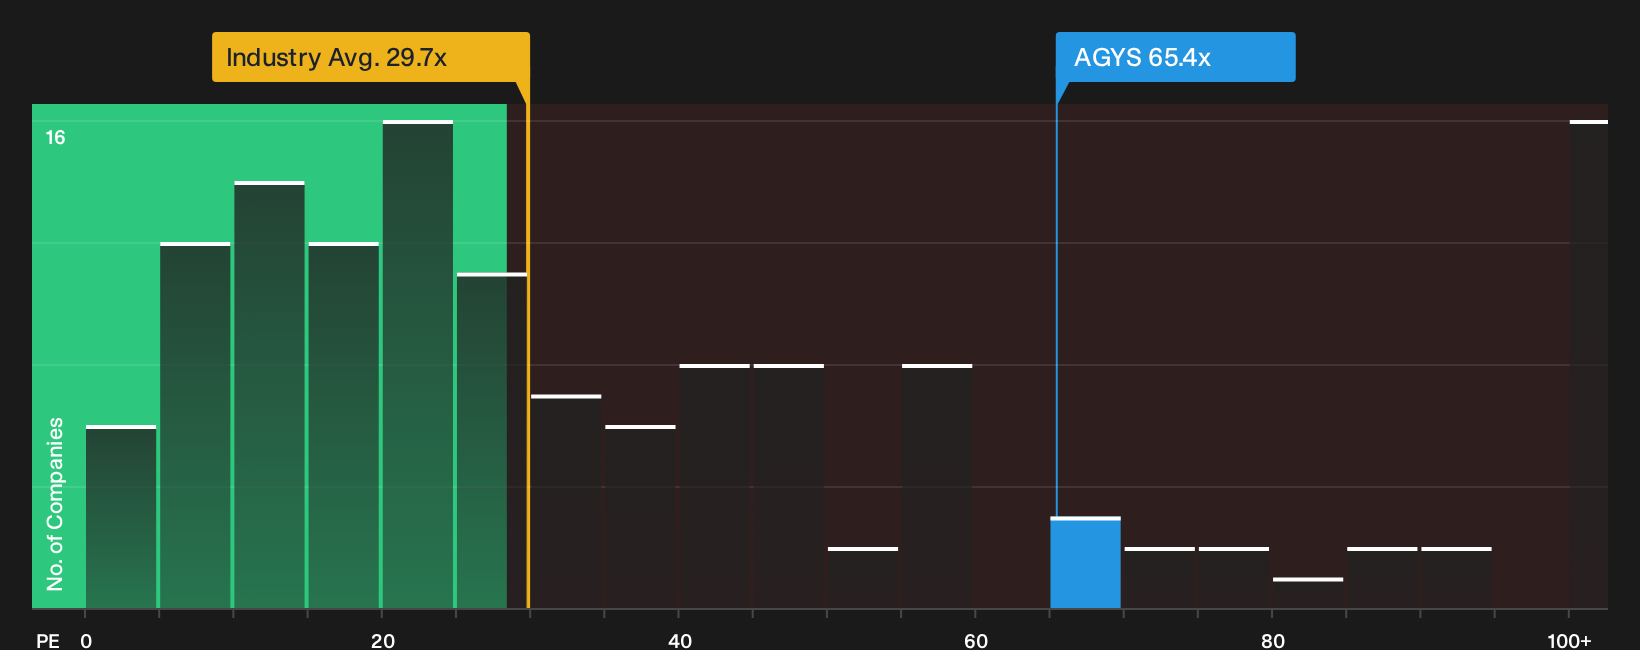
Agilysys might look appealing against a fair value estimate of $133.67, yet the current P/E of 65.4x tells a very different story. That multiple sits well above the US Software sector on 29.7x and the peer group at 41.9x, and it is almost double the 34x fair ratio.
Such a gap suggests that a lot of optimism is already baked into the price. This raises the question of how much room is left if growth or margins track closer to average rather than the more optimistic scenarios anchoring the bullish narrative.
See what the numbers say about this price in more detail with our valuation breakdown. Then decide which signals you trust most, the cash flow story or the earnings multiple story, by reviewing the See what the numbers say about this price — find out in our valuation breakdown..
Next Steps
Mixed signals on Agilysys so far. If you want to move quickly but think for yourself, weigh both sides of the story by checking the 4 key rewards and 1 important warning sign.
Ready for more ideas beyond Agilysys?
If Agilysys has sharpened your thinking, do not stop here. Broaden your watchlist with a few focused screens that surface very different types of opportunities.
- Target resilient compounding potential by scanning a curated set of quality companies trading below estimated value through the 32 high quality undervalued stocks.
- Prioritise staying power in tougher markets by zeroing in on businesses with strong finances using the list of solid balance sheet and fundamentals (24 results).
- Hunt for tomorrow's potential standouts before the crowd pays attention by reviewing the 16 high quality undiscovered gems.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com