
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Exploring 3 Undervalued Small Caps In Global With Recent Insider Activity
In recent weeks, global markets have been navigating a complex landscape marked by inflation concerns and fluctuating interest rates, with the small-cap Russell 2000 Index experiencing a pullback amid these pressures. Despite these challenges, economic indicators like the U.S. PMI suggest robust business activity, creating an environment where discerning investors might find opportunities in undervalued small-cap stocks exhibiting insider activity. Identifying such stocks often involves looking for those with strong fundamentals and potential for growth despite broader market volatility.
Top 10 Undervalued Small Caps With Insider Buying Globally
| Name | PE | PS | Discount to Fair Value | Value Rating |
|---|---|---|---|---|
| Q Technology (Group) | 3.6x | 0.2x | 42.71% | ★★★★★☆ |
| China Aircraft Leasing Group Holdings | 7.3x | 1.0x | 36.09% | ★★★★★☆ |
| Nexus Industrial REIT | 10.1x | 3.0x | 8.59% | ★★★★☆☆ |
| Pizza Pizza Royalty | 11.8x | 9.0x | 41.68% | ★★★★☆☆ |
| Linc | 12.1x | 12.6x | 34.06% | ★★★★☆☆ |
| Sagicor Financial | 6.9x | 0.5x | -77.78% | ★★★★☆☆ |
| Diversified Royalty | 25.6x | 10.1x | 45.99% | ★★★☆☆☆ |
| Travis Perkins | NA | 0.3x | -218.07% | ★★★☆☆☆ |
| ATS | 55.5x | 0.9x | 31.43% | ★★★☆☆☆ |
| Coveo Solutions | NA | 1.8x | -20.42% | ★★★☆☆☆ |
Here we highlight a subset of our preferred stocks from the screener.
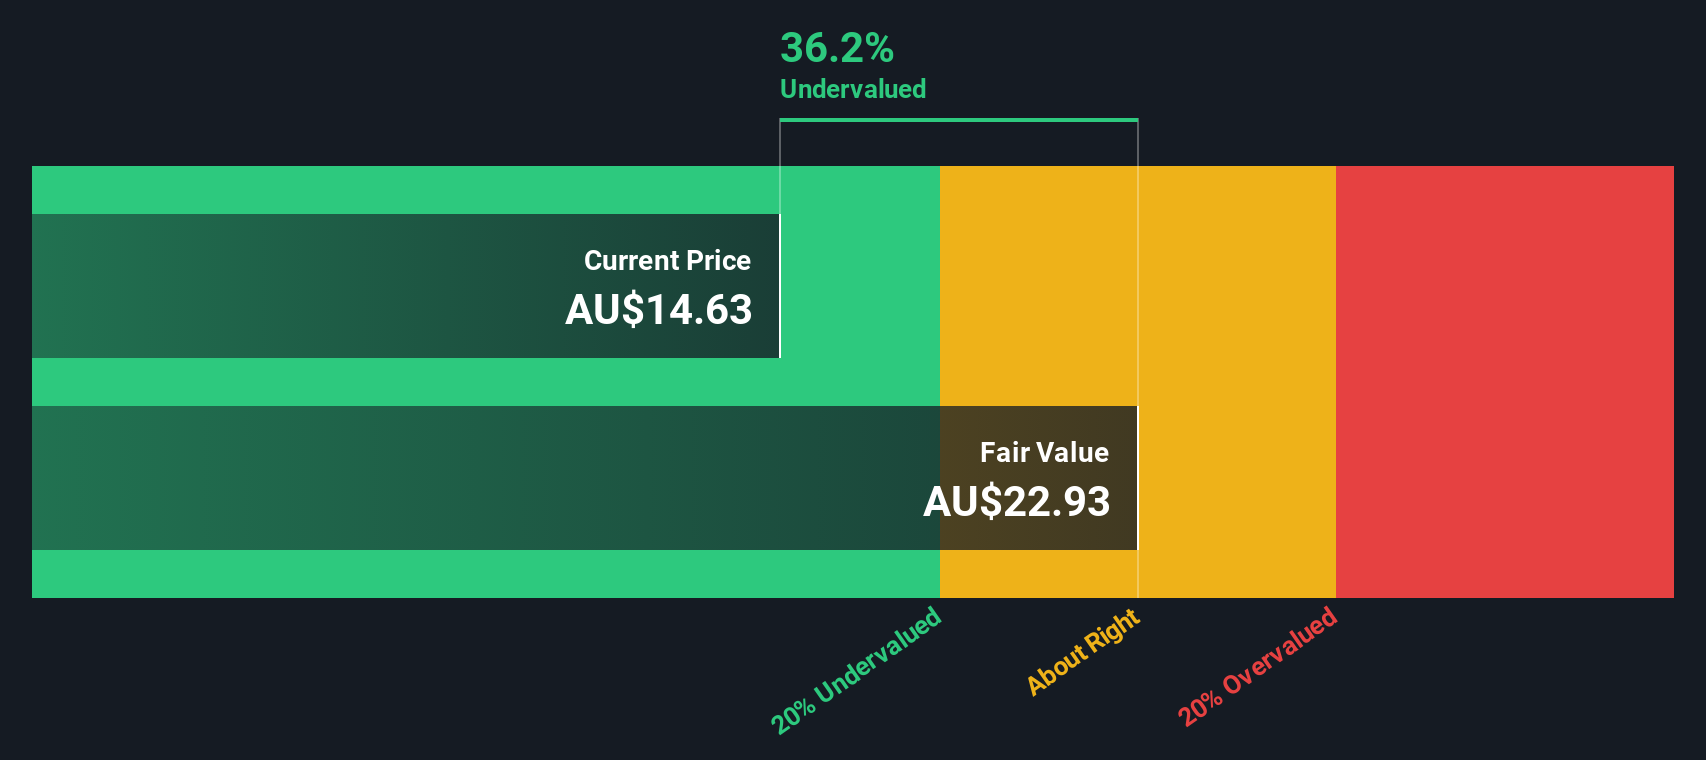
Domino's Pizza Enterprises (ASX:DMP)
Simply Wall St Value Rating: ★★★★☆☆
Overview: Domino's Pizza Enterprises is a leading pizza delivery and carryout company operating a network of restaurants, with a market cap of A$5.86 billion.
Operations: Revenue primarily comes from restaurant operations, with a focus on managing costs of goods sold (COGS) and operating expenses. The gross profit margin has fluctuated over time, reaching 31.88% in the most recent period. Operating expenses include significant allocations for sales and marketing as well as depreciation and amortization. Net income margins have shown variability, recently recording negative figures due to increased non-operating expenses.
PE: -13.8x
Domino's Pizza Enterprises, recently dropped from the FTSE All-World Index, presents a mixed picture as an undervalued stock. Despite reporting a net loss of A$134.16 million for the year ending June 2026, insider confidence remains evident with recent share purchases. The company is navigating legal challenges related to historical agreements but maintains a forecasted earnings growth of 43% annually. While high debt levels are notable, strategic management and industry positioning could offer future potential for investors seeking small-cap opportunities in dynamic markets.
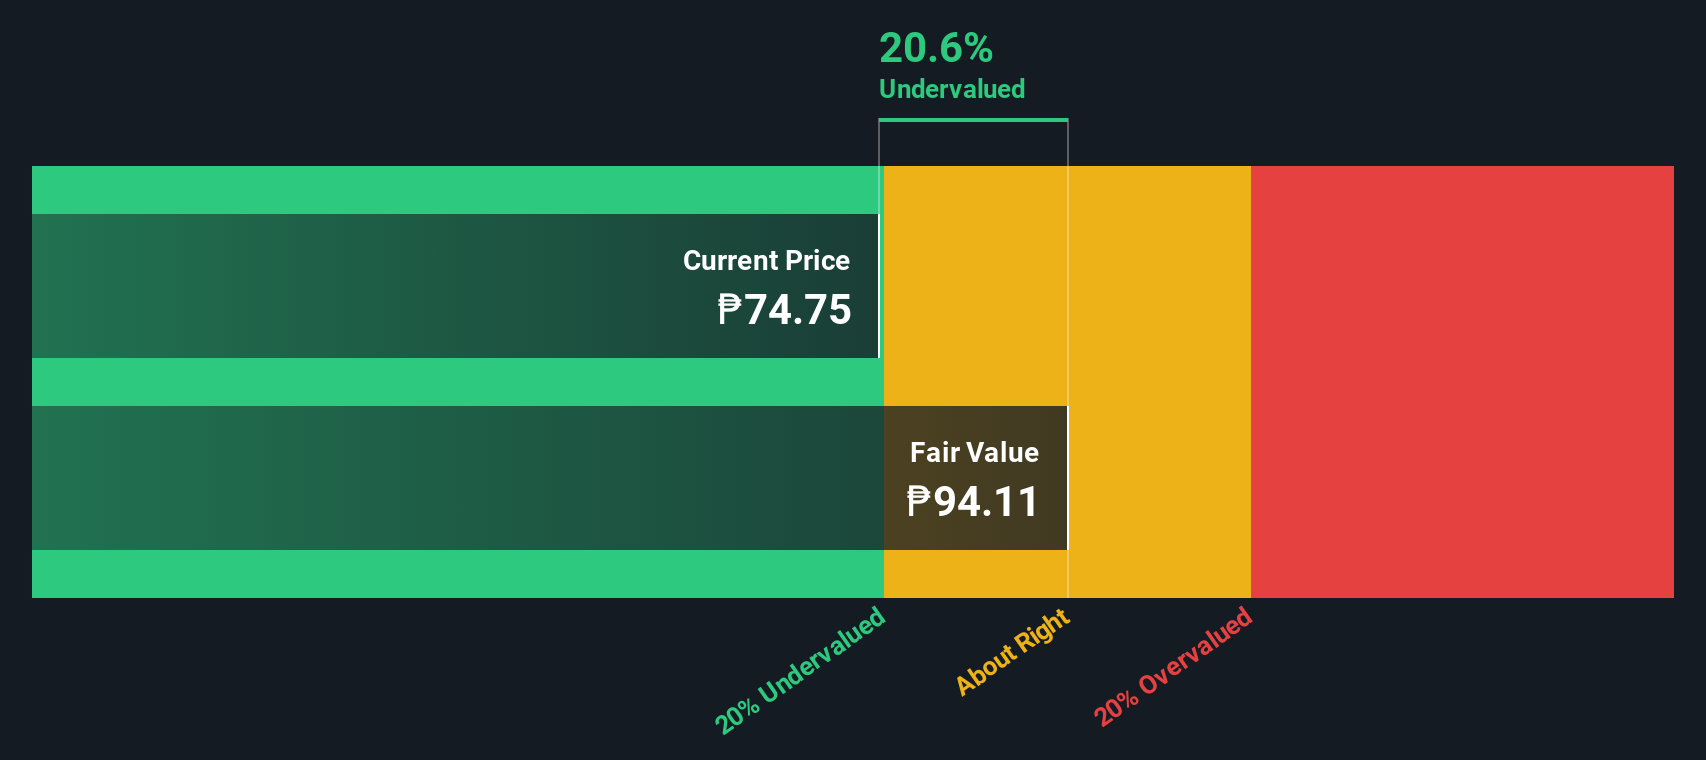
Asia United Bank (PSE:AUB)
Simply Wall St Value Rating: ★★★☆☆☆
Overview: Asia United Bank is a financial institution that provides a range of banking services including commercial and consumer banking, treasury operations, and branch services, with a market capitalization of ₱39.22 billion.
Operations: Asia United Bank's primary revenue streams include branches, treasury operations, consumer banking, and commercial banking. The company has shown a notable trend in its net income margin, reaching 56.02% by March 2025 from 24.61% in September 2015. Operating expenses are primarily driven by general and administrative costs alongside sales and marketing expenses.
PE: 5.5x
Asia United Bank, a smaller player in the banking sector, is showing signs of potential value. Recent insider confidence is evident as Acmad Rizaldy Moti acquired 11,000 shares valued at PHP 454,453 in July 2026. The bank's earnings for Q2 2026 showed a slight increase in net income to PHP 2.99 billion from PHP 2.98 billion the previous year. A significant amendment to its Articles of Incorporation was approved on August 28, raising authorized capital stock from PHP 14.7 billion to PHP 72.5 billion to support expansion plans and strategic growth initiatives moving forward.
- Navigate through the intricacies of Asia United Bank with our comprehensive valuation report here.
Assess Asia United Bank's past performance with our detailed historical performance reports.
Marco Polo Marine (SGX:5LY)
Simply Wall St Value Rating: ★★★★★★
Overview: Marco Polo Marine is a Singapore-based company specializing in ship chartering, shipbuilding, and repair services with a market capitalization of approximately SGD 0.33 billion.
Operations: The company generates revenue primarily from ship chartering services and ship building and repair services, with recent figures showing SGD 92.56 million and SGD 51.57 million respectively in these segments. The gross profit margin has shown a notable upward trend, reaching 44.38% by March 2026, indicating improved cost management or pricing strategies over time.
PE: 8.6x
Marco Polo Marine, a small company in the marine sector, has caught attention with its insider confidence. CEO & Executive Director Yun Lee purchased 400,000 shares recently for A$56,000. This move indicates belief in the company's potential despite challenges like a forecasted earnings decline of 3.4% annually over three years. While revenue is expected to grow by nearly 20% per year, reliance on external borrowing adds risk to its financial structure.
- Unlock comprehensive insights into our analysis of Marco Polo Marine stock in this valuation report.

Taking Advantage
- Unlock more gems! Our Undervalued Global Small Caps With Insider Buying screener has unearthed 117 more companies for you to explore.Click here to unveil our expertly curated list of 120 Undervalued Global Small Caps With Insider Buying.
- Already own these companies? Link your portfolio to Simply Wall St and get alerts on any new warning signs to your stocks.
- Simply Wall St is a revolutionary app designed for long-term stock investors, it's free and covers every market in the world.
Curious About Other Options?
- Explore high-performing small cap companies that haven't yet garnered significant analyst attention.
- Fuel your portfolio with companies showing strong growth potential, backed by optimistic outlooks both from analysts and management.
- Find companies with promising cash flow potential yet trading below their fair value.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com