
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Earnings Preview: What To Expect From Carnival’s Report
Based in Miami, Florida, Carnival Corporation & plc (CCL) is a prominent cruise operator, shaping leisure travel across key global markets. With a market cap of nearly $30.5 billion, the company orchestrates a portfolio of cruise brands while extending its reach into private destinations, tours, hotels, and transport.
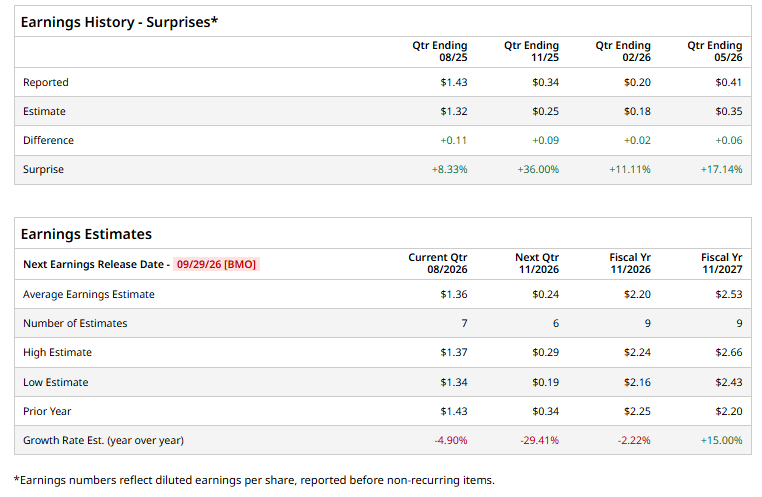
The company is now moving towards its fiscal 2026 third-quarter earnings release on Tuesday, Sept. 29, before markets open. Analysts expect diluted EPS of $1.36, marking a 4.9% drop from $1.43 a year ago-quarter. Carnival has topped EPS estimates in all of the four trailing quarters, signaling steady execution.
Looking beyond the near term, the Street sees a steady drumbeat of earnings growth. Analysts project fiscal year 2026 diluted EPS at $2.20, reflecting a 2.2% year-over-year dip from $2.25 in FY2025. The momentum appears set to carry forward, with fiscal year 2027 EPS estimated at $2.53, implying a further 15% increase.
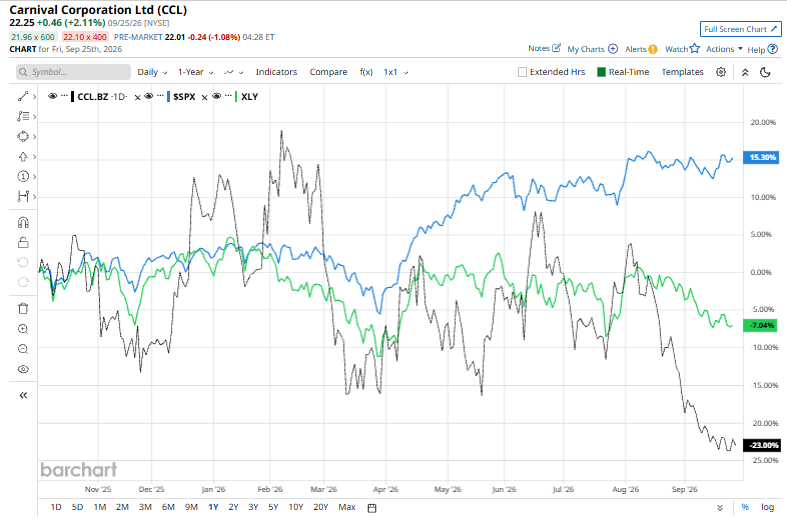
Coming to share performance, CCL stock has declined 27% over the past 52 weeks, lagging behind the S&P 500 Index ($SPX), which rose 17.2% over the same stretch.
Moreover, the stock has trailed its sector benchmark, the State Street Consumer Discretionary Select Sector SPDR ETF (XLY), which has dipped 6.4% over the past year.
Carnival’s underperformance over the past year reflects weaker operating efficiency, limited cash-flow improvement and below-average returns on capital. Its passenger cruise-day performance has lagged peers, while free cash flow margins are expected to remain largely unchanged next year. Meanwhile, relatively low returns on invested capital suggest the company has struggled to generate attractive returns from its investments, weighing on investor sentiment and limiting its ability to keep pace with the broader market.
Analyst sentiment continues to lean firmly bullish. CCL stock holds an overall “Strong Buy” rating, unchanged over the past three months. Of 27 analysts, 20 have assigned CCL stock a “Strong Buy” rating, one suggests “Moderate Buy,” and six recommend “Hold.”
Analysts place the average price target at $33.61, implying potential upside of 51.5% from the prevailing market prices.
On the date of publication, Kritika Sarmah did not have (either directly or indirectly) positions in any of the securities mentioned in this article. All information and data in this article is solely for informational purposes. For more information please view the Barchart Disclosure Policy here.