
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
How Investors Are Reacting To Flotek Industries (FTK) New Loan Funding
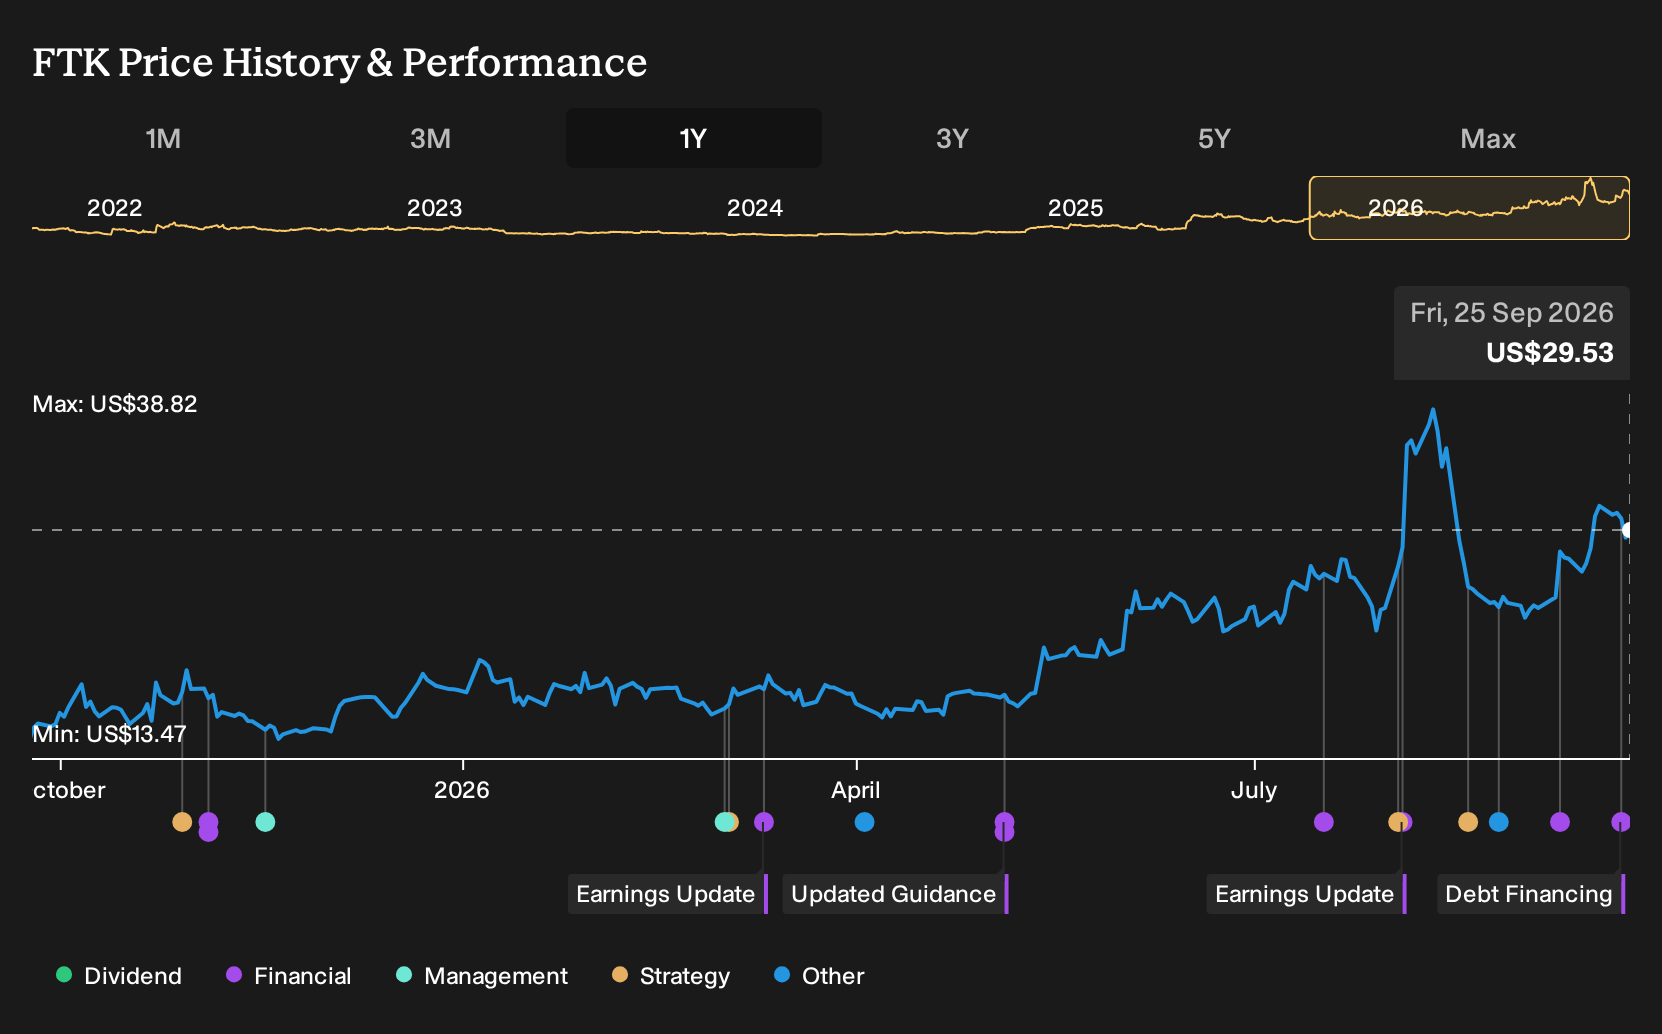
- Flotek Industries announced a new secured term loan providing initial funding of $75 million and up to $45 million in delayed-draw capacity, alongside an extension of its separate asset-based loan to October 31, 2027.
- The funding plan focuses on refinancing existing debt and directing fresh capital into Flotek Industries' Data Analytics segment, capital expenditure, and working capital. This shifts the balance of risk toward execution on higher-margin, technology-led services.
- We will now look at how Flotek Industries' investment narrative could be reshaped by this sizeable new term loan and liquidity runway.
Flotek Industries Investment Narrative Recap
For a shareholder in Flotek Industries, the core belief is that the mix keeps shifting toward higher margin Data Analytics while Chemistry Technologies stays relevant in a world that is slowly decarbonizing. The fresh term loan points the near term story squarely at funding that pivot, since a large chunk of the proceeds is earmarked for the Data Analytics segment.
The key near term catalyst is execution on existing and new analytics contracts so earnings quality and cash generation keep up with higher leverage. The biggest risk still sits with customer concentration and scaling newer offerings from pilots to full deployments. This financing does not remove those issues. It provides more time and resources to address them.
The new term loan announced on 23 September 2026 matters because it refinances the prior US$40 million facility and stretches the maturity profile out to 2031. That longer runway, together with the absence of amortization or a cash sweep in the first two years, gives Flotek Industries room to pursue multi year projects without the same balance sheet pressure.
This is important for catalysts around Data Analytics, where contracts, pilots and infrastructure deployments can take time to ramp. The extended US$20 million asset based loan to October 2027, together with up to US$120 million of total term capacity, supports working capital and capital expenditure tied to those opportunities. Execution on that spend, and not the financing itself, is what now shapes the risk reward profile.
Flotek Industries Forward Expectations Through 2029
Flotek Industries' current analyst narrative centers on a business that is expected to grow its top line while earnings step down from today's level. The outlook that sits behind the consensus price targets assumes that the new capital structure and the focus on Data Analytics still translate into expanding revenue, even if profitability metrics compress.
Recent forecasts point to revenue climbing at 7.3% per year over the next three years. Analysts also build in a move from 13.0% profit margins today to 8.0% in three years. That combination sets up a scenario where sales grow, yet the profit pool tightens as the mix of contracts, pricing, and cost structure shifts.
On earnings, the same set of estimates has Flotek Industries generating $38.0 million today and $29.1 million by 2029. That is an earnings decline of $8.9 million over the period, not an increase. The consensus forecast is anchored to September 2029, so investors are effectively judging whether a lower profit base in that year can still support a higher valuation multiple.
Flotek Industries' narrative projects $362.3 million revenue and $29.1 million earnings by 2029. This requires 7.3% yearly revenue growth and an earnings decline of $8.9 million from $38.0 million.
The same research suggests the equity would trade on a P/E of 72.1x those 2029 earnings, compared with 22.2x today and 23.0x for the broader US Chemicals industry. That is a large gap to the sector benchmark and implies investors would need to be comfortable with a much richer multiple on a smaller earnings base. The discount rate referenced in this work sits around 7.4%, which is used to translate those future estimates into today's fair value range.
Analyst price targets cluster around $38.25, with the highest at $43.0 and the lowest at $32.0. Against a current share price of $23.37 as of late September 2026, that average target is 38.9% higher. The key tension for readers is clear. The consensus expects revenue growth and continued investment in higher margin services, alongside thinner margins and lower earnings in 2029 than today, yet still assigns a richer valuation to Flotek Industries than the market currently does.
Uncover why Flotek Industries' fair value indicates a 30% potential upside to its current price before that gap starts to close.
Exploring Other Perspectives
One alternate view on Flotek Industries leans heavily on customer concentration risk. The most cautious analysts were already projecting higher revenue of about $430.0 million by 2029 and earnings near $32.8 million, yet still framed that growth as fragile. Those estimates came before this new term loan, so expect opinions to shift.
Explore 3 other Flotek Industries fair value estimates, including one that suggests as much as 51% downside from the current price.
Form Your Own Verdict
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Flotek Industries research is our analysis highlighting 3 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for Flotek Industries. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Flotek Industries' overall financial health at a glance.
Looking For More Flotek Industries Style Investment Ideas?
If the Flotek Industries story has you thinking about other potential opportunities, it can help to scan a wider field of companies that line up with your risk profile, income needs, and balance sheet comfort level. The Simply Wall St Screener lets you filter for the traits that matter most, rather than starting from a blank page.
- For readers focused on quality at a reasonable price, consider a curated set of companies that combine solid fundamentals with attractive valuations through the 32 high quality undervalued stocks.
- If income and resilience are a priority, you can zero in on businesses that pair higher yields with more durable payouts by checking out the 8 dividend fortresses.
- For those who care most about financial strength, narrow your watchlist to businesses with stronger balance sheets and healthier fundamentals using the list of solid balance sheet and fundamentals (24 results).
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com