
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Slow ARR Growth Might Change The Case For Investing In Bentley Systems (BSY)
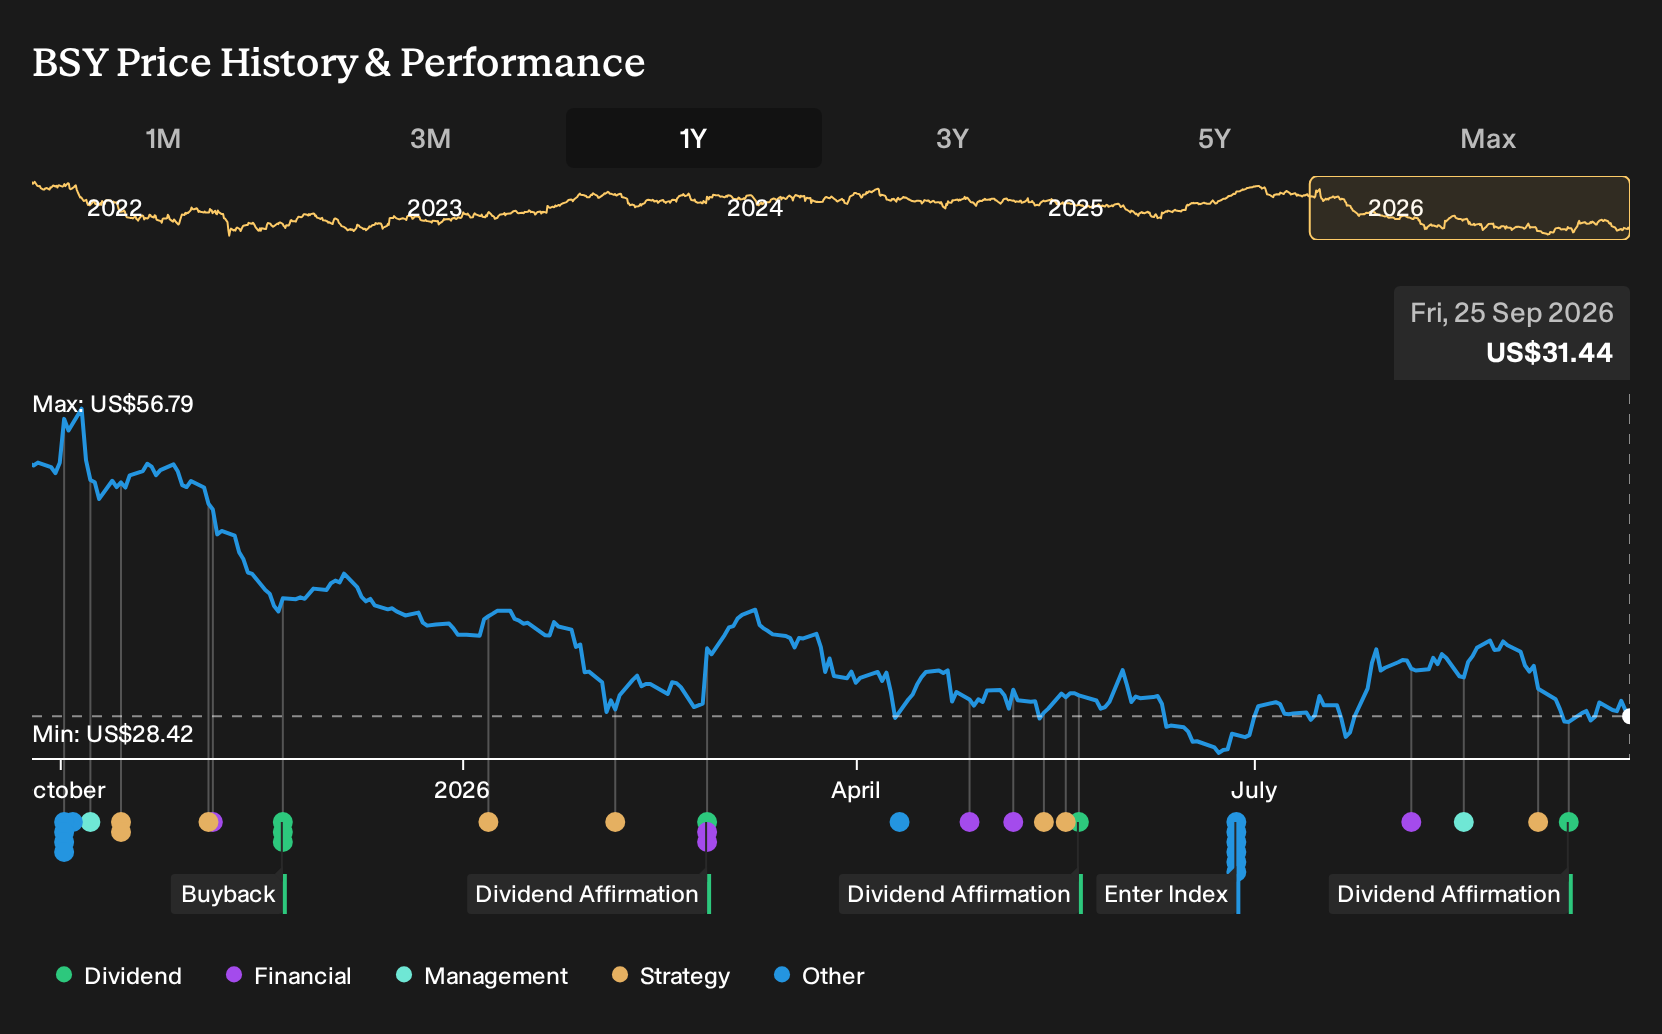
- Bentley Systems has recently been under scrutiny, as annual recurring revenue growth has been described as underwhelming, while operating margins remain flat despite revenue expansion and a supportive broader market backdrop.
- The combination of muted subscription momentum and stagnant profitability raises questions about how effectively Bentley Systems is converting infrastructure software demand into scalable earnings quality.
- We will now look at how Bentley Systems' softer recurring revenue trends could reshape the investment narrative investors have been relying on.
Bentley Systems Investment Narrative Recap
For an investor to stay with Bentley Systems, the core belief is that infrastructure software demand and the shift to cloud and digital twins should eventually show up clearly in recurring revenue and cleaner earnings. The recent share price decline and underwhelming ARR growth put more weight on execution. In the near term, the key question is whether subscription activity can regain momentum without sacrificing pricing.
The biggest risk right now is that flat operating margins become a ceiling rather than a pause, particularly with high R&D and debt already in the mix. If cost discipline and product mix do not improve, the story around operating leverage weakens. If ARR stabilises even at modest growth, this news appears more like a sentiment reset than a break in the thesis.
There have been no fresh operational announcements tied directly to this share price move, which leaves the latest reported run rate and margin profile as the main reference points for you. That shifts attention toward the existing software portfolio, from MicroStation to the iTwin platform, and how effectively those products are being monetised across subscriptions.
In this context, the practical catalyst is straightforward. You want to see evidence that Bentley Systems can translate its broad customer base across regions into steadier ARR growth and more efficient use of operating spend. Without new deals or product disclosures in view, the next data that matters most will be the upcoming earnings releases and any updated commentary on subscription trends and cost structure.
What The Current Forecasts Assume For Bentley Systems
Bentley Systems' current consensus view points to US$2.1b in revenue and US$508.3m in earnings by 2029. That profile sits on top of analysts assuming 11.3% yearly revenue growth and an earnings move of about 80% from US$281.9m today to the 2029 forecast level.
Uncover why Bentley Systems' fair value indicates a 43% potential upside to its current price, a gap that could narrow quickly.
Exploring Other Perspectives
One optimistic twist on Bentley Systems focuses on AI driven asset analytics as a potential accelerator. The most upbeat analysts were modelling about US$2.2b of revenue and earnings near US$588.2m by 2029 before this share price setback. That is far rosier than consensus and may shift if sentiment on recurring revenue weakens further.
Explore 2 other Bentley Systems fair value estimates, including one that suggests there could be as much as 72% upside from the current price.
Decide For Yourself
Disagree with existing narratives? Extraordinary investment outcomes rarely come from following the herd, so rely on your own analysis.
- A great starting point for your Bentley Systems research is our analysis highlighting 4 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Bentley Systems. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Bentley Systems' overall financial health at a glance.
Looking For More Investment Ideas Beyond Bentley Systems?
If Bentley Systems is now a question mark in your portfolio, you might use this moment to widen your opportunity set. The Simply Wall St Screener lets you shift attention toward other businesses with recurring revenue strength, balance sheet resilience, or income profiles that might better match your goals.
- If you want potential mispricing combined with quality, you could review our 32 high quality undervalued stocks which may offer a different mix of fundamentals and earnings resilience compared with Bentley Systems.
- For investors who are most focused on staying power and capital preservation, you could start with our 30 resilient stocks with low risk scores to look at businesses that clear a stricter risk filter.
- If you are hunting for future leaders before they are widely followed, the 16 high quality undiscovered gems can highlight companies with solid metrics that are still off most radars.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com