
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
West Pharmaceutical Services (WST) Is Back In The Spotlight, What Is Catching Attention?
West Pharmaceutical Services (WST) has drawn fresh attention after its recent share move, with the stock closing at US$370.44 and logging mixed short and longer term returns.
For context, West Pharmaceutical Services has a 1-month share price return of 9.77% and a year-to-date share price gain of 34.02%. The 1-year total shareholder return of 42.75% points to momentum that has been building rather than fading.
Scan beyond West Pharmaceutical Services and see how its recent momentum compares with 32 high quality undervalued stocks, which may offer a different balance of quality and price.
West Pharmaceutical Services looks like a high quality operation backed by solid shareholder returns. After this latest jump to US$370.44, the real question is whether that strength is already fully reflected in the price.
Most Popular Narrative: 8.6% Undervalued
West Pharmaceutical Services closed at $370.44, while the most followed narrative pegs fair value around $405.38, so the gap really comes down to how durable its higher margin opportunities prove to be.
The strategic focus on expanding the contract manufacturing business into drug handling, including a Dublin program expected to reach more than US$60 million of revenue at full ramp by around 2028 and targeted gross margins above 30% compared with mid to high teens today for West Vantage overall, could lift segment profitability and support group net margin and earnings as additional programs are added over time.
See why 13 investors see West Pharmaceutical Services as 9% undervalued.
Result: Fair Value of $405.38 (UNDERVALUED)
Still, this hinges on West Pharmaceutical Services keeping high value GLP 1 and biologics demand on track, and on contract manufacturing margins not slipping during the CGM exit and Dublin ramp.
Find out about the key risks to this West Pharmaceutical Services narrative.
Another View On West Pharmaceutical Services
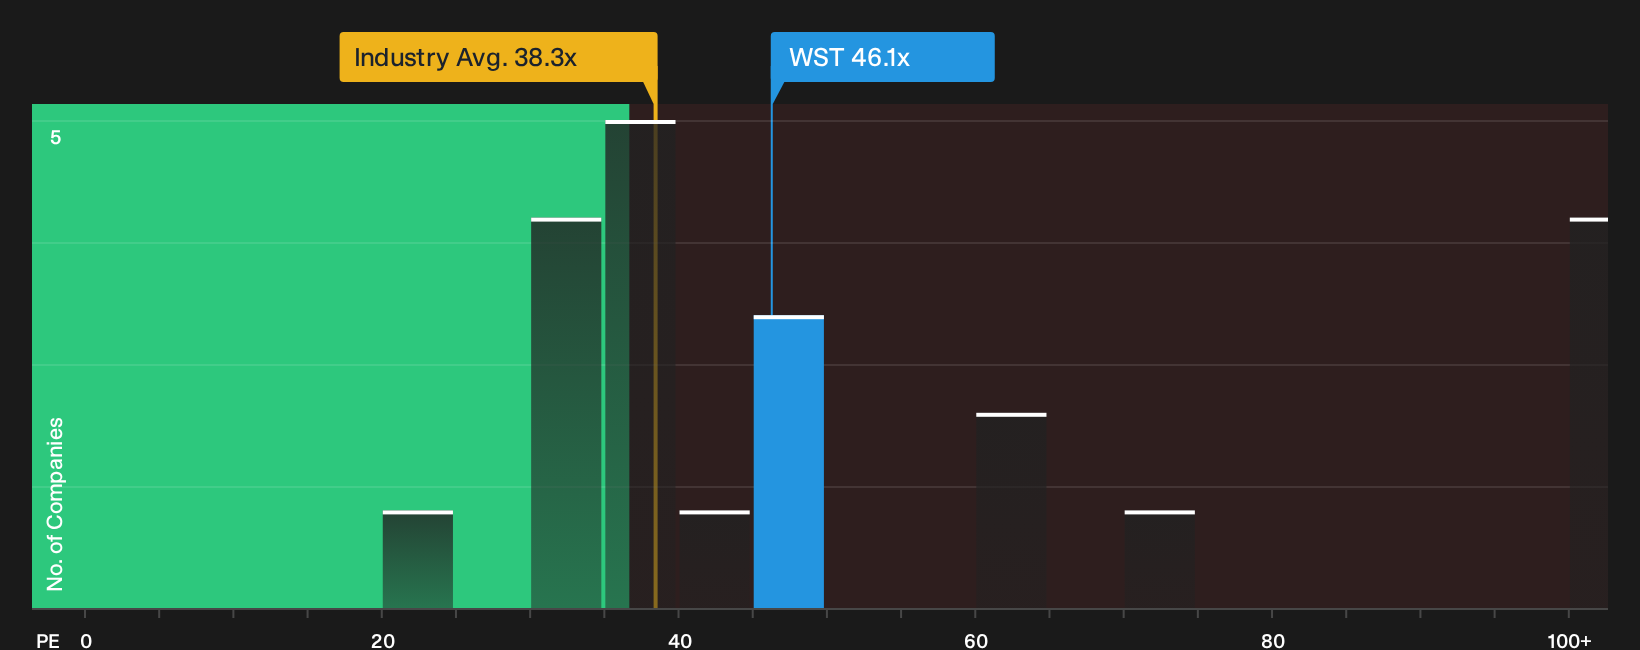
The first narrative leans on future earnings and margin expansion to argue West Pharmaceutical Services looks 8.6% undervalued at $405.38. A plain P/E check tells a different story. WST trades on 46.1x earnings versus a fair ratio of 23.6x and a Global Life Sciences average of 38.3x, which points to valuation risk if expectations cool. Which signal do you trust more when real money is on the line?
To pressure test the current price against the earnings multiple and that fair ratio, it is worth digging into the numbers behind the premium, then comparing them with peer valuations and quality metrics: See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals or quiet opportunity, either way it pays to move quickly, review the underlying assumptions yourself and weigh up both sides of the story. To see what is driving optimism around West Pharmaceutical Services, take a closer look at its 2 key rewards.
Want more ideas beyond West Pharmaceutical Services?
If you stop with West Pharmaceutical Services, you only see a fraction of what the market offers. Put the Simply Wall St Screener to work and widen your opportunity set.
- Spot potential turnaround stories early by scanning 7 elite penny stocks with strong financials that already pair higher risk with measurable financial strength.
- Zero in on pricing gaps by reviewing 16 high quality undiscovered gems that combine robust fundamentals with relatively low market attention.
- Strengthen your core holdings by filtering for 30 resilient stocks with low risk scores that aim to keep volatility and balance sheet stress in check.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com