
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
SiTime (SITM) Joins PHLX Index As Valuation Debate Comes Into Focus
SiTime (SITM) has been added to the PHLX Semiconductor Sector Index, putting the timing-chip specialist on the radar of more index-linked funds and sector-focused investors watching semiconductor benchmarks.
Recent trading reflects that shift in attention. SiTime’s share price has rallied, with a 1-month share price return of 18.72% and a year-to-date share price return of 79.01%. The 1-year total shareholder return of 125.95% and 3-year total shareholder return of almost 5x suggest momentum has been strong over both shorter and longer horizons.
Scan SiTime’s peers receiving similar index-driven attention by reviewing the hand picked 85 AI infrastructure stocks that is now capturing fund flows into semiconductor and AI hardware enablers.
SiTime now trades about 28% below the average analyst target after a sharp run, which leaves one tension: Is the market fairly discounting risk or underestimating this timing-chip story?
Most Popular Narrative: 23% Undervalued
SiTime's most followed valuation storyline points to a fair value above the last close of $662.27. This frames the current rally as still leaving a gap to that narrative target.
Expansion of SiTime's content per device, particularly through customized clocks and clocking systems for AI, networking, and hyperscale platforms, enables increased dollar content per design win, directly supporting top-line growth and improving gross margins as these higher-ASP products become a greater share of sales.
Broadening adoption across automotive (notably with L3+/L4 ADAS, robotaxis), industrial robotics, and defense applications positions SiTime to benefit from the long-term technological shift toward fully autonomous systems, propelling future revenue growth as these markets scale.
See why 9 investors see SiTime as 23% undervalued.
Result: Fair Value of $864.38 (UNDERVALUED)
Still, SiTime's heavy reliance on AI data center demand, along with the need for constant high-end R&D investment, could quickly challenge that undervaluation storyline.
Find out about the key risks to this SiTime narrative.
Another View On SiTime’s Valuation
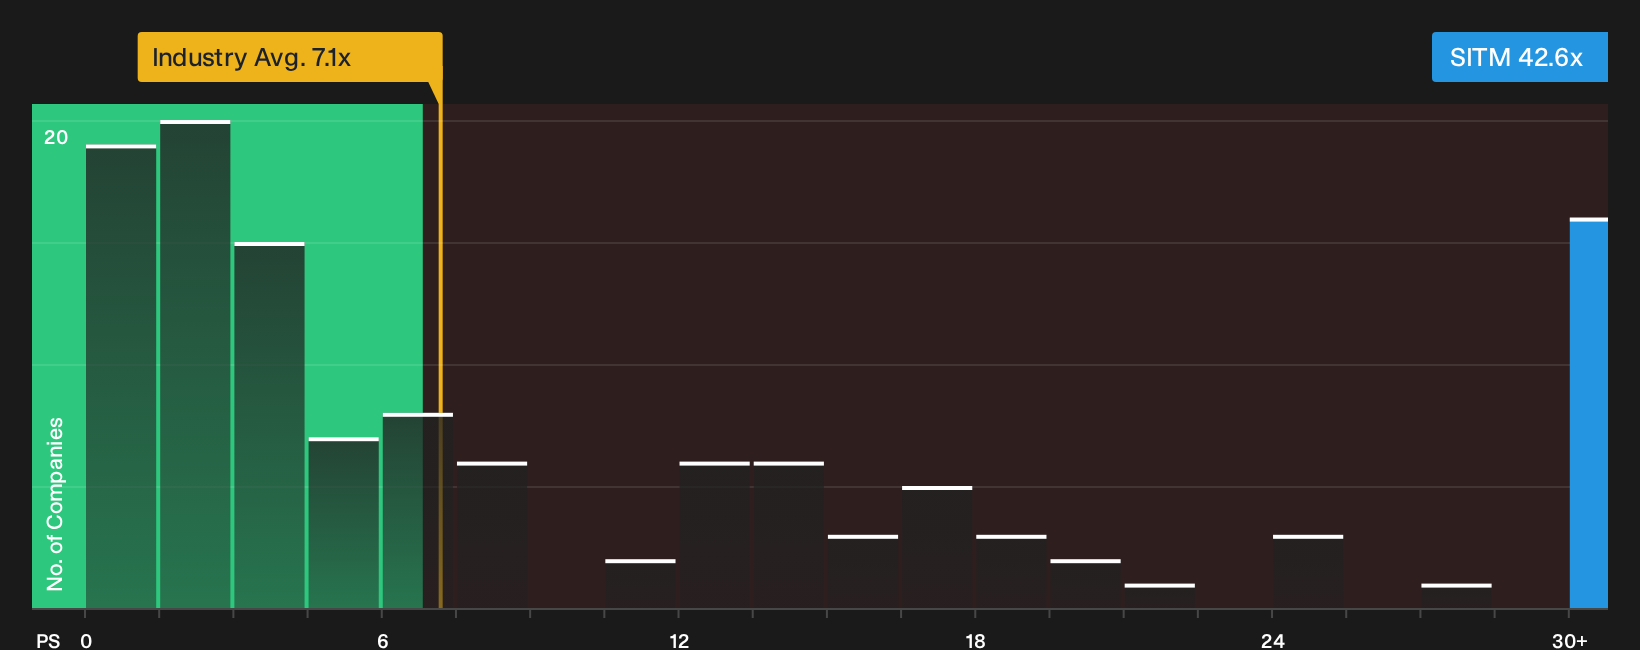
Analysts frame SiTime as about 23% undervalued against a narrative fair value of $864.38, yet the market is paying a P/S ratio of 42.6x. That is sharply higher than both the US Semiconductor industry at 7.1x and an estimated fair ratio of 24.5x, which points to meaningful valuation risk if sentiment cools.
This kind of gap means expectations for future execution are already heavy, so any wobble in growth, margins or AI demand could hit the multiple hard before earnings have time to catch up. Does this rich P/S signal a long runway or simply a crowded trade around the SiTime story?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Sentiment around SiTime is clearly mixed, with strong enthusiasm on one side and clear concerns on the other. Move quickly, review the data, and pressure test the story for yourself by weighing the 3 key rewards and 4 important warning signs.
Looking for more investment ideas beyond SiTime?
If SiTime has caught your attention, do not stop here. Broaden your watchlist with fresh ideas that tap different risk levels, income needs, and value angles.
- Target potential mispricing by scanning a curated set of 32 high quality undervalued stocks that pair solid fundamentals with prices that may not fully reflect their underlying strength.
- Strengthen your income stream by focusing on companies in the 8 dividend fortresses that combine higher yields with an emphasis on durability.
- Dial down portfolio stress and concentrate on resilience by reviewing the 30 resilient stocks with low risk scores built to spotlight businesses with steadier profiles.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com