
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Outsourced Trading Win Could Be A Big Deal For Northern Trust Stock (NTRS)
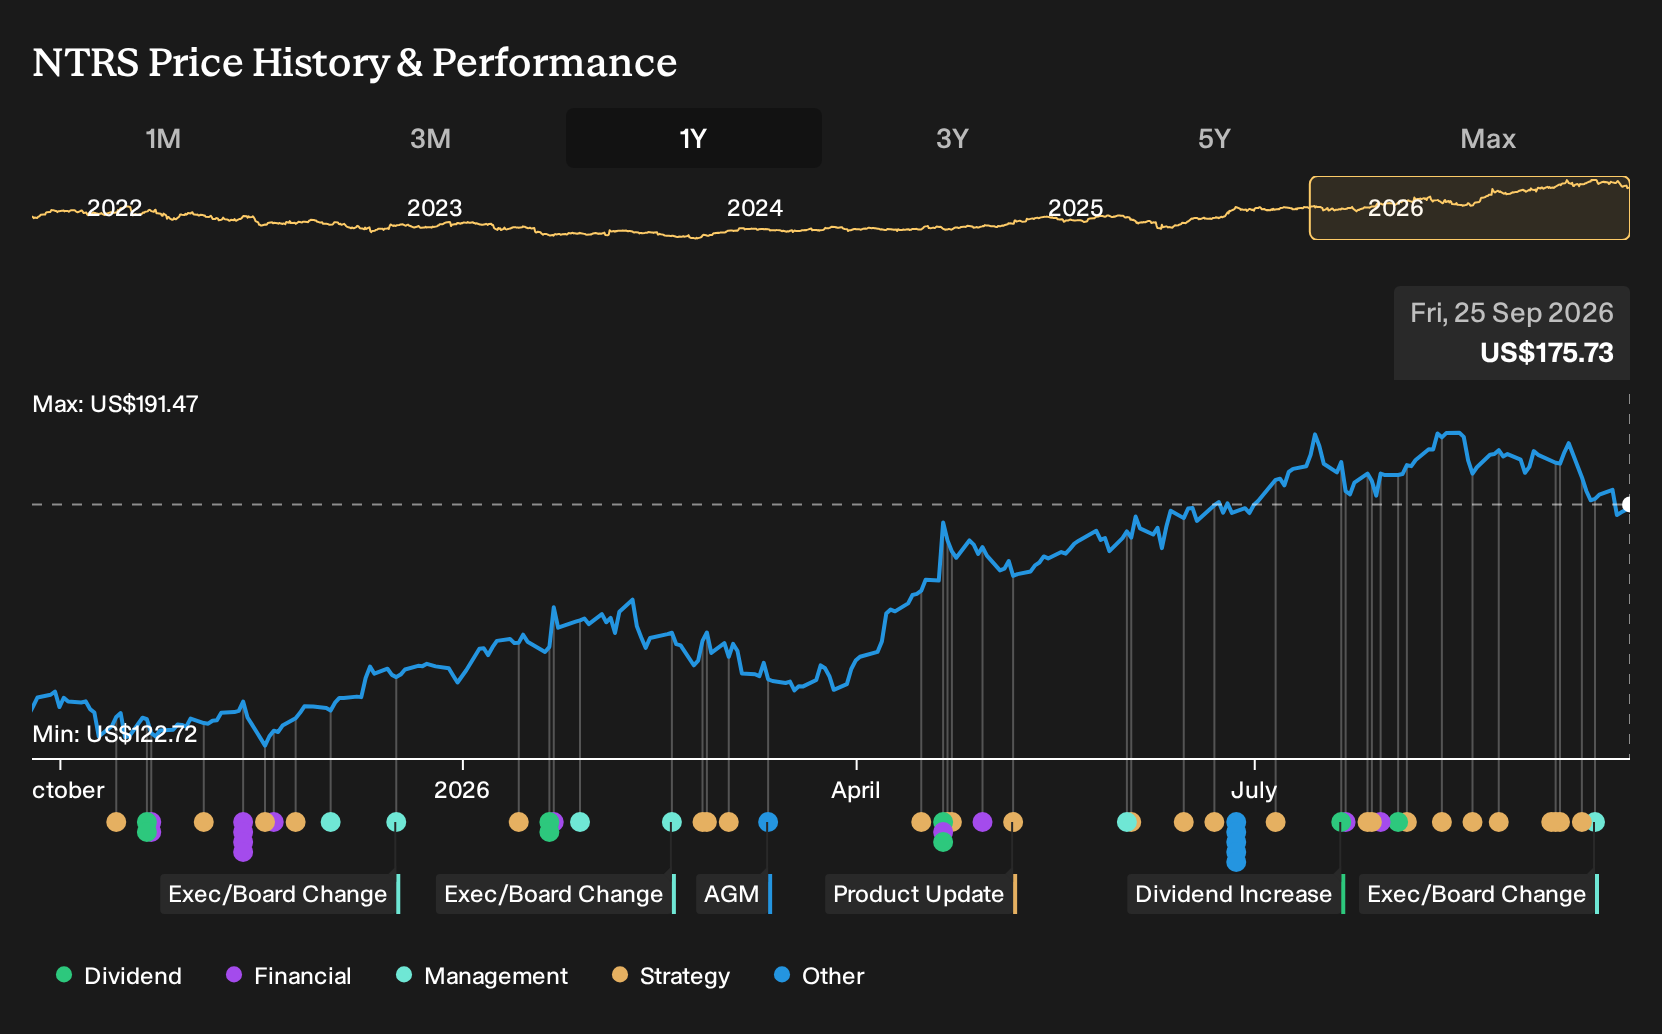
- In September 2026, J O Hambro Capital Management appointed Northern Trust’s Integrated Trading Solutions desk as its sole outsourced trading provider, extending a long running asset servicing relationship that already covers custody, fund accounting, middle office, transfer agency, depositary and currency management.
- The mandate shifts J O Hambro Capital Management’s trading operations into Northern Trust’s agency only global platform, with parts of J O Hambro Capital Management’s trading team invited to move across. This deepens operational integration and could reshape how Northern Trust scales its capital markets services business.
- We will now examine how Northern Trust’s investment narrative could be influenced by becoming J O Hambro’s exclusive outsourced trading provider.
Scan other asset servicers and outsourced trading specialists that share Northern Trust’s institutional focus, with a curated set of list of solid balance sheet and fundamentals (24 results)
Northern Trust Investment Narrative Recap
Northern Trust appeals to shareholders who want a fee-heavy financial group that focuses on asset servicing, wealth management and tech-driven efficiency rather than pure lending growth. The near-term story still revolves around whether management can keep expense growth below revenue growth while competition for advisers and price pressure in liquidity products affect the model.
The J O Hambro outsourced trading mandate and prior guidance for positive operating leverage both point toward deeper use of the One Northern Trust approach. The biggest short-term swing factor remains execution on productivity and AI projects. The main risk is cost creep from talent and technology that outpaces relatively modest revenue growth assumptions.
The J O Hambro trading deal looks most relevant for current catalysts. It directly connects to Integrated Trading Solutions and capital markets services, which have been a growing fee engine and part of the reason management lifted 2026 revenue and net interest income guidance. For an investor, this contract illustrates how Northern Trust can deepen relationships with existing clients rather than rely on headline client wins alone.
There is also a clear link to the new head of private markets role in Emea. Alternatives assets under administration already sit above US$1b, and private markets servicing often involves complex trading, FX and liquidity needs. If the business continues to win outsourced trading flows from clients like J O Hambro while building out private markets capabilities, that combination could be more important for fee mix and operating leverage than any single contract announcement.
Northern Trust Consensus Assumptions and Valuation Set Up
Analysts frame Northern Trust’s medium term outlook around modest expansion rather than a radical reset. The current models point to revenue growth of 3.6% each year over the next three years, paired with an uplift in profit margins from 24.0% today to 25.1% by around 2029. Earnings are projected to move from US$2.2b today to US$2.5b, which represents an increase of roughly US$0.3b over that period, with most forecasts clustering around that figure rather than scattering widely.
The consensus view expects this earnings profile in 2029 to sit alongside a P/E of 15.7x, compared with about 15.0x today and well below the 39.6x currently quoted for the broader US capital markets peer group. That implies investors who align with this framework are treating Northern Trust as a steadier fee focused franchise rather than paying a premium multiple for faster top line expansion. Forecasts also bake in a 3.26% annual reduction in the share count over the next three years, so part of the expected earnings per share outcome reflects buybacks rather than only underlying profit growth.
On pricing, the analyst group has settled on a consensus target of US$184.27, bracketed by a bullish end point of US$208.00 and a more cautious floor of US$158.00. With Northern Trust stock trading around US$178.95, that central estimate sits just 2.9% above the market level, which signals that many commentators already view the shares as roughly aligned with their base case projections. Readers considering their own stance can use this range as a reference point, then adjust the inputs if they hold a different view on fees from outsourced trading, private markets flows or the cost of technology.
Northern Trust's narrative projects US$10.1b revenue and US$2.5b earnings by 2029. This requires 3.6% yearly revenue growth and an earnings increase of about US$0.3b from US$2.2b today.
Uncover how Northern Trust's fair value indicates a 5% potential upside to its current price that may not last much longer.
Exploring Other Perspectives
Two fair value estimates from the Simply Wall St Community cluster tightly between about US$180.59 and US$184.27, which lines up closely with recent Northern Trust pricing. These private investors have not yet incorporated the J O Hambro mandate or the new Emea private markets role. You may want to compare their views with your own assessment of competition risks, technology spending and outsourced trading momentum.
Explore another Northern Trust fair value estimate, including one that suggests it could be worth just $180.59.
Reach Your Own Conclusion
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Northern Trust research is our analysis highlighting 4 key rewards that could impact your investment decision.
- See our latest analysis for Northern Trust. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Northern Trust's overall financial health at a glance.
Looking for more Northern Trust style ideas?
If the Northern Trust story has sharpened your thinking, widen the lens and compare it with other companies that match your risk, income and balance sheet preferences using the Simply Wall St Screener.
- For investors who want potential upside with strict balance sheet discipline, scan a curated 30 resilient stocks with low risk scores that aim to keep downside risk in check.
- If income is your priority, focus on reliable cash returns with a screener built around 8 dividend fortresses that have historically supported higher payout levels.
- If you are hunting for under the radar opportunities, filter for strong fundamentals that the crowd may have missed by reviewing 16 high quality undiscovered gems.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com