
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
O'Reilly Automotive (ORLY) Looks Undervalued On Paper, Is The Premium P E Multiple Justified?
O'Reilly Automotive (ORLY) is back in focus after recent share price moves that leave the stock down over the past month and the past 3 months, despite positive annual revenue and net income growth.
Recent trading paints a mixed picture for O'Reilly Automotive. The 7 day share price return of 3.9% contrasts with a 30 day decline of 2.7% and a 90 day slide of 6.5%, while the 1 year total shareholder return is down 19.9% despite 3 year and 5 year total shareholder returns of 43.8% and 115.9% respectively. This suggests shorter term momentum has faded even as longer term holders still sit on sizeable gains.
Scan how O'Reilly Automotive stacks up against other potential rebound stories by reviewing the 32 high quality undervalued stocks that our filters surface from across the market.
O'Reilly Automotive appears to be a solid operator on the surface, with revenue and net income both rising while the share price has retreated. Does that pullback leave the stock attractively priced, or is it still demanding?
Most Popular Narrative: 20% Undervalued
On the most followed view of O'Reilly Automotive, the estimated fair value of $107.80 sits well above the last close of $86.12. This frames the recent share pullback as a pricing gap rather than a simple loss of confidence.
Private label penetration above 50% of revenue and sourcing from multiple suppliers for single SKUs, combined with a reaffirmed 51.5% to 52% gross margin outlook and targeted expansion versus 2025, point to further benefits from scale and sourcing diversification for gross margin and net earnings.
See why 21 investors see O'Reilly Automotive as 20% undervalued.
Result: Fair Value of $107.80 (UNDERVALUED)
Still, the story around O'Reilly Automotive hinges on smooth execution, since higher tariffs or a messy NAPA acquisition outcome could quickly undercut the case that the stock is 20% undervalued.
Find out about the key risks to this O'Reilly Automotive narrative.
Another View On O'Reilly Automotive's Valuation
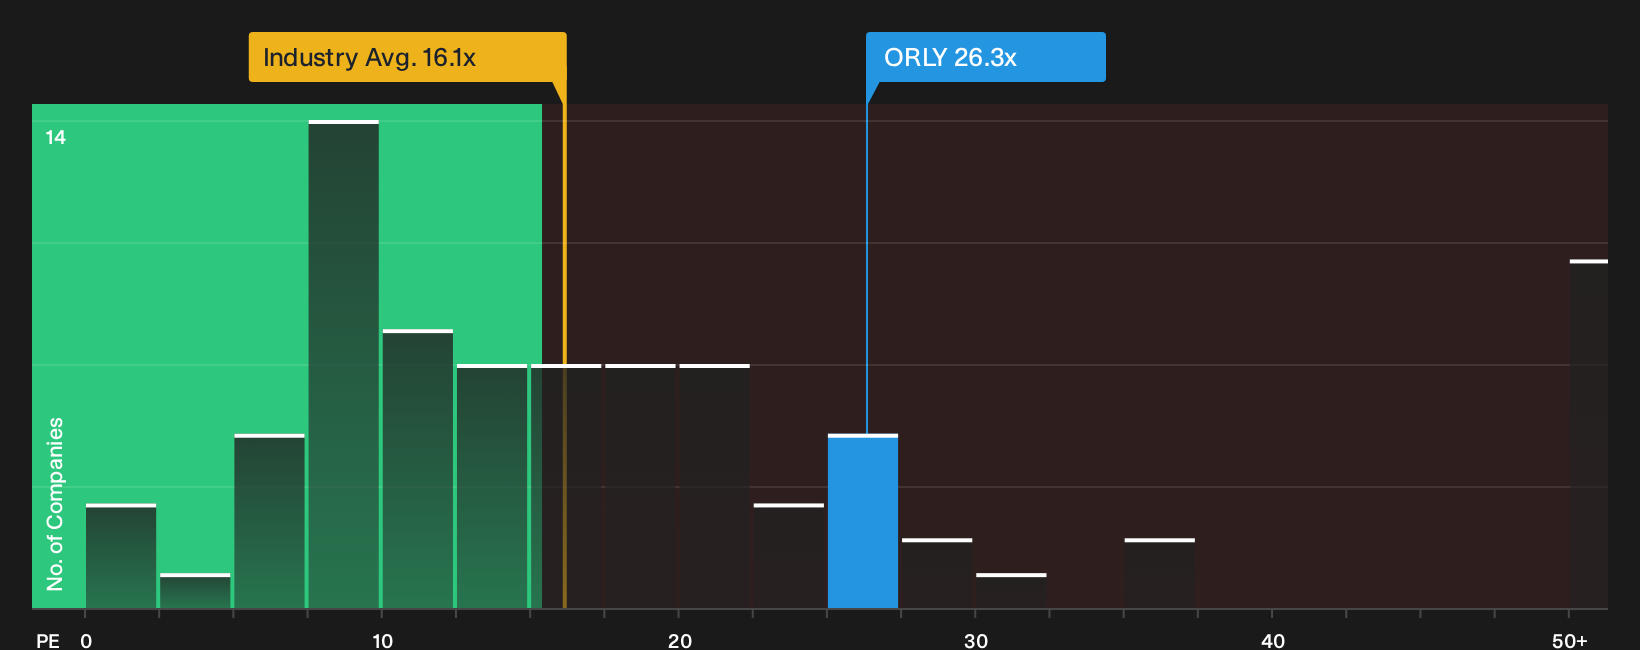
While the consensus fair value for O'Reilly Automotive points to about a 20% upside, the current P/E of 26.3x tells a different story. That multiple sits well above both the US Specialty Retail industry at 16.1x and a fair ratio of 19.6x, which suggests valuation risk if expectations slip.
In plain terms, investors are paying a premium price for O'Reilly Automotive compared with peers and where the fair ratio implies the market could settle. Anyone building a position may want to ask what would need to change for that gap to close.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
That mix of optimism and concern around O'Reilly Automotive will not settle itself. Look through both sides of the ledger and weigh the 3 key rewards and 2 important warning signs.
Ready for more investment ideas beyond O'Reilly Automotive?
If you stop with O'Reilly Automotive, you miss the chance to line up fresh ideas from the Screener that could better match your goals and risk comfort.
- Target potential mispricings by reviewing companies our filters flag as offering value through the 32 high quality undervalued stocks.
- Strengthen your portfolio’s foundation by checking businesses highlighted in the list of solid balance sheet and fundamentals (24 results).
- Aim for stability with upside by scanning opportunities featured in the 30 resilient stocks with low risk scores.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com