
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
bioMérieux (ENXTPA:BIM) Could Be 2% Undervalued On SPINCHIP Launch
bioMérieux (ENXTPA:BIM) has just introduced SPINCHIP, a compact point of care platform. Its first assay measures high sensitivity cardiac troponin I from a single drop of blood.
The SPINCHIP announcement lands at a time when bioMérieux’s share price has shown a 7-day share price return of 7.47% and a 90-day share price return of 13.10%. However, the stock is still down 29.04% on a year-to-date share price basis, and the 1-year total shareholder return has declined 29.92%, which indicates that recent momentum is improving while longer-term performance remains weak.
Seize this moment around bioMérieux's SPINCHIP launch to scan a curated set of resilient healthcare names in our 226 resilient stocks with low risk scores.bioMérieux now trades close to analyst targets yet still shows a sizeable gap to some fair value estimates. After this sharp rebound, does the upside implied by those models still look compelling or already used up?
Most Popular Narrative: 1.7% Undervalued
Against a last close of €77.70, the most followed narrative for bioMérieux points to a fair value of about €79.04, leaving only a narrow implied discount once recent gains are taken into account.
GO. Simple profitability improvement initiatives, including automation and cost management, are already delivering tangible outcomes. These initiatives may enhance net margins and earnings over time.
Investment in research and development, with 12% of sales reinvested, is aimed at sustaining future growth and maximizing returns. This is expected to positively impact revenue and may improve net margins through high-margin innovative products.
See why 5 investors see bioMérieux as 2% undervalued.
Result: Fair Value of €79.04 (UNDERVALUED)
However, the BIOFIRE contract roll off and heavier reliance on the U.S. market could pressure bioMérieux if volumes soften or regulation shifts.
Find out about the key risks to this bioMérieux narrative.
Another View: Multiples Paint A Different Picture For bioMérieux
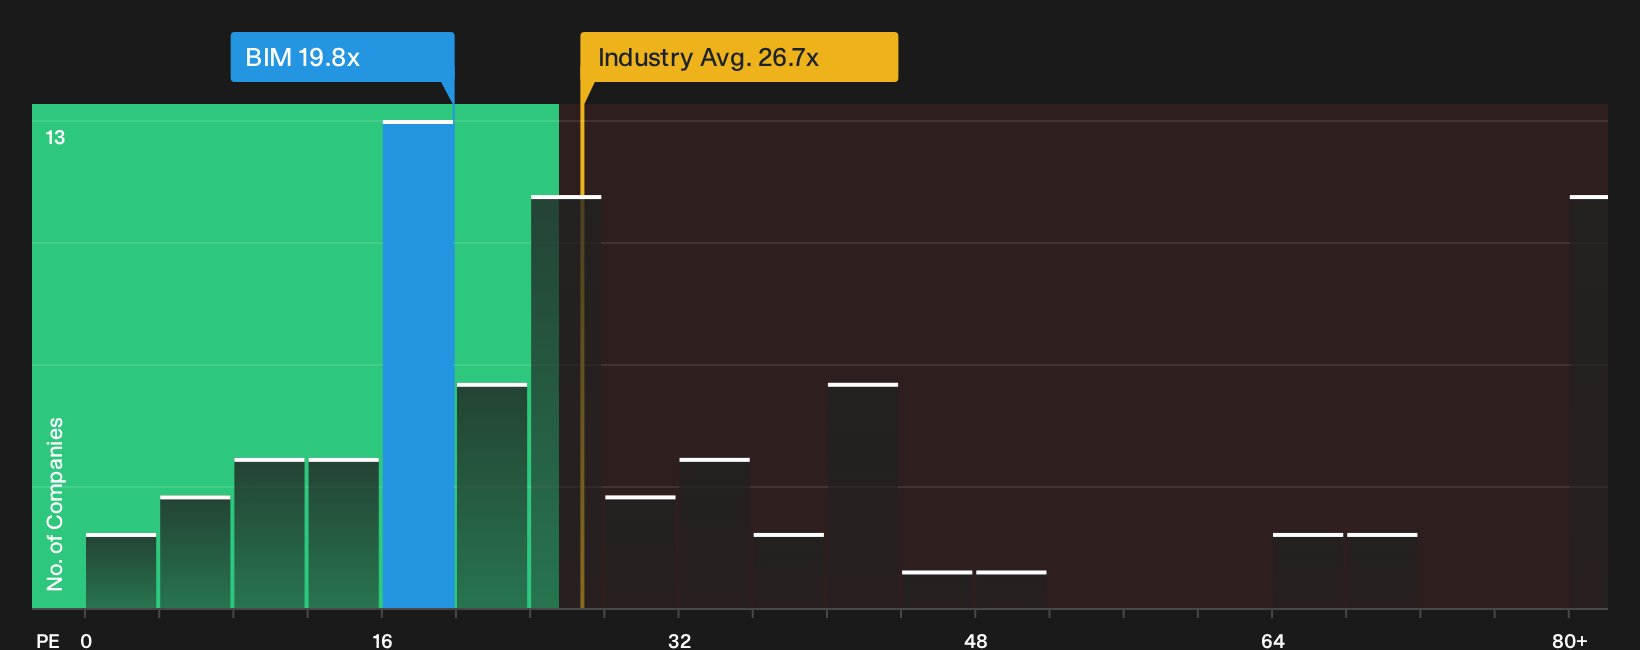
The first narrative has bioMérieux trading only about 1.7% below a fair value of €79.04, yet the share sits roughly 31.1% below one in house fair value estimate and on a 19.8x P/E. That multiple is lower than peers at 22.9x and the wider European medical equipment group at 26.7x, but still above a fair ratio of 18.2x. This hints at both room for rerating and the risk that sentiment simply settles closer to that fair ratio instead.
If you want to stress test this multiples view against a full breakdown of the numbers, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Sentiment around bioMérieux is clearly split, with some investors focusing on recent gains while others worry about past drawdowns, so move quickly and stress test the optimism against your own framework. To see which rewards are driving that positive angle for the business in the data, review the 3 key rewards.
Looking for more investment ideas beyond bioMérieux?
Do not stop with one stock story. Use fresh screeners to spot different kinds of opportunities and build a watchlist that actually reflects how you want to invest.
- Target potential mispricing by scanning a curated pool of quality companies trading below some fair value estimates with the 184 high quality undervalued stocks.
- Prioritise resilience and balance sheet strength by filtering for businesses with solid cash and debt profiles using the list of solid balance sheet and fundamentals (201 results).
- Lock in income focused ideas by zeroing in on stocks that offer 159 dividend fortresses.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com