
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
What Five Star Bancorp Stock's New External Affairs Role Means For Shareholders
- Five Star Bancorp recently appointed Lydia Ramirez as Executive Vice President and Chief External Affairs Officer, a new role focused on aligning the bank’s community commitments with how it serves clients and expands across California.
- By putting a seasoned banking and community leader in charge of external affairs, Five Star Bancorp is making local feedback a core input for how it prioritizes markets, partnerships, and service offerings.
- We will now examine how Five Star Bancorp's investment narrative could evolve as Lydia Ramirez leads its new external affairs function.
Scan how Five Star Bancorp's community focused expansion compares with other regionally focused banks by reviewing our hand picked list of solid balance sheet and fundamentals (24 results) now shaping local growth stories.
Five Star Bancorp Investment Narrative Recap
To own Five Star Bancorp, you need to believe the bank can keep converting relationship banking in Northern California into steady loan and deposit growth while managing its heavy exposure to commercial real estate and concentrated large deposits. The immediate swing factor is whether recent market expansion can support revenue without eroding the bank's efficiency or net interest margin.
Lydia Ramirez's appointment should help execution around community based growth, but it does not materially shift the near term risk profile. The biggest pressure point remains credit and funding risk if regional conditions weaken, particularly in commercial real estate heavy markets and among large deposit clients.
The most relevant development around this news is Five Star Bancorp's recent move into markets like Walnut Creek, Lodi, and Southern California. Those openings increase access to new borrowers and core deposits. This feeds directly into the growth story analysts are modeling, including revenue forecasts and expectations for continued earnings expansion.
That broader push also raises the stakes on execution. New branches and verticals bring higher noninterest costs and potential asset quality volatility if competition forces looser terms. Ramirez's role ties community feedback into that build out. This could support more resilient deposits and better credit selection if management sticks to relationship based underwriting and disciplined pricing.
Five Star Bancorp's current analyst storyline points to revenues of $296.8 million and earnings of $104.0 million by 2029. This outlook is built on an assumed 21.0% yearly revenue growth rate and an earnings increase of $32.0 million from $72.0 million today.
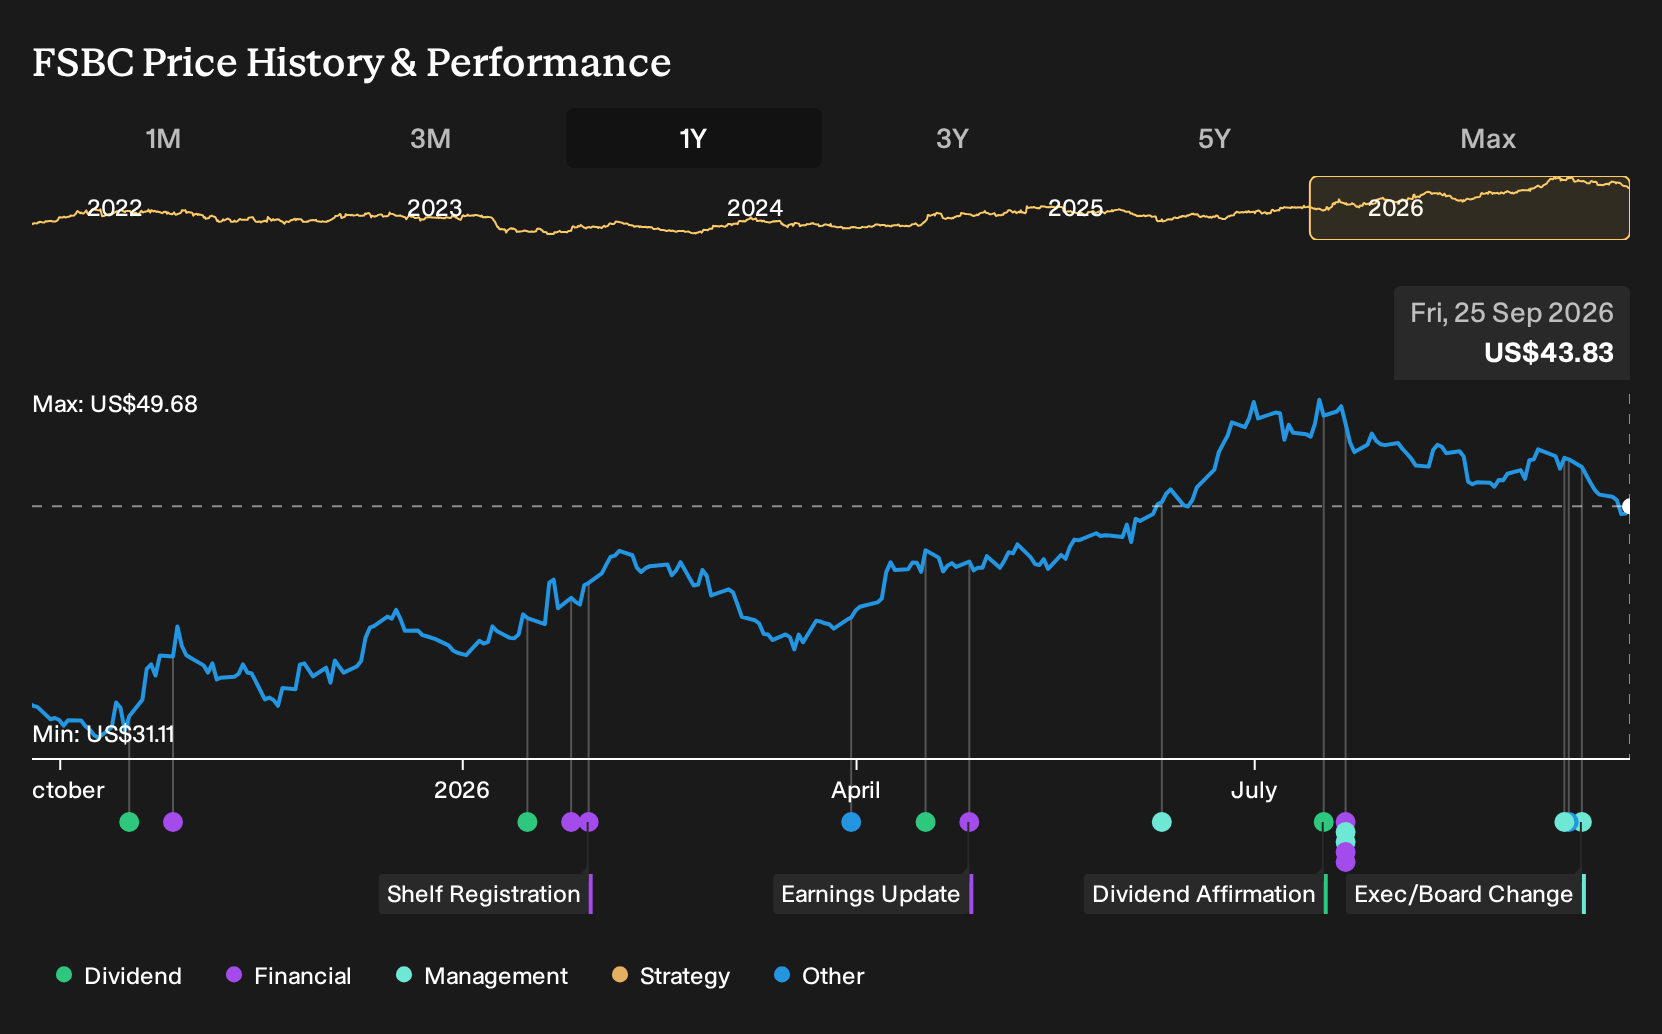
Uncover how Five Star Bancorp's fair value indicates a 12% potential upside to its current price before sentiment closes that discount.
Exploring Other Perspectives
The Simply Wall St Community only includes two fair value views on Five Star Bancorp so far, yet they already span from about $49 to roughly $81 per share. That wide gap shows how differently retail investors can frame the same story. When you add concentrated commercial real estate exposure and branch expansion costs, you have multiple moving parts that readers may want to explore through several contrasting viewpoints.
Explore another Five Star Bancorp fair value estimate, including one that suggests it could be worth just $49.00.
Decide For Yourself
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Five Star Bancorp research is our analysis highlighting 3 key rewards that could impact your investment decision.
- See our latest analysis for Five Star Bancorp. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Five Star Bancorp's overall financial health at a glance.
Looking for more investment ideas beyond Five Star Bancorp?
If the Five Star Bancorp story has you thinking about portfolio upgrades, it can help to scan a broader set of companies that match the kind of balance sheet strength, income potential, or upside profile you are looking for.
- For investors who want potential upside without stretching on quality, check out 32 high quality undervalued stocks that pair solid fundamentals with prices that may not fully reflect them yet.
- If income is your priority, focus on stability and payout strength with our curated 8 dividend fortresses that aim to combine higher yields with resilient cash flows.
- When capital preservation matters most, start with resilience by reviewing a 30 resilient stocks with low risk scores chosen for stronger financial footing and lower overall risk scores.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com