
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Learn Why The Bull Case For Renasant Stock Could Change Following CFO Appointment
- Renasant recently appointed longtime bank analyst Catherine Mealor as Chief Financial Officer, a leadership change arriving while the bank contends with tightening margins, rising deposit costs, and integration work following its merger with The First Bancshares.
- The combination of a new CFO drawn from the analyst community and a larger Southeastern footprint is putting Renasant’s cost discipline, integration execution, and balance sheet mix under sharper investor scrutiny.
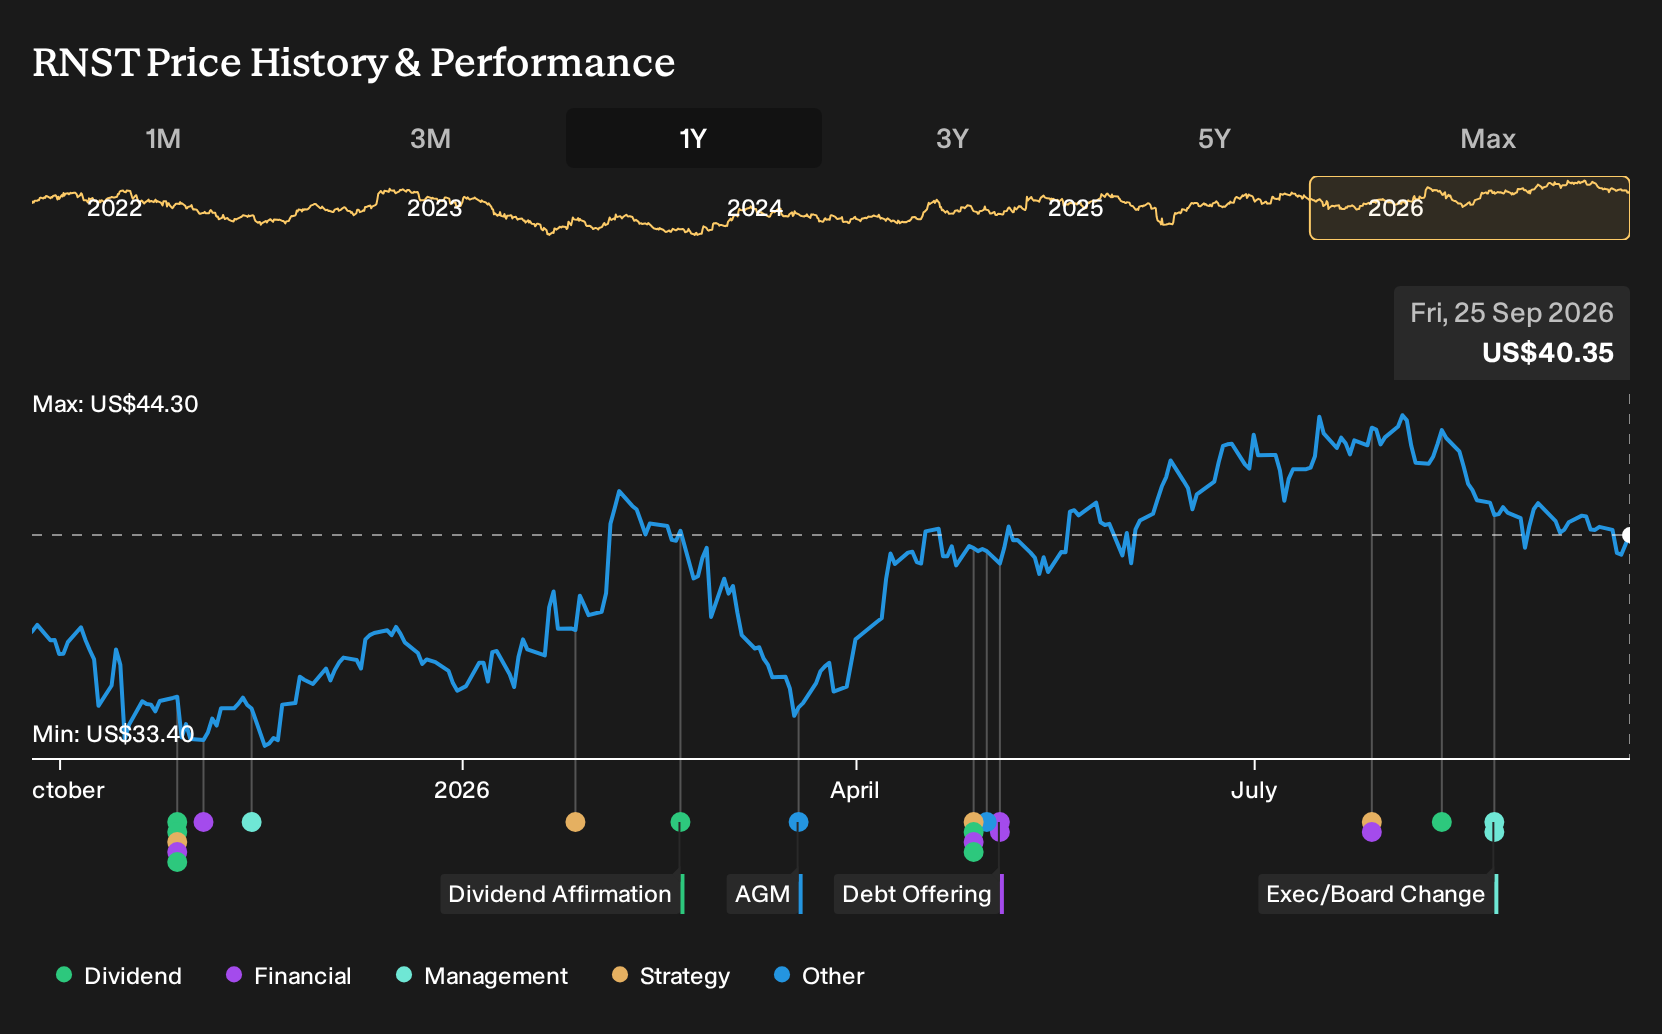
- This analysis examines how Renasant’s investment narrative is being reshaped by Catherine Mealor’s arrival as CFO during merger integration and a period of margin pressure.
Scan how Renasant compares with other potential undervalued banks and regional lenders by checking our curated list of 32 high quality undervalued stocks.
Renasant Investment Narrative Recap
To own Renasant, you need to be comfortable with a regional bank that leans heavily on traditional lending in the Southeast and is working through tighter margins and rising deposit costs. The key near term swing factor is how quickly the merged franchise with The First Bancshares can support stable earnings while funding stays expensive. Catherine Mealor’s appointment as CFO adds focus on cost control and balance sheet mix, but does not fundamentally change that core thesis.
The biggest current risk is still concentration. A harder hit to the Southeastern economy or to real estate credit quality could pressure loan performance and net interest income at the same time that merger integration and technology spend keep expenses elevated. The new finance leadership may influence how Renasant sequences cost saves and digital investment, although the underlying exposure to regional shocks and integration execution remains the main thing to watch.
The headline change is Renasant bringing in longtime bank analyst Catherine Mealor as CFO while it is absorbing The First Bancshares and dealing with margin pressure. That move directly intersects with the main catalyst investors are watching: management’s ability to pull costs out of the combined bank and protect returns while funding costs stay high.
As an analyst, Mealor followed many regional lenders through rate cycles and integration periods. That background could help sharpen how Renasant prioritizes expense actions, deposit mix, and loan growth in its Southeast footprint, where small business formation has been a key part of the story. Execution will show up in basic metrics such as how efficiently the merged institution runs, how stable credit looks, and how consistently the dividend around 2.38% is supported by earnings.
Renasant’s current analyst storyline points to revenues of $1.3b and earnings of $392.7 million by 2029. That path assumes revenue growth of 6.3% a year and an earnings increase of about $78.6 million from today’s $314.1 million profit base.
Uncover why Renasant's fair value indicates a 19% potential upside to its current price that could narrow quickly.
Exploring Other Perspectives
Two fair value inputs from the Simply Wall St Community cluster between $48 and about $54.67 a share, so Renasant screens as potentially inexpensive relative to those private forecasts. Those views do not factor in the Mealor appointment or merger integration risk, so you should weigh them against concentration in the Southeast and real estate credit exposure. Investor opinions can differ widely, so explore several community perspectives before deciding how Renasant fits your portfolio.
Explore another Renasant fair value estimate, including one that suggests as much as 35% upside from the current price!
Decide For Yourself
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Renasant research is our analysis highlighting 4 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Renasant. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Renasant's overall financial health at a glance.
Looking For More Investment Ideas Beyond Renasant?
If the Renasant story has you thinking about portfolio upgrades, it can help to line it up against other opportunities with different risk and income profiles. The Simply Wall St Screener lets you quickly scan for stocks that better match your preferences on value, balance sheet strength, or yield.
- For investors who care most about quality at a sensible entry point, consider scanning a curated 32 high quality undervalued stocks that combine solid fundamentals with prices that may not fully reflect them.
- If dependable income is higher on your list, filter for companies offering resilient payouts through our hand picked 8 dividend fortresses that focus on yield and consistency.
- Those who put capital preservation first can look across a 30 resilient stocks with low risk scores designed to highlight businesses with sturdier financial profiles and lower overall risk scores.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com