
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
3 Asian Penny Stocks With Market Caps Under US$2B
The Asian market is currently navigating a complex landscape, influenced by global economic shifts and technological advancements. Despite the challenges, there remains potential within smaller or less-established companies often referred to as penny stocks. Although the term may seem outdated, these stocks continue to offer opportunities for growth at lower price points when backed by strong financials and clear growth trajectories.
Let's explore several standout options from the results in the screener.
Koh Brothers Eco Engineering (Catalist:5HV)
Simply Wall St Financial Health Rating: ★★★★★☆
Overview: Koh Brothers Eco Engineering Limited is an investment holding company offering engineering, procurement, and construction services across sectors such as infrastructure, water and wastewater treatment, building, biorefinery, and renewable energy projects with a market cap of SGD262.09 million.
Operations: The company generates revenue primarily from its Engineering and Construction segment, which accounts for SGD212.02 million, followed by the Bio-Refinery and Renewable Energy segment at SGD66.05 million.
Market Cap: SGD262.09M
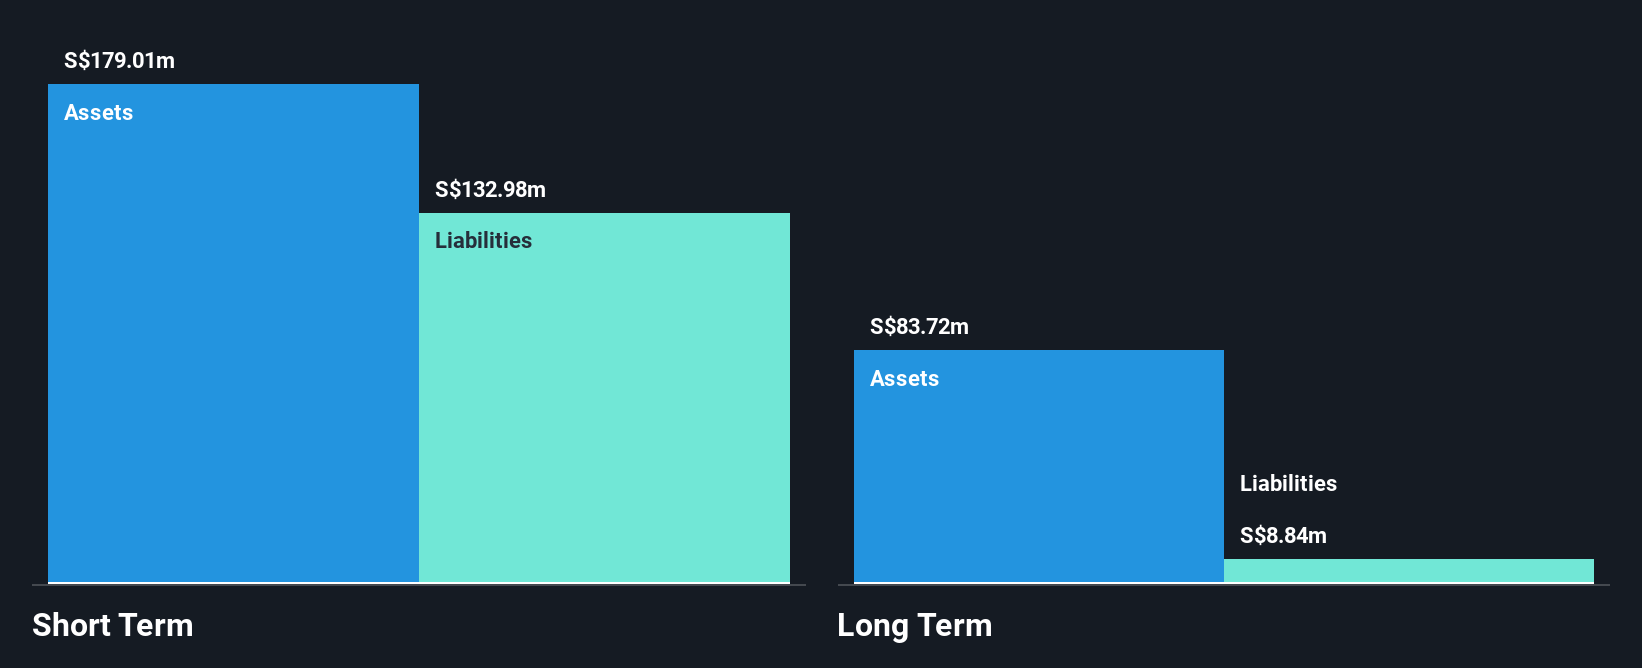
Koh Brothers Eco Engineering Limited has faced challenges with profitability, reporting a net loss of SGD5.67 million for the first half of 2026, attributed to increased material costs and supply chain disruptions affecting its Engineering and Construction division. Despite these hurdles, the company maintains a stable cash runway exceeding one year and has short-term assets surpassing both short-term and long-term liabilities. The management team is experienced, though the company's share price remains highly volatile. Recent executive changes include the resignation of its Financial Controller without concerns over financial reporting practices.
- Dive into the specifics of Koh Brothers Eco Engineering here with our thorough balance sheet health report.
- Examine Koh Brothers Eco Engineering's past performance report to understand how it has performed in prior years.
China Oriental Group (SEHK:581)
Simply Wall St Financial Health Rating: ★★★★★☆
Overview: China Oriental Group Company Limited manufactures and sells iron and steel products for downstream steel manufacturers in the People’s Republic of China, with a market cap of approximately HK$3.80 billion.
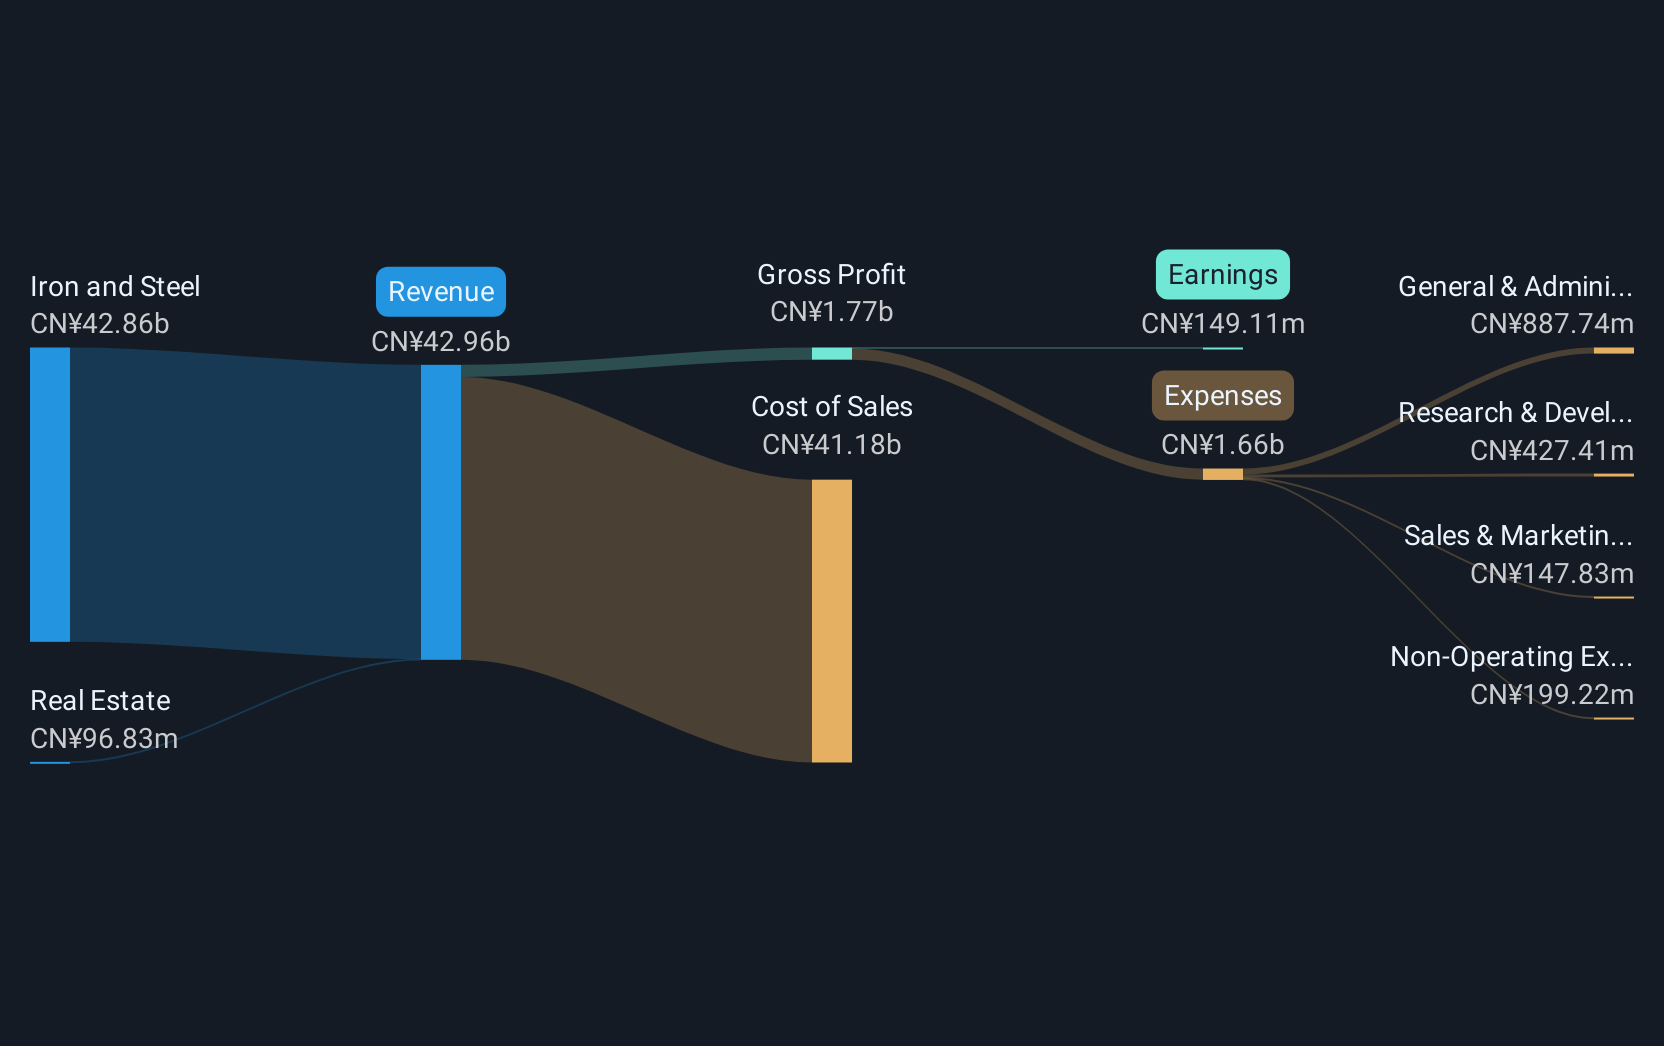
Operations: The company's revenue is primarily derived from its Iron and Steel segment, which generated CN¥38.70 billion, while its Real Estate segment contributed CN¥69.84 million.
Market Cap: HK$3.8B
China Oriental Group has shown a modest improvement in net profit margins, rising to 0.7% from 0.6% last year, despite earnings growth lagging behind the broader Metals and Mining industry. The company's debt-to-equity ratio has decreased over five years, indicating improved financial health, yet its operating cash flow inadequately covers its debt obligations. Recent agreements with NEMM Upstream JV for operational support and property leasing services are expected to generate additional revenue streams through 2028. However, the dividend yield of 6.84% is not well-supported by free cash flows, highlighting potential sustainability concerns for investors seeking income stability.
- Jump into the full analysis health report here for a deeper understanding of China Oriental Group.
- Assess China Oriental Group's previous results with our detailed historical performance reports.
Nanfang Pump Industry (SZSE:300145)
Simply Wall St Financial Health Rating: ★★★★★★
Overview: Nanfang Pump Industry Co., Ltd. is involved in the research, design, development, production, and sale of pump products both in China and internationally, with a market capitalization of approximately CN¥9.52 billion.
Operations: Nanfang Pump Industry Co., Ltd. does not report specific revenue segments, focusing instead on the comprehensive production and sale of pump products domestically and abroad.
Market Cap: CN¥9.52B
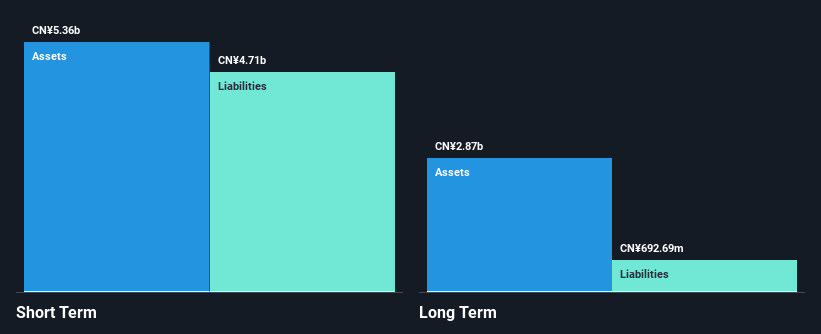
Nanfang Pump Industry has demonstrated financial stability with a satisfactory net debt to equity ratio of 26.4% and earnings growth of 14.1% over the past year, surpassing the Machinery industry's growth rate. The company's seasoned management team and board contribute to its strategic direction, while its short-term assets (CN¥5.3 billion) comfortably cover both short-term and long-term liabilities. Despite a low return on equity at 9.5%, Nanfang's price-to-earnings ratio of 37.4x is below the market average, suggesting potential value for investors seeking exposure in this sector without significant shareholder dilution concerns recently noted in company bylaws amendments.
- Click to explore a detailed breakdown of our findings in Nanfang Pump Industry's financial health report.
- Review our growth performance report to gain insights into Nanfang Pump Industry's future.
Taking Advantage
- Access the full spectrum of 1,051 Asian Penny Stocks by clicking on this link.
- Want To Explore Some Alternatives? We've found 8 US stocks that are forecast to pay a dividend yeild of over 6% next year. See the full list for free.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com