
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Will Board Appointment Change Pool (POOL) Narrative
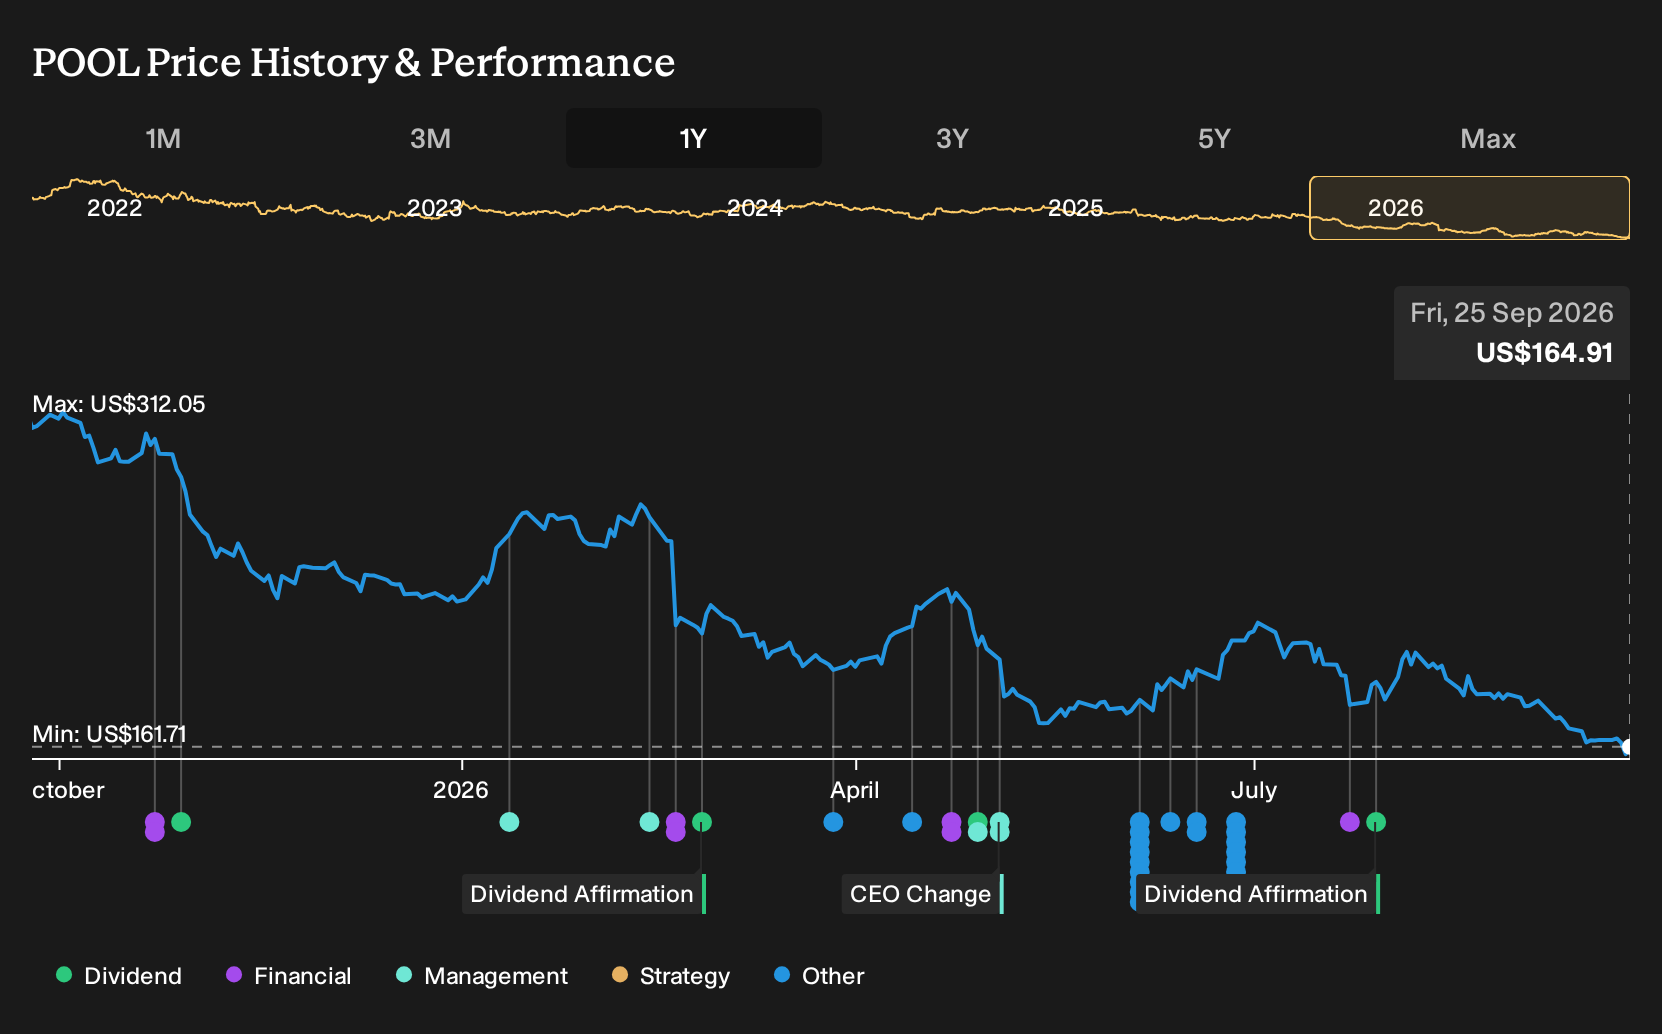
- Pool Corporation recently appointed Jean-Marc Germain, former Chief Executive Officer of Constellium SE and current special advisor to its board, as a director, with his term running from September 30, 2026, until the 2027 annual meeting of shareholders.
- Germain’s long history running global industrial businesses and serving on other public company boards introduces fresh operating experience that could influence how Pool addresses cost pressure, digital execution and product mix decisions.
- We will monitor how Pool's investment narrative evolves as the board adds Jean-Marc Germain, whose industrial background may affect execution priorities.
Pool Investment Narrative Recap
To own Pool, you need to be comfortable with a business that leans heavily on a large, recurring maintenance stream, while discretionary projects remain under pressure from high interest rates and softer housing turnover. The big near term swing factor is whether POOL360 adoption and private label mix keep offsetting freight and customer mix headwinds.
The most important risk is that weakness in new pool construction, remodeling and Horizon irrigation persists, which could keep volume and gross margin under strain. Jean Marc Germain joining the board does not change that operating backdrop in the short term, although his industrial experience may shape how Pool executes on cost and capital decisions.
The appointment of Jean Marc Germain, with his long tenure running global industrial groups and current role on GrafTech’s board, is the governance development that ties most directly into Pool’s execution story. His background in complex supply chains and manufacturing could be relevant as Pool works through freight costs, mix shifts and digital fulfillment.
For you as a shareholder, the practical question is whether this extra industrial experience helps Pool make cleaner trade offs between growth investments like POOL360, mix in higher margin proprietary products and balance sheet discipline, given the firm’s higher debt levels. That matters because the key catalyst remains execution on recurring revenue, digital tools and mix, while the main risk is prolonged pressure in construction linked categories.
Pool's analyst narrative points to revenues of US$5.9b and earnings of US$464.9m by 2029. This implies forecast revenue growth of 3.3% per year and an earnings increase of about US$67m from current earnings of US$397.8m.
Uncover why Pool's fair value indicates a 32% potential upside to its current price that could narrow quickly.
Exploring Other Perspectives
Some of the most optimistic analysts focus on distribution capacity as the big swing factor for Pool. Before this board news, the bullish camp was working off revenue projections of about US$6.1b and earnings near US$492.1m by 2029, which is meaningfully higher than consensus. That gap shows how widely views can differ, so treat Germain’s appointment as a new data point and explore several possible narratives instead of relying on just one set of numbers.
Explore 2 other Pool fair value estimates, including one that suggests as much as 63% upside from the current price.
The Verdict Is Yours
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Pool research is our analysis highlighting 4 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Pool. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Pool's overall financial health at a glance.
Looking for more investment ideas beyond Pool?
Once you have a view on Pool, it can help to compare it with other companies that fit different risk and income profiles using the Simply Wall St Screener.
- For investors willing to take on higher risk in search of outsized moves, scan through 6 elite penny stocks with strong financials that already show solid financial footing.
- If your focus is long term compounding and balance sheet strength, sort through the list of solid balance sheet and fundamentals (24 results) that may better match a quality first approach.
- For those who care most about cash returns, review the 8 dividend fortresses that concentrate on income potential backed by robust fundamentals.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com