
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Did New AI Server Launch Just Shift Fujitsu's (TSE:6702) Investment Narrative?
- Fujitsu announced in September 2026 that it will start global sales of its Japan-designed FUJITSU-MONAKA CPU and the made-in-Japan MONAKA Server from November 2026, targeting cloud and data center operators, enterprises, and HPC and academic users in Japan and Europe.
- The MONAKA platform highlights sovereign AI infrastructure with domestic manufacturing, high power efficiency, and space-saving design. This directly speaks to data center cost pressures, energy constraints, and governments’ focus on supply chain traceability and national security.
- We will now look at how Fujitsu's investment narrative is affected by the sovereign AI focused MONAKA launch and its infrastructure ambitions.
Scan how other data center and AI infrastructure plays are positioning for the same pressures driving Fujitsu's MONAKA launch by reviewing the hand picked 85 AI infrastructure stocks shaping this build out.
Fujitsu Investment Narrative Recap
To own Fujitsu, you need to believe the services pivot in digital transformation, AI and modernization can keep offsetting pressures in legacy hardware and slower international regions. The MONAKA launch speaks directly to that shift into higher value infrastructure and data center workloads. The key near term catalyst still sits in execution on modernization and Uvance demand rather than a single product cycle.
The biggest risk remains concentration in Japan and dependence on large, lumpy public and enterprise contracts, which can make earnings choppy as budgets move. If international revenue softness in Europe or APAC persists or accelerates, this product news alone probably does not change that picture in a material way.
The most relevant announcement for this story is the MONAKA CPU and MONAKA Server roll out from November 2026. That offering lines up with rising AI workload needs, power constraints and government focus on sovereign infrastructure in Japan and Europe. It also leans on Fujitsu’s existing processor and server know how rather than pushing the group into an entirely new field.
Execution risk is still real. Management needs to get volume, pricing and supply right while integrating these servers into a broader services and data center offering, not just chasing one off hardware deals. For investors watching catalysts, early adoption by cloud or HPC customers and how MONAKA links into Uvance and long term service contracts may matter more than headline performance metrics.
What The MONAKA Launch Means For Fujitsu's Forecasts
Fujitsu's narrative projects ¥3,927.8b revenue and ¥423.4b earnings by 2029. This implies 3.6% yearly revenue growth and an earnings increase of about ¥105.6b from ¥317.8b today.
Uncover why Fujitsu's fair value indicates a 20% potential upside to its current price before the market closes the discount.
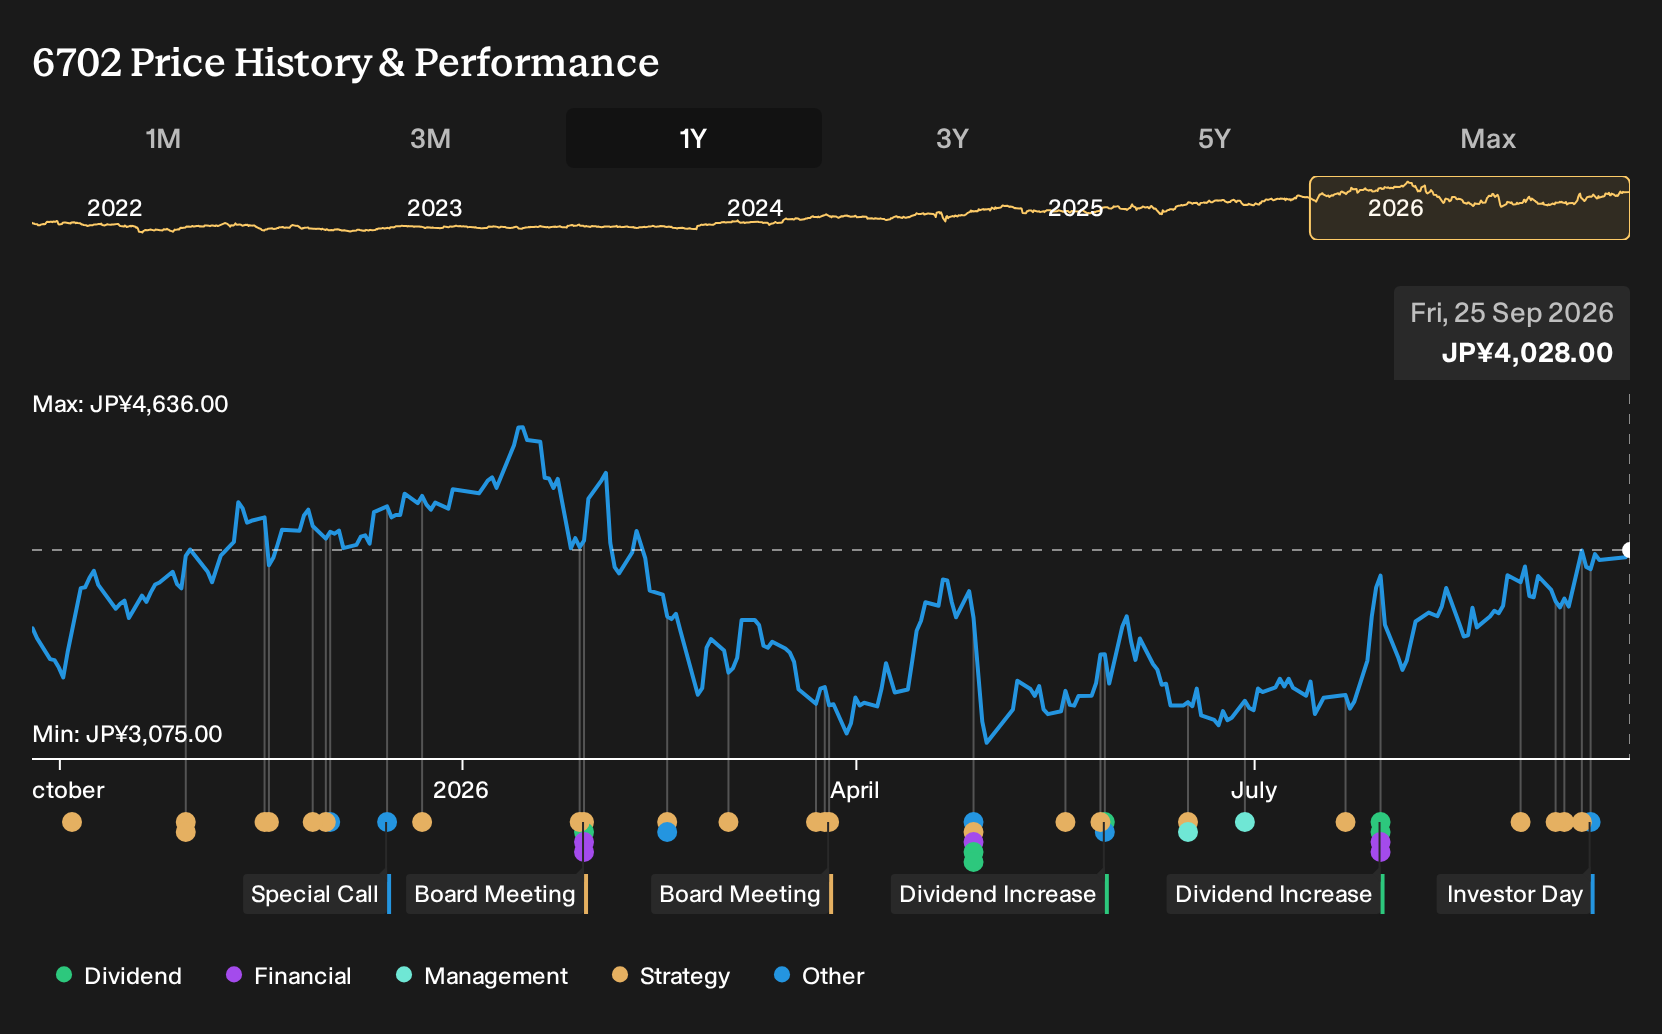
Exploring Other Perspectives
One alternate take on Fujitsu leans hard into competition risk. The most cautious analysts were only assuming ¥3,651.5b in revenue and ¥318.5b in earnings by 2029, with just 1.4% annual top line growth. That is far more downbeat than consensus. You can treat the MONAKA news as a fresh reason to compare those viewpoints.
Explore 2 other Fujitsu fair value estimates, including one that suggests it could be worth just ¥4,729.
Reach Your Own Conclusion
Disagree with existing narratives? Extraordinary investment outcomes are rarely achieved by following the herd, so trust your own analysis.
- A great starting point for your Fujitsu research is our analysis highlighting 4 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Fujitsu. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easier to evaluate Fujitsu's overall financial health at a glance.
Looking For More Ideas Beyond Fujitsu?
If the Fujitsu story has sharpened your thinking about AI infrastructure and long term compounding, it can help to line it up against other opportunities on your radar. The Simply Wall St Screener lets you quickly filter for different return profiles, risk levels and balance sheet setups so you can build a watchlist that genuinely fits your own playbook.
- If you want potential upside with less financial fragility, focus on companies with stronger balance sheets by scanning the list of solid balance sheet and fundamentals (22 results) that can help underpin resilience when conditions get tougher.
- If your priority is capital preservation and smoother ride potential, start with the 21 resilient stocks with low risk scores that filters for businesses scoring well on stability and risk checks.
- If you are hunting for ideas that the market may not be fully pricing yet, check the 74 high quality undiscovered gems that surface smaller, high quality businesses with strong fundamentals.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com