
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
COSCO SHIPPING Development (SEHK:2866) Heads Into Earnings On A Cheap P E With Cash Flow Doubts
COSCO SHIPPING Development (SEHK:2866) heads into its H1 2026 earnings call on 23 September with investors weighing the recent share price pullback and the company’s mix of container manufacturing, leasing and financial investment activities.
Recent trading has been soft, with COSCO SHIPPING Development’s share price falling 2.79% in the last session and recording a 7-day share price return of down 5.43%. The year to date share price return is down 18.69%, while the 3-year total shareholder return is up 17.29%. This suggests that shorter term sentiment has cooled ahead of the H1 2026 call as investors reassess both growth prospects and risk around its container and leasing exposure at the current HK$0.87 level.
Scan how COSCO SHIPPING Development compares with other container, shipping and leasing peers by running the curated list of solid balance sheet and fundamentals (201 results)
Bulls point to COSCO SHIPPING Development’s container scale and leasing reach, while bears focus on the recent share price slide and value traps. Which case do the current valuation signals lean toward?
Preferred P/E of 6x for COSCO SHIPPING Development: Is it justified?
On simple earnings math, COSCO SHIPPING Development trades on a P/E of 6x at the last close of HK$0.87, which is below both the Hong Kong market and its Trade Distributors peer group.
The P/E ratio compares the current share price to earnings per share. For a container manufacturing and leasing group like COSCO SHIPPING Development, it gives a quick sense of how much investors are paying for each unit of profit in a sector where asset intensity and capital cycles matter a lot.
Against that backdrop, the stock screens as inexpensive. The current P/E of 6x sits below the Hong Kong market average of 10.7x and also below the Hong Kong Trade Distributors industry average of 11.5x. At the same time, earnings have declined by 6.9% over the past year and by 33.9% per year over the past 5 years, which suggests the market might be assigning a lower multiple because profit trends and a return on equity of 5.2% are relatively weak.
Relative to peers, the discount is clear. COSCO SHIPPING Development is described as good value both versus the Hong Kong market multiple and versus sector competitors that trade closer to 9.5x to 11.5x earnings. This points to investors potentially pricing in softer growth, lower profitability and risks such as interest coverage pressure and a 4.97% dividend that is not well covered by free cash flows.
See what the numbers say about this price — find out in our valuation breakdown.
Result: Price-to-earnings of 6x (UNDERVALUED)
Still, COSCO SHIPPING Development faces pressure from declining multi year earnings trends and a dividend that free cash flow coverage does not currently support comfortably.
Find out about the key risks to this COSCO SHIPPING Development narrative.
Another view on COSCO SHIPPING Development’s valuation
On cash flows, the picture flips. COSCO SHIPPING Development trades at HK$0.87, while our DCF model points to a future cash flow value of HK$0.23, which screens as overvalued. That raises a simple question for investors: Are current earnings cheap, or is the cash flow risk being underpriced?
Look into how the SWS DCF model arrives at its fair value.
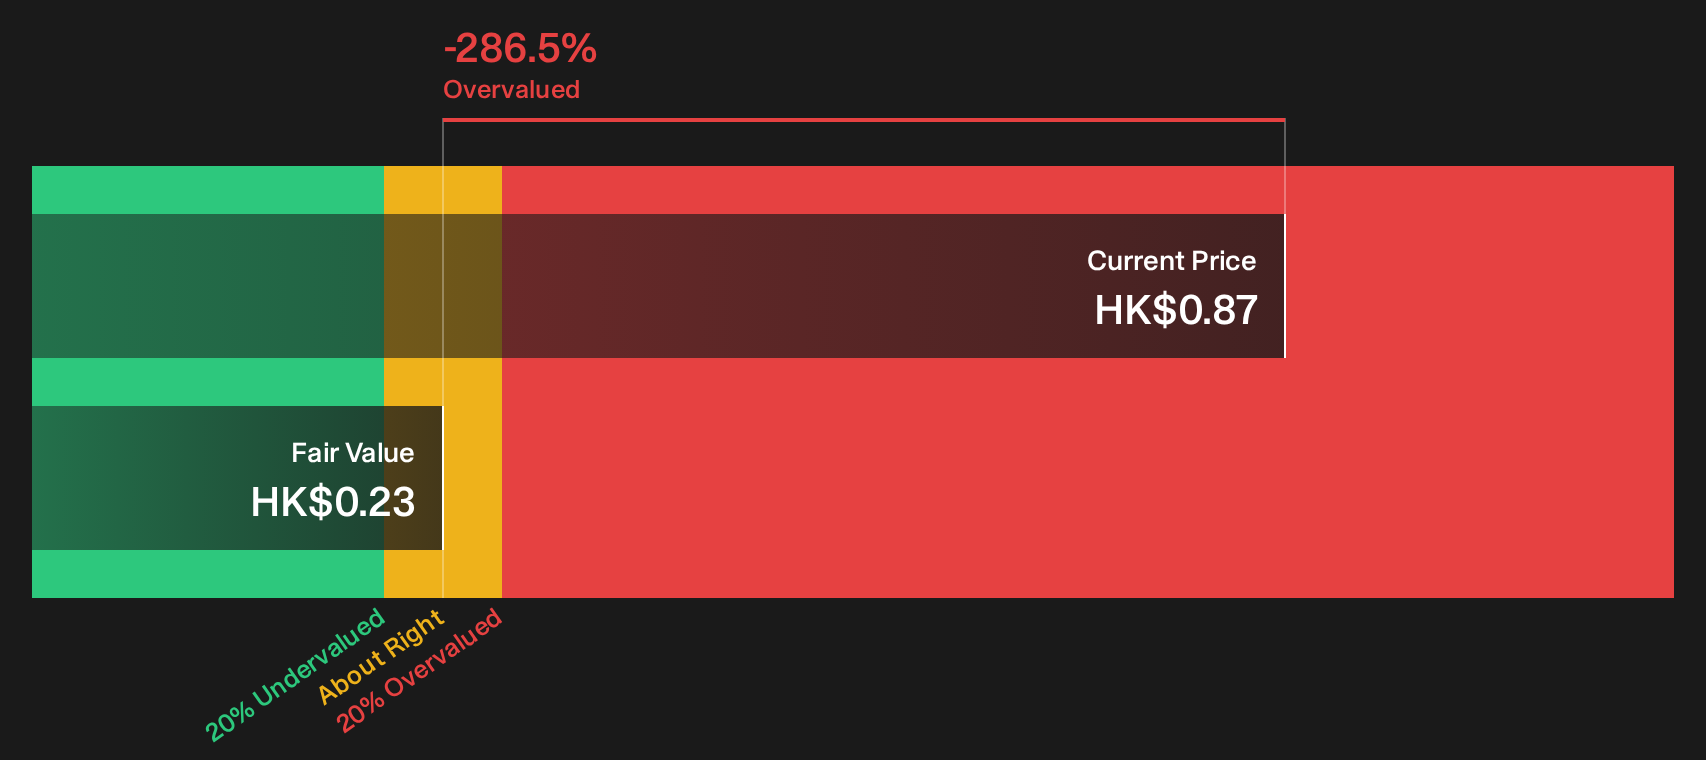
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out COSCO SHIPPING Development for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 184 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Sentiment on COSCO SHIPPING Development is split, which makes this a good moment to move quickly, review the underlying data, and reach your own conclusion by weighing the 1 key reward and 3 important warning signs.
Looking for more investment ideas beyond COSCO SHIPPING Development?
If COSCO SHIPPING Development has you thinking more carefully about value and risk, use that momentum and cast a wider net before the next market move passes you by.
- Target resilience first and scan a curated set of 226 resilient stocks with low risk scores that aim to keep portfolio swings in check when conditions turn rough.
- Hunt for better value and compare COSCO SHIPPING Development with a broader pool of 184 high quality undervalued stocks that pair solid fundamentals with discounted prices.
- Strengthen potential income streams and line up a watchlist of 159 dividend fortresses that focus on higher yields backed by more robust financials.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com