
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Greatland Resources And 2 Australian Undervalued Stocks To Watch
Australian bond yields have climbed toward 5.5% on the 10 year government bond, lifting discount rates and putting pressure on share valuations. That kind of move can leave cash rich businesses trading below what their future cash flows suggest they are worth. This article walks through three Australian stocks that currently appear underpriced on a discounted cash flow basis, and explains why that gap may matter for patient investors.
The three stocks in this piece are a sample set, and the full screen on Simply Wall St has surfaced 3 more companies with equally compelling cash flow stories that are not covered here. To identify and analyze those extra ideas alongside this starting list, head straight to the Undervalued Stocks Based On Cash Flows screener.
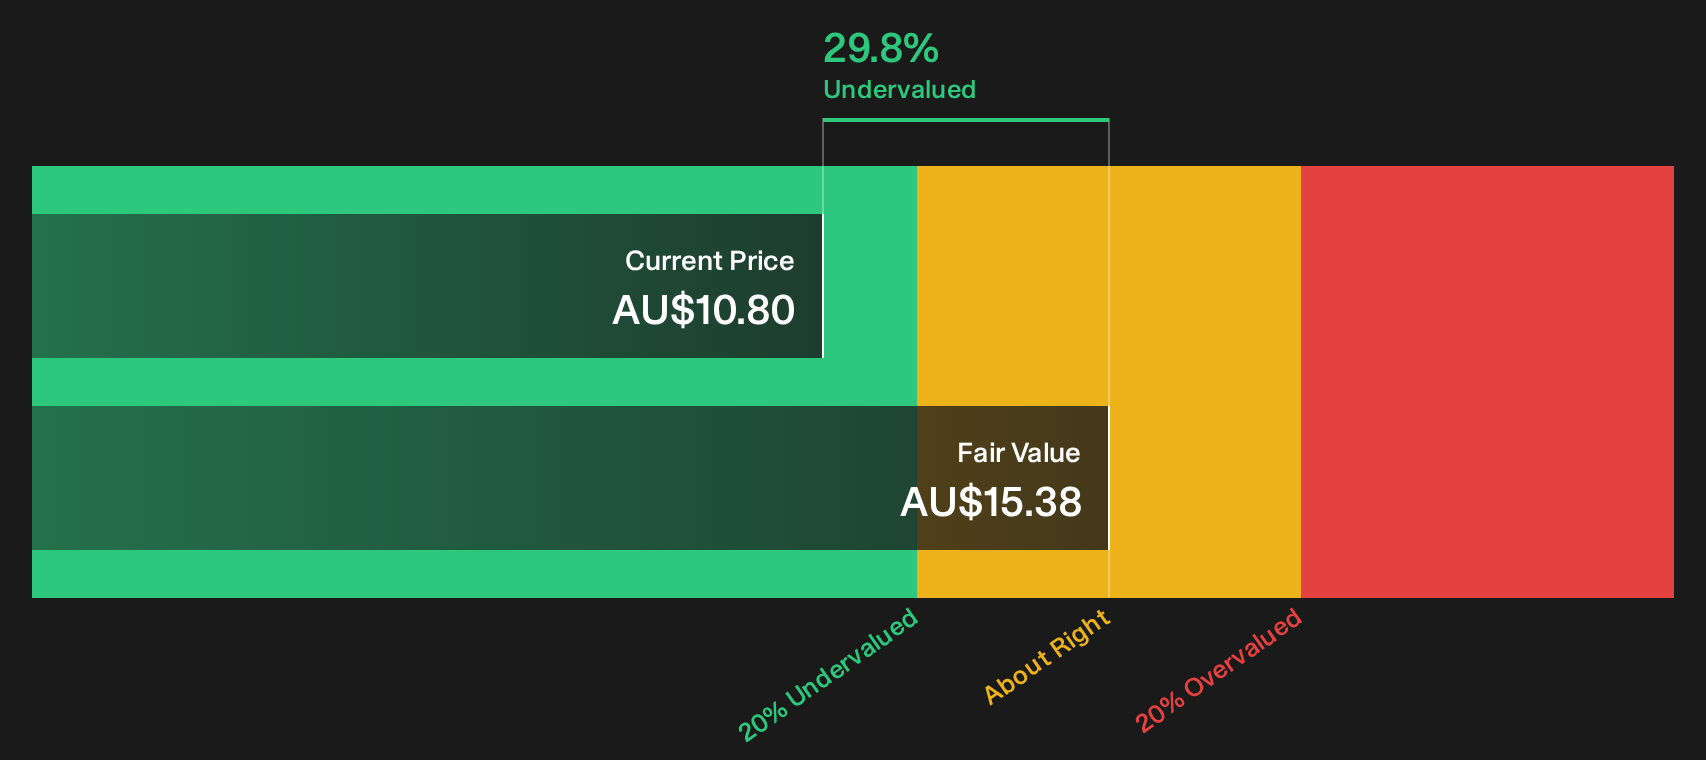
Greatland Resources (ASX:GGP)
Overview: Greatland Resources is a gold and copper miner whose Havieron project in Western Australia anchors its long term cash flow potential.
Operations: Greatland Resources currently reports A$2.26b in revenue from its Telfer Havieron segment, reflecting a tightly focused production base.
Market Cap: A$7.26b
Greatland Resources matters for this cash flow focused screen because Havieron is shifting the business story from hopeful exploration to producing asset, where the timing and quality of those future cash streams start to really drive valuation.
"The primary driver of Greatland’s future is the gold price. As a single asset developer moving toward production, it offers significant operational leverage to gold."
What happens when one key assumption in that future cash flow story moves just a little can have a big impact on investor outcomes.
That kind of sensitivity is exactly why reading the full narrative for Greatland Resources can help you see how gold price swings and project timing might reshape Greatland Resources’ valuation story.
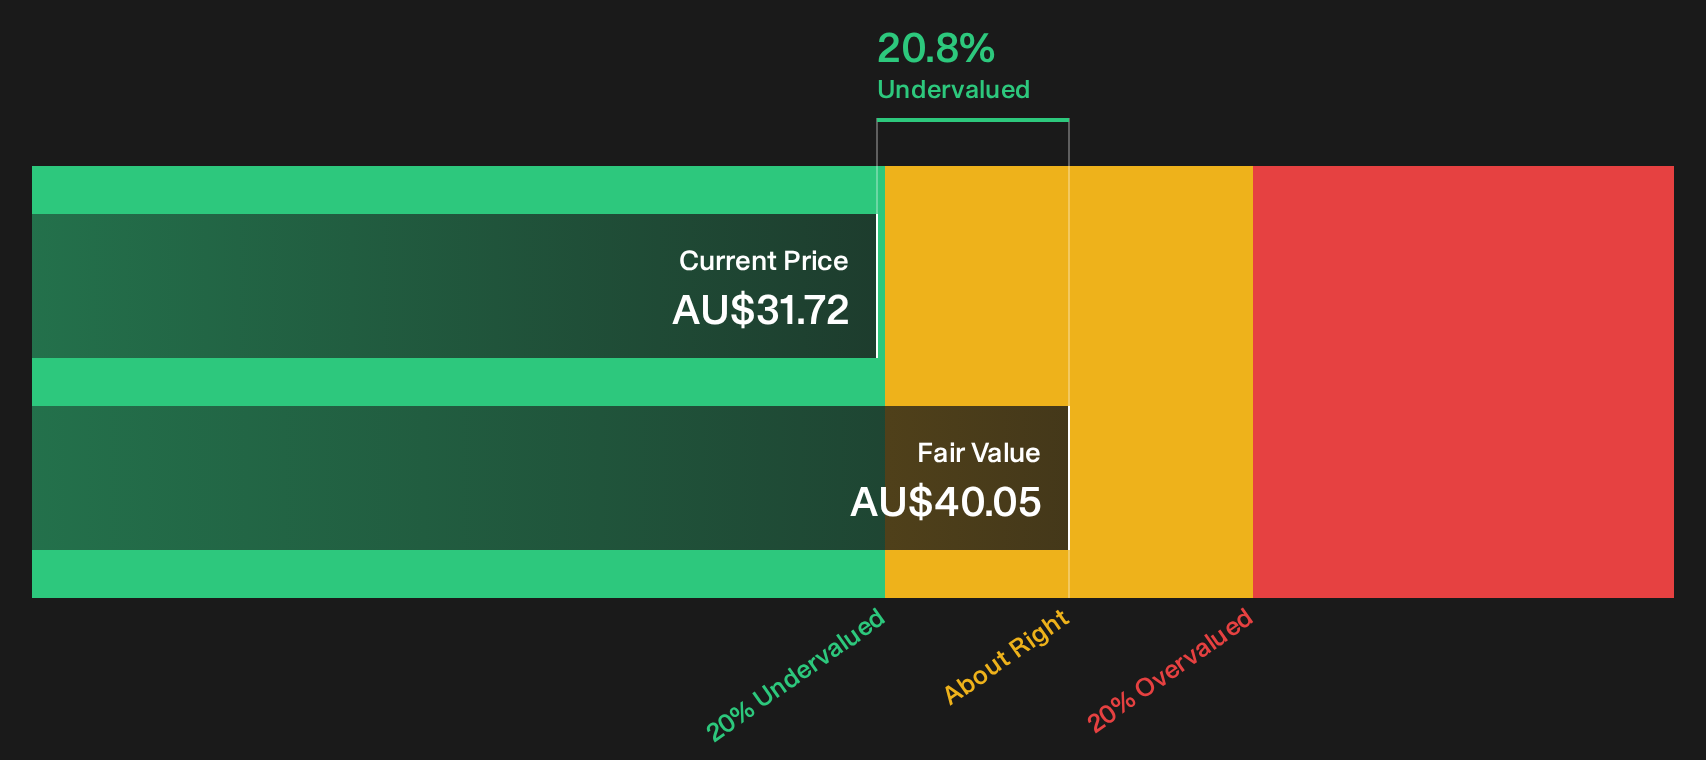
Woodside Energy Group (ASX:WDS)
Overview: Woodside Energy Group is a Perth based hydrocarbon producer focused on LNG projects, complemented by oil, gas and emerging low carbon activities.
Operations: Woodside generates about US$7.3b from Australian operations, US$4.6b from international projects and US$1.9b from marketing activities.
Market Cap: A$60.3b
Woodside Energy Group matters for this cash flow screen because its LNG projects feed long term contracts that shape discounted cash flow valuations more than headline production volumes.
"Investor optimism appears driven by robust expectations for long-term demand growth in Asian and emerging markets, with Woodside's global LNG expansion (Louisiana, Scarborough) positioned to capture this growth; however, these assumptions may underestimate the potential for rapid decarbonization policies or renewable adoption, which could affect future revenue and volume growth if LNG demand softens in key markets."
What happens if one quiet shift in future energy policy changes the pricing power that underpins Woodside Energy Group’s LNG margins?
If that question is on your mind, the full narrative for Woodside Energy Group shows how shifting policy, pricing power and project timing could be quietly reshaping Woodside Energy Group’s opportunity set.
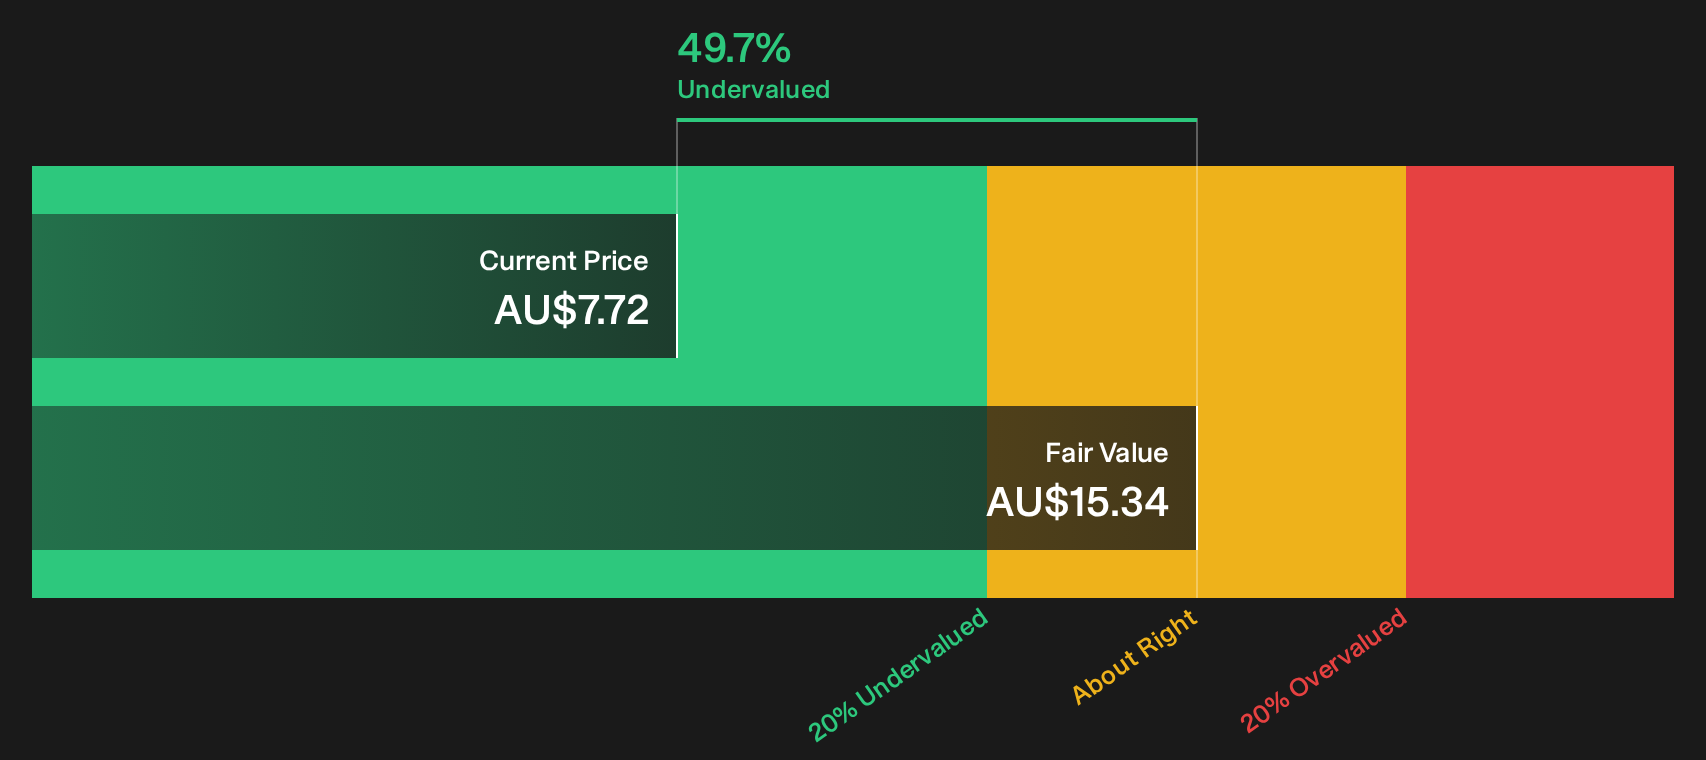
Regis Resources (ASX:RRL)
Overview: Regis Resources is an Australian gold producer whose Duketon and other operating mines convert mined ounces into cash flow from bullion sales.
Operations: Regis Resources reports A$1.45b from Duketon and A$897 million from Tropicana, with all A$2.35b in revenue earned in Australia.
Market Cap: A$5.8b
Regis Resources is relevant for this cash-flow focused screen because its producing gold projects feed directly into discounted cash flow models rather than distant exploration hopes.
"Regulatory and environmental barriers are stifling new mine supply globally, increasing the strategic value of established, expandable operations like those of Regis, supporting a long-term upward shift in realized gold prices and offering durable revenue and margin expansion for existing shareholders."
The extent to which potential value appears in margins may depend heavily on how even a single pressure on future project spending ultimately evolves.
If that pressure is what you are weighing, the full narrative for Regis Resources outlines how Regis Resources’ cash generation, project pipeline and risk profile could be subtly shifting expectations.
Curious About What You Might Be Missing?
Fresh opportunities move fast while valuations, momentum and sentiment keep shifting. Spot potential breakouts before the crowd, while it matters and while prices are still dropping or flying. Get in early.
- Spot potential cash generative compounders before headlines catch up by scanning the 4 high quality undervalued stocks curated from businesses with earnings support and balance sheets that can carry a long runway.
- Hunt for potential income workhorses that might keep portfolios steadier through cycles by screening the 3 dividend fortresses built around yield plus balance sheet strength.
- Track emerging themes that could move from fringe to front page by running the 20 cryptocurrency and blockchain stocks focused on businesses tied to digital asset infrastructure and adoption.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com