
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Here's What We Like About R Systems International's (NSE:RSYSTEMS) Upcoming Dividend
It looks like R Systems International Limited (NSE:RSYSTEMS) is about to go ex-dividend in the next 2 days. The ex-dividend date generally occurs two days before the record date, which is the day on which shareholders need to be on the company's books in order to receive a dividend. The ex-dividend date is important because any transaction on a stock needs to have been settled before the record date in order to be eligible for a dividend. Accordingly, R Systems International investors that purchase the stock on or after the 1st of October will not receive the dividend, which will be paid on the 24th of October.
The company's next dividend payment will be ₹8.00 per share, on the back of last year when the company paid a total of ₹6.00 to shareholders. Based on the last year's worth of payments, R Systems International has a trailing yield of 2.5% on the current stock price of ₹235.62. If you buy this business for its dividend, you should have an idea of whether R Systems International's dividend is reliable and sustainable. We need to see whether the dividend is covered by earnings and if it's growing.
If a company pays out more in dividends than it earned, then the dividend might become unsustainable - hardly an ideal situation. Fortunately R Systems International's payout ratio is modest, at just 37% of profit. A useful secondary check can be to evaluate whether R Systems International generated enough free cash flow to afford its dividend. What's good is that dividends were well covered by free cash flow, with the company paying out 25% of its cash flow last year.
It's positive to see that R Systems International's dividend is covered by both profits and cash flow, since this is generally a sign that the dividend is sustainable, and a lower payout ratio usually suggests a greater margin of safety before the dividend gets cut.
View our latest analysis for R Systems International
Click here to see the company's payout ratio, plus analyst estimates of its future dividends.
Have Earnings And Dividends Been Growing?
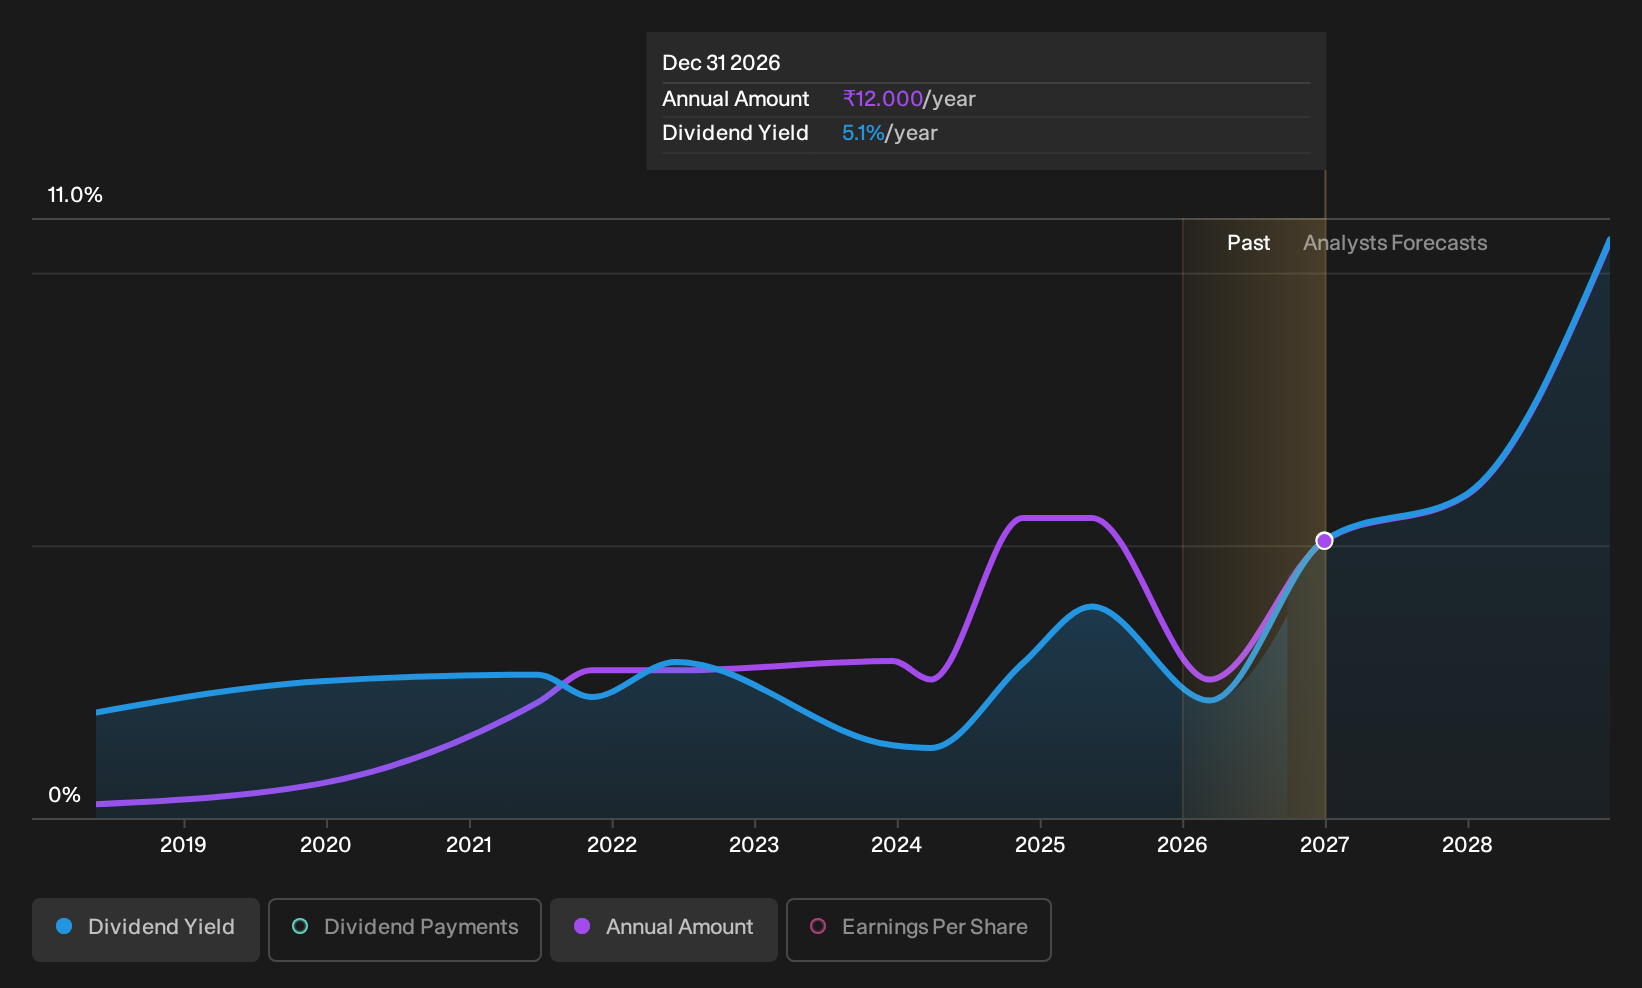
Companies with consistently growing earnings per share generally make the best dividend stocks, as they usually find it easier to grow dividends per share. If business enters a downturn and the dividend is cut, the company could see its value fall precipitously. For this reason, we're glad to see R Systems International's earnings per share have risen 19% per annum over the last five years. Earnings per share are growing rapidly and the company is keeping more than half of its earnings within the business; an attractive combination which could suggest the company is focused on reinvesting to grow earnings further. This will make it easier to fund future growth efforts and we think this is an attractive combination - plus the dividend can always be increased later.
The main way most investors will assess a company's dividend prospects is by checking the historical rate of dividend growth. R Systems International has delivered an average of 33% per year annual increase in its dividend, based on the past eight years of dividend payments. It's great to see earnings per share growing rapidly over several years, and dividends per share growing right along with it.
To Sum It Up
Has R Systems International got what it takes to maintain its dividend payments? It's great that R Systems International is growing earnings per share while simultaneously paying out a low percentage of both its earnings and cash flow. It's disappointing to see the dividend has been cut at least once in the past, but as things stand now, the low payout ratio suggests a conservative approach to dividends, which we like. R Systems International looks solid on this analysis overall, and we'd definitely consider investigating it more closely.
While it's tempting to invest in R Systems International for the dividends alone, you should always be mindful of the risks involved. Every company has risks, and we've spotted 1 warning sign for R Systems International you should know about.
Generally, we wouldn't recommend just buying the first dividend stock you see. Here's a curated list of interesting stocks that are strong dividend payers.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team (at) simplywallst.com.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.