
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Adobe (ADBE) Stock May Trade At A Discount On AI Partnership News
Adobe has seen its share price fall sharply in recent years, which puts fresh attention on whether the current valuation still lines up with what the business earns. With earnings in focus and sentiment shifting, the key issue for investors is how to read today’s price tag against the company’s profit engine.
- Over the past 5 years the stock has declined 59.2%, which puts a lot more weight on the question of how much earnings power the market is really paying for now.
- Recent moves into AI powered customer experience tools, such as the Jet2 partnership, can shape expectations for future earnings quality and pricing power as these products scale.
- There is a second opinion on Adobe worth weighing. See what analysts think Adobe's shares could be worth.
For investors, the debate is whether Adobe's current share price is properly grounded in the earnings it is generating today and is expected to produce in the future.
If you are weighing Adobe's earnings story against its recent share price slide, it can help to compare it with other software companies exposed to AI using 38 AI small caps.
Does Adobe Look Undervalued on Earnings?
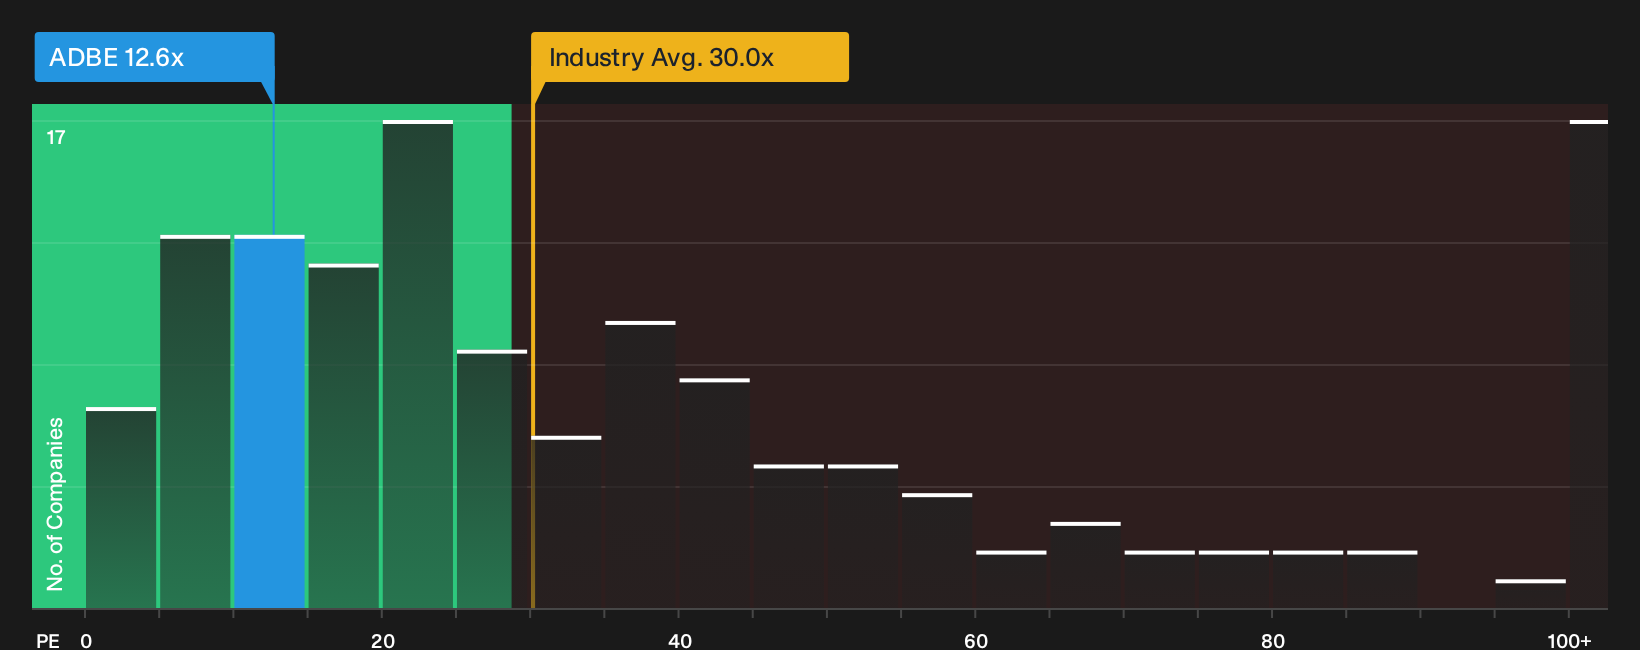
The P/E ratio suits Adobe because earnings remain the main anchor for how investors weigh its software and AI ambitions. On this basis, Adobe trades on a P/E of 12.6x, compared with a Software sector average of 30.0x and a peer group around 48.4x. That is a wide gap for a large, established platform that still leans heavily on recurring subscriptions.
The Fair Ratio framework, which adjusts for factors such as growth profile, profitability, scale and risk, points to a higher P/E than where Adobe trades today, so the stock screens as undervalued on this measure. Because the Jet2 partnership puts fresh attention on how Adobe can monetise agentic AI in real customer journeys, the current discount to this tailored benchmark provides a reference point to assess whether the market is underestimating that earnings stream. Explore the numbers behind Adobe's P/E valuation.
The Adobe Narrative: What Would Justify Today's Price?
Simply Wall St Narratives pick up where the P/E puzzle for Adobe leaves off. They spell out which paths for growth, margins and earnings would need to play out for the stock to be worth meaningfully more or less than it is today on the screen. Each narrative ties its number to a clear view on how Adobe's revenue mix, profitability and risk profile might evolve, which you can revisit as new information arrives on the Community page.
Community views on Adobe sit on opposite sides of the valuation fence, with one camp arguing the selloff has gone too far and the other calling it a value trap.
Bull case: 49% undervalued
"This system creates a "consumption-to-conversion flywheel." As professionals integrate AI into their daily workflows, their credit usage increases…"
Discover why this Narrative puts Adobe at 49% undervalued.
Bear case: 44% overvalued
"Adobe's investment in Firefly has caused great harm in the user community. It cannibalizes the user base…"
Explore why this Narrative puts Adobe at 44% overvalued.
One more angle on Adobe that could matter for you
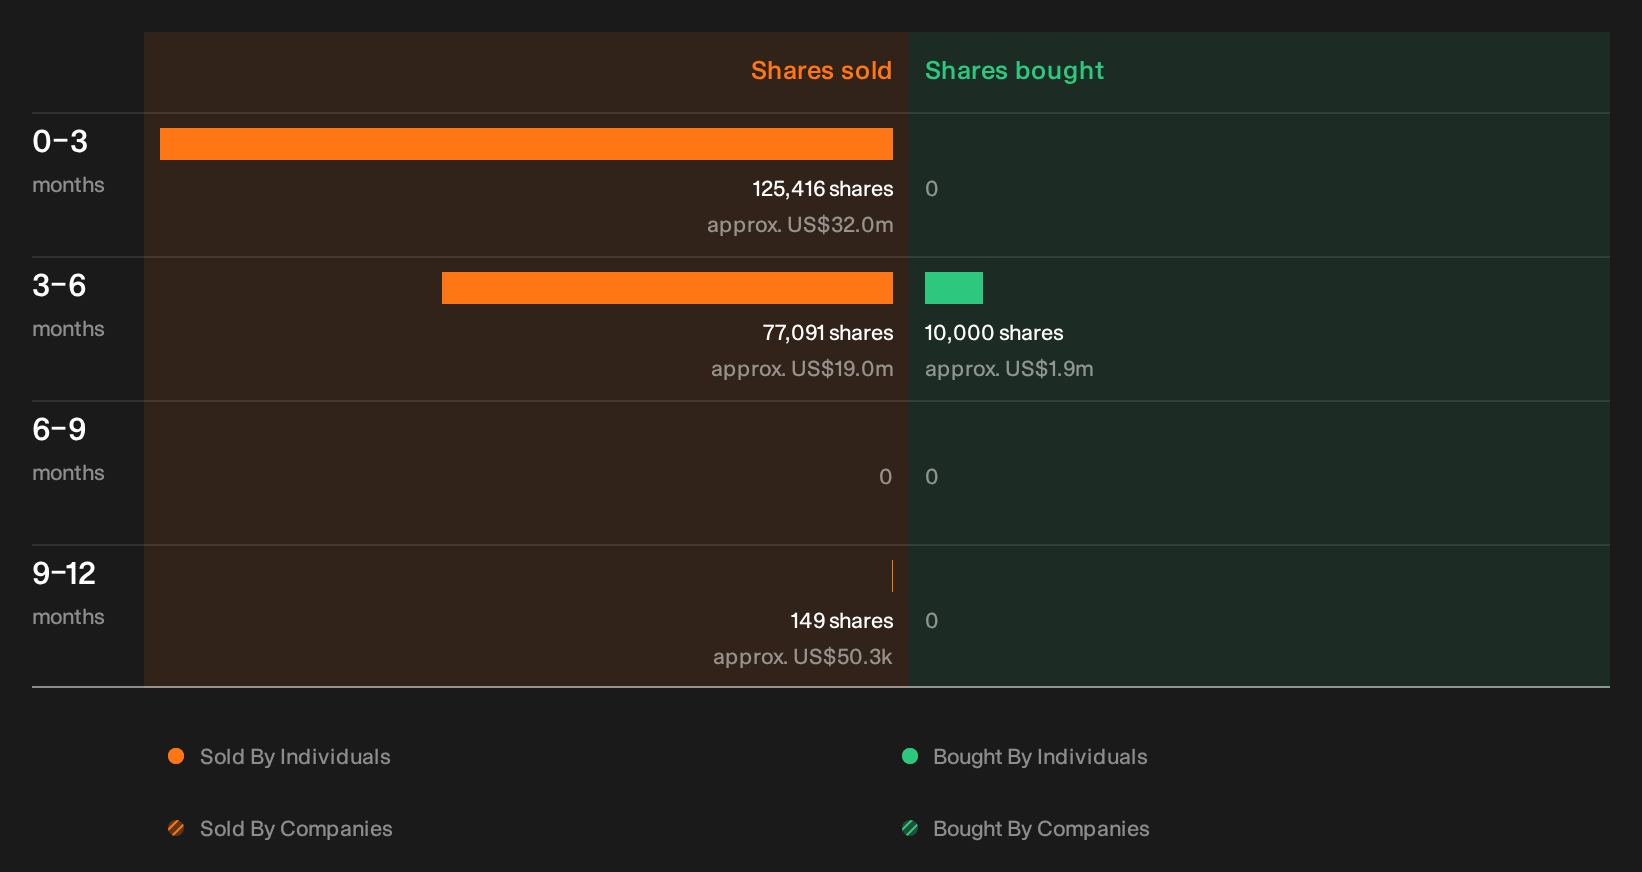
There is one final piece of the Adobe story that the valuation work does not cover. This is what recent share dealings by company insiders might be signaling about their own risk and reward trade off. See the recent insider selling flagged for Adobe.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com