
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
L&F Co., Ltd. (KRX:066970) About To Shift From Loss To Profit
L&F Co., Ltd. (KRX:066970) is possibly approaching a major achievement in its business, so we would like to shine some light on the company. L&F Co., Ltd. engages in the development and sale of electronic materials in Korea. The ₩4.3t market-cap company posted a loss in its most recent financial year of ₩534b and a latest trailing-twelve-month loss of ₩323b shrinking the gap between loss and breakeven. As path to profitability is the topic on L&F's investors mind, we've decided to gauge market sentiment. In this article, we will touch on the expectations for the company's growth and when analysts expect it to become profitable.
Consensus from 24 of the South Korean Electrical analysts is that L&F is on the verge of breakeven. They anticipate the company to incur a final loss in 2025, before generating positive profits of ₩41b in 2026. So, the company is predicted to breakeven approximately a year from now or less! We calculated the rate at which the company must grow to meet the consensus forecasts predicting breakeven within 12 months. It turns out an average annual growth rate of 98% is expected, which is rather optimistic! If this rate turns out to be too aggressive, the company may become profitable much later than analysts predict.
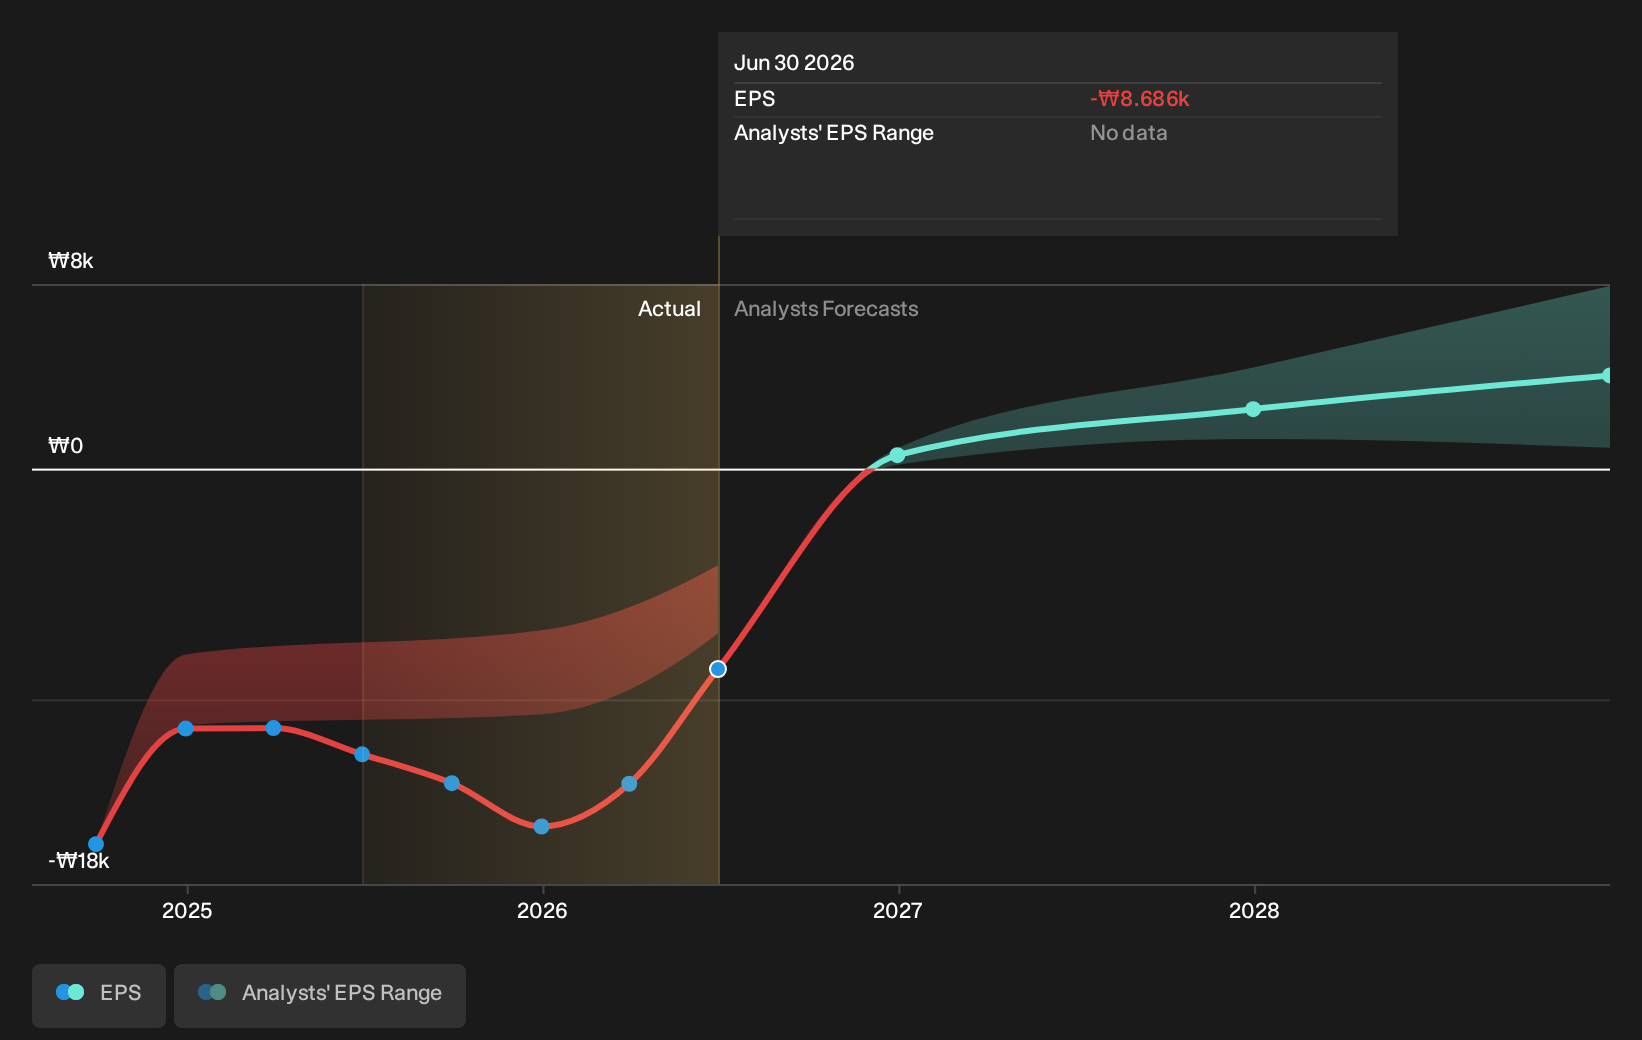
Underlying developments driving L&F's growth isn’t the focus of this broad overview, but, take into account that generally a high growth rate is not out of the ordinary, particularly when a company is in a period of investment.
Check out our latest analysis for L&F
One thing we would like to bring into light with L&F is its debt-to-equity ratio of over 2x. Generally, the rule of thumb is debt shouldn’t exceed 40% of your equity, and the company has considerably exceeded this. Note that a higher debt obligation increases the risk around investing in the loss-making company.
Next Steps:
There are key fundamentals of L&F which are not covered in this article, but we must stress again that this is merely a basic overview. For a more comprehensive look at L&F, take a look at L&F's company page on Simply Wall St. We've also put together a list of relevant aspects you should further examine:
- Valuation: What is L&F worth today? Has the future growth potential already been factored into the price? The intrinsic value infographic in our free research report helps visualize whether L&F is currently mispriced by the market.
- Management Team: An experienced management team on the helm increases our confidence in the business – take a look at who sits on L&F’s board and the CEO’s background.
- Other High-Performing Stocks: Are there other stocks that provide better prospects with proven track records? Explore our free list of these great stocks here.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team (at) simplywallst.com.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.