
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
TransDigm Group (TDG) Could Be 26% Undervalued On New Debt Focus
Why TransDigm Group’s New Debt Is Back in Focus
TransDigm Group (TDG) has just completed a US$3b secured bond issue and flagged another US$2.5b offering, putting its funding playbook and refinancing risk firmly back on investors' radar.
Recent trading has been choppy for TransDigm Group, with the share price down about 17.8% year to date and around 15.7% over 90 days. This comes even though the 3 year total shareholder return of roughly 54.9% and 5 year total shareholder return of about 105.7% still point to a strong longer term record.
The fresh US$3b bond issue and flagged US$2.5b raise now sit against that weaker recent share price return backdrop. This suggests investors are reassessing leverage and refinancing risk rather than the entire long run equity story.
Spot opportunities beyond TransDigm Group’s refinancing story by scanning 32 high quality undervalued stocks that couple solid fundamentals with balance sheets investors are currently rewarding.For TransDigm Group, the question now is whether the weaker share price reflects real concern about a heavily funded business model or a swing in mood around debt and regulation that could be out of step with valuation.
Most Popular Narrative: 26% Undervalued
On the most followed view, TransDigm Group’s fair value of $1,513.37 sits well above the last close at $1,116.20. This frames the recent refinancing within a story that still focuses on cash generation and aftermarket strength.
Analysts expect TransDigm Group to keep leaning on its proprietary, high margin aftermarket model, supported by recent commercial and defense revenue growth, raised 2026 guidance, and strong free cash flow.
See why 33 investors see TransDigm Group as 26% undervalued.
Result: Fair Value of $1,513.37 (UNDERVALUED)
Still, the TransDigm Group story can be knocked off course if regulators keep pushing back on defense focused acquisitions, or if right to repair rules erode aftermarket pricing power.
Find out about the key risks to this TransDigm Group narrative.
Another View: What Multiples Say About TransDigm Group
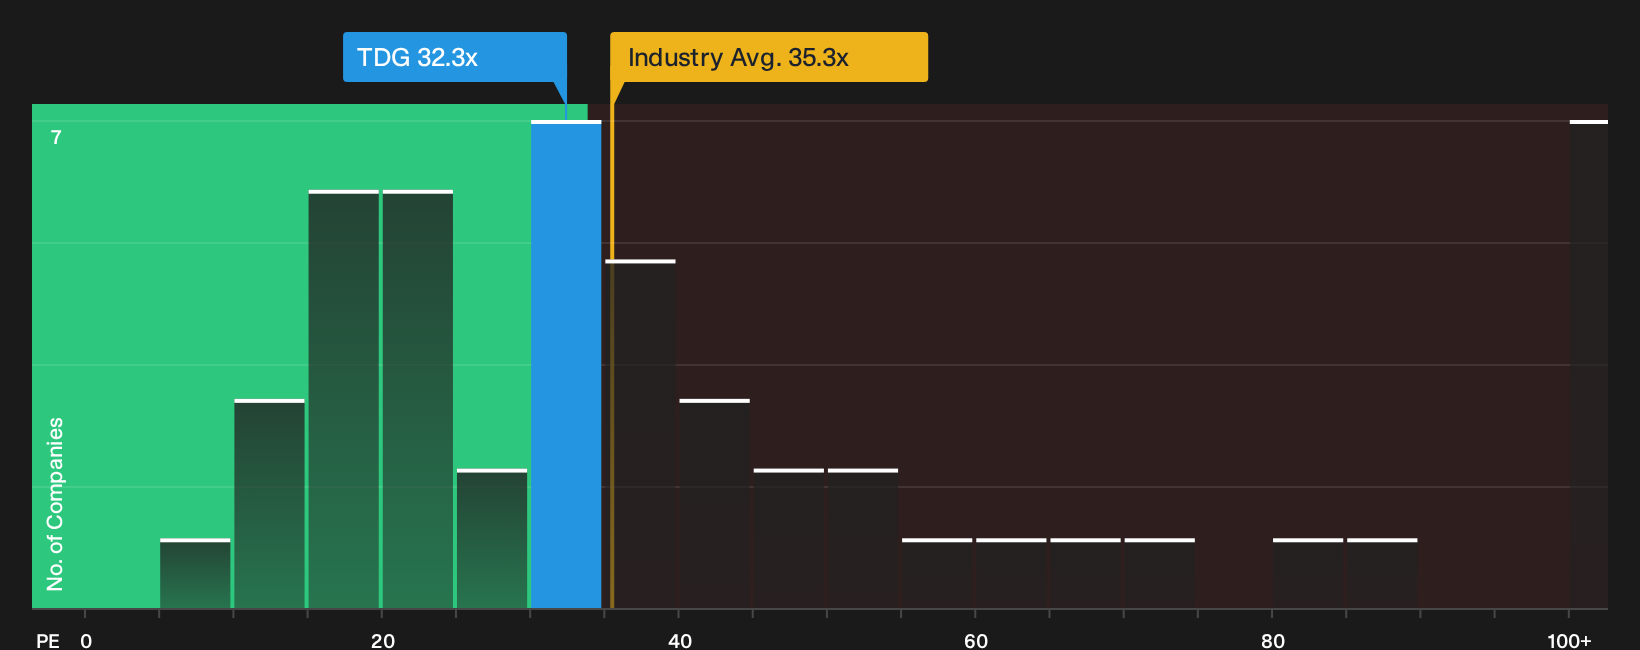
There is a clear gap between TransDigm Group’s discounted cash flow value and how the market is using earnings to price the stock. The current P/E of 32.3x sits above its own fair ratio of 31.5x and also above peer levels of 27.4x. That points to richer pricing on this measure and raises the question of how much good news is already reflected in the earnings multiple.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Sentiment around TransDigm Group is clearly mixed, with both risks and rewards on the table. Consider the 4 key rewards and 3 important warning signs alongside your own assessment of the numbers before making any decisions.
Looking for more investment ideas beyond TransDigm Group?
You do not need to stop with TransDigm Group. Use the Simply Wall Street Screener to surface fresh opportunities that fit the type of portfolio you want to build.
- Target steadier journeys by reviewing 30 resilient stocks with low risk scores that aim to limit surprises when markets turn choppy.
- Hunt for quality at a discount with 16 high quality undiscovered gems that many investors may not be watching yet.
- Anchor your watchlist with companies that combine resilience and strong finances through the list of solid balance sheet and fundamentals (24 results).
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com