
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Is COSCO SHIPPING Energy Transportation (SEHK:1138) Fully Valued Following Higher Tanker Rates?
Recent disruption at major oil chokepoints has pushed tanker freight rates higher, putting COSCO SHIPPING Energy Transportation (SEHK:1138) in focus as investors assess how tighter routes affect margins and future earnings sensitivity.
At a share price of HK$19.5, COSCO SHIPPING Energy Transportation has logged a 30 day share price return of 21.88% and a year to date share price gain of 101.65%. The 1 year total shareholder return of 134.74% points to strong momentum building around the stock.
Scan how COSCO SHIPPING Energy Transportation compares with other tanker exposed plays by reviewing our hand picked list of list of solid balance sheet and fundamentals (201 results).
COSCO SHIPPING Energy Transportation has already rewarded early holders after a sharp run, yet the freight backdrop and earnings link keep the door open to debate. Is most of the upside already priced in, or not?
Preferred P/E of 13.6x: Is it justified?
Valuation now leans against the recent price move, with COSCO SHIPPING Energy Transportation trading on a P/E of 13.6x while many peers sit lower on earnings multiples.
The P/E ratio compares the share price with earnings per share and, for a tanker and LNG carrier operator like COSCO SHIPPING Energy Transportation, it often reflects how the market weighs shipping cycle exposure against current profit strength. A higher multiple can suggest investors are comfortable paying more for each unit of earnings, or that they expect the current profit profile to hold up relative to sector swings.
Here, the stock is described as expensive versus both the broader Asian Oil and Gas group P/E of 11.9x and a peer average of 8.5x. It is also described as rich compared with an estimated fair P/E of 13.2x, which indicates the current pricing already leans above the level that some models suggest the market could move toward if sentiment cools.
Explore the SWS fair ratio for COSCO SHIPPING Energy Transportation.
Result: Price-to-earnings of 13.6x (OVERVALUED)
Still, COSCO SHIPPING Energy Transportation faces clear pressure points if tanker rates cool or if new vessel deliveries weigh on utilisation and day rates.
Find out about the key risks to this COSCO SHIPPING Energy Transportation narrative.
Another view on COSCO SHIPPING Energy Transportation’s value
Our DCF model paints a far harsher picture than the earnings multiple. At HK$19.5, COSCO SHIPPING Energy Transportation sits well above an estimated future cash flow value of HK$1.45. This points to a stock that screens as very expensive on this method. How comfortable are you with that disconnect?
Look into how the SWS DCF model arrives at its fair value.
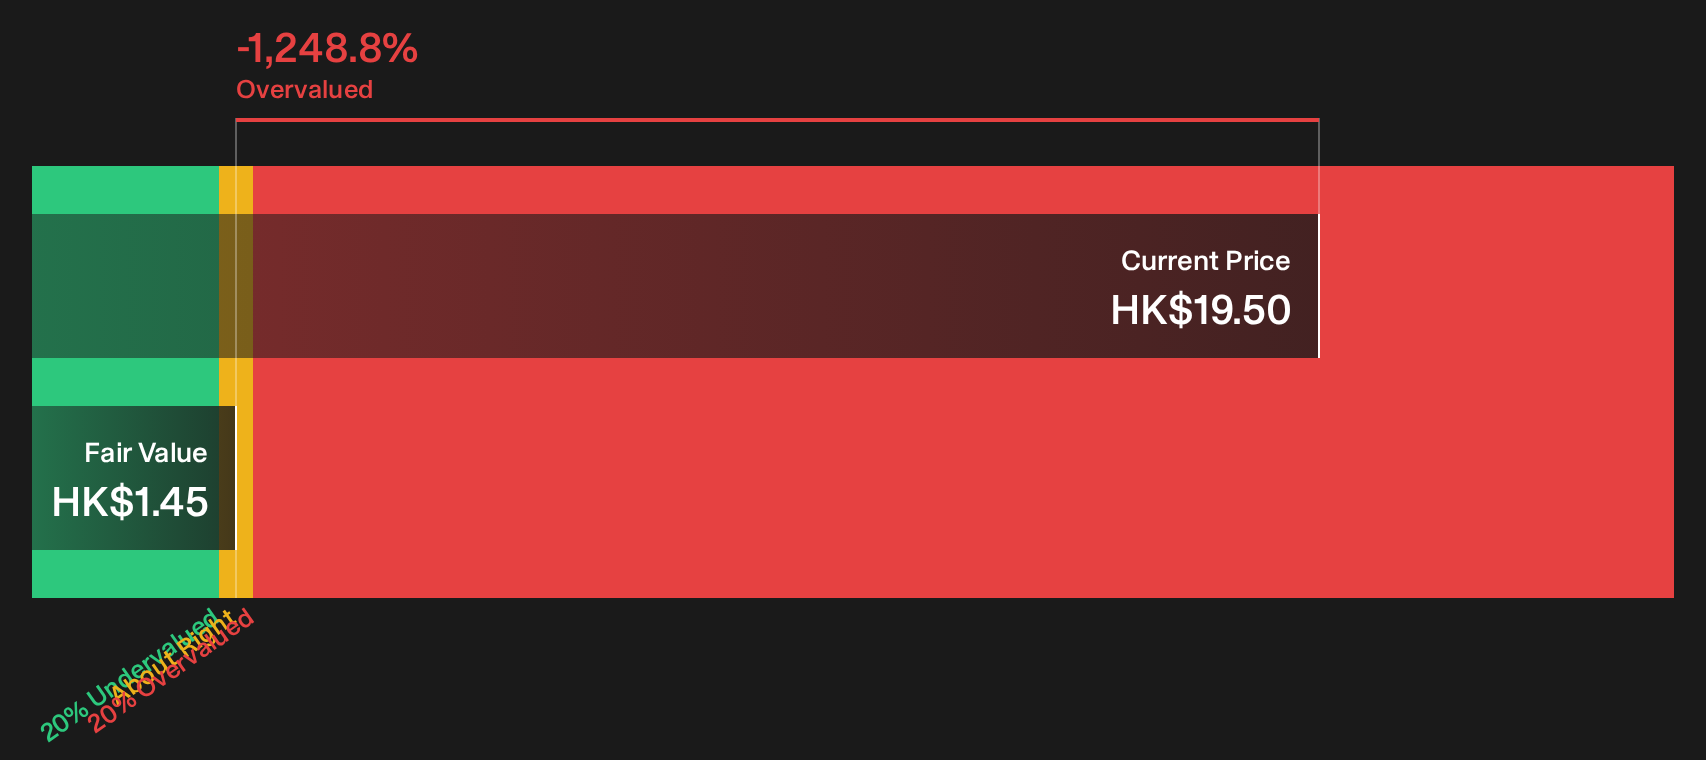
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out COSCO SHIPPING Energy Transportation for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 184 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
If sentiment around COSCO SHIPPING Energy Transportation feels stretched or conflicted, use that as a prompt to pull apart the numbers yourself and move quickly while the data is fresh. To weigh both the potential upside and the key concerns side by side, start with the 2 key rewards and 1 important warning sign.
Looking for more COSCO SHIPPING Energy Transportation sized ideas?
Do not stop with COSCO SHIPPING Energy Transportation. Use the same disciplined lens across a wider watchlist so you are not relying on a single theme.
- Target resilient balance sheets and steady fundamentals by reviewing our list of solid balance sheet and fundamentals (201 results).
- Hunt for quality trading at a discount and scan the 184 high quality undervalued stocks before momentum crowds the opportunity.
- Build income focused exposure and stress test payout strength through the 159 dividend fortresses while yields remain on your side.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com