
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
AI Agent Launch Could Be A Game Changer For Workiva Stock (WK)
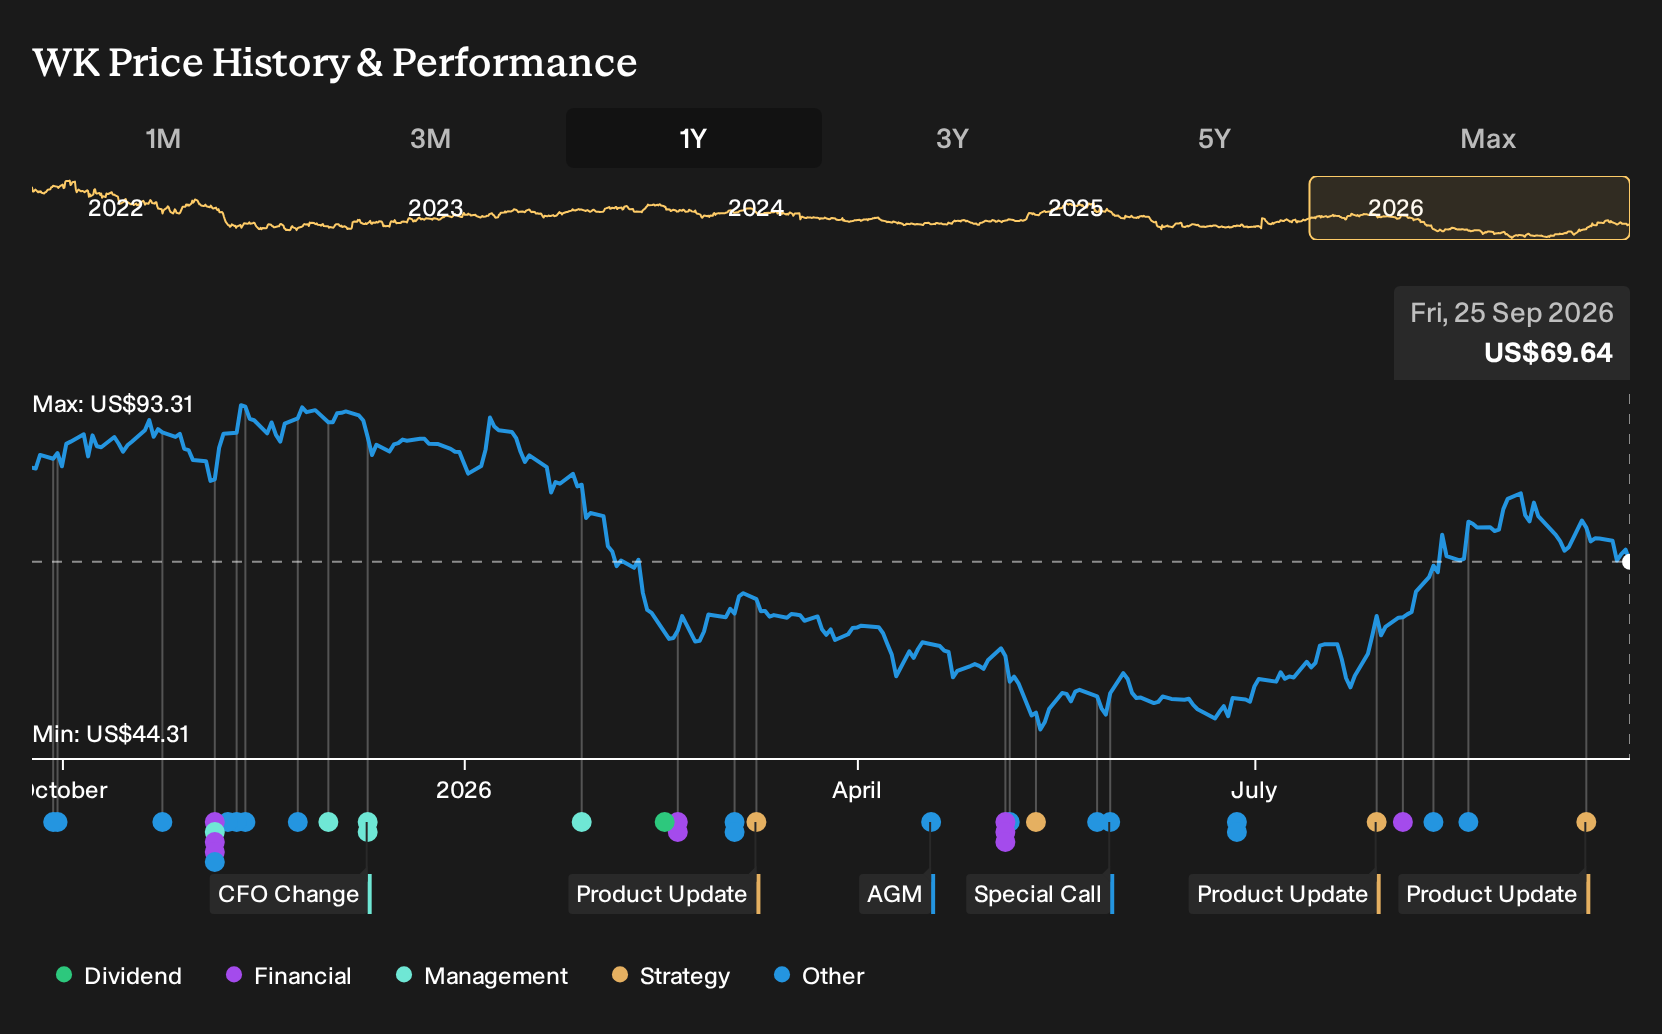
- Workiva held its Amplify 2026 conference in September, unveiling Agent Studio and multiple AI agent solutions that automate regulatory reporting, internal audit testing, and GRC workflows without requiring code.
- The push into AI agents aimed at complex, recurring compliance tasks signals a heavier focus on workflow automation across more reporting obligations within a single platform.
- We will now assess how Workiva's new Agent Studio capability may reshape the broader investment narrative around its multi-solution platform strategy.
Scan beyond Workiva and line up other compliance heavy software stocks by reviewing 85 AI infrastructure stocks while AI driven workflows are in the spotlight.
Workiva Investment Narrative Recap
For a shareholder in Workiva, the core belief is that a single connected reporting platform can keep winning larger, multi solution contracts across financial, sustainability, and compliance workflows. The short term focus sits on whether new AI features deepen usage with big enterprises and support the current shift toward higher value subscriptions without inflating costs too quickly.
The main near term risk still looks operational. Workiva carries high debt and negative shareholders equity, so heavy investment in AI agents needs to translate into efficient uptake, not just higher spend. Regulatory uncertainty in Europe, along with softer software budgets, could also slow expected demand for sustainability and compliance solutions.
The most relevant announcement here is Agent Studio. It lets customers build and deploy AI agents across Workiva’s platform to automate recurring regulatory, audit, and GRC work without code. That directly connects to the long term thesis around larger, multi solution deals because it gives finance and compliance teams more reasons to standardize work inside one environment.
Automated testing for internal audit and GRC matters for catalysts too. The ability to run evidence collection, sampling, and attribute testing with full traceability speaks to operational efficiency, a key piece of analyst expectations for margin improvement. Execution risk now shifts toward adoption quality. Enterprises need these agents to be accurate, governed, and reliable at scale.
Workiva's narrative projects US$1.5 billion revenue and US$153.9 million earnings by 2029. This assumes 16.3% yearly revenue growth and requires earnings to rise by about US$139.7 million from US$14.2 million today.
Discover why Workiva's fair value indicates a 13% potential upside to its current price that may not last much longer.
Exploring Other Perspectives
One alternate view puts the risk of slow AI adoption at the center. The most cautious analysts were already baking in only 15.4% yearly revenue growth and a P/E of 28.3x by 2029, even as they projected US$1.5b revenue and US$181.7 million earnings. That is a stricter bar, and it shows how widely opinions on Workiva can differ. Use this new Agent Studio news as a prompt to compare these more conservative assumptions with your own before deciding how you feel about the stock’s long term potential.
Explore another Workiva fair value estimate, including one that suggests it could be worth just $78.73.
Decide For Yourself
Disagree with existing narratives? Extraordinary investment outcomes rarely come from following the herd, so consider your own analysis.
- A great starting point for your Workiva research is our analysis highlighting 4 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for Workiva. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easier to evaluate Workiva's overall financial health at a glance.
Looking For More Investment Ideas Beyond Workiva?
If the Workiva story has you thinking more broadly about where compliance, automation, and durable cash flows might intersect next, it can help to line up a wider watchlist using the Simply Wall St Screener.
- For investors who want resilience first, focus on companies that score well on financial strength through the list of solid balance sheet and fundamentals (24 results).
- If potential mispricing is what interests you, scan a curated set of quality businesses trading below their estimated worth using the 32 high quality undervalued stocks.
- For those who care most about dependable income, filter for robust payout candidates with a track record of strong yields through the 8 dividend fortresses.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com