
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Delek US Holdings (DK) Prices $400 Million Notes On A Valuation That Still Looks Cheap
How Delek US Holdings’ New Convertible Notes Change The Picture
Delek US Holdings (DK) has priced a private offering of US$400 million in zero coupon convertible senior notes due 2031, a move that reshapes its mix of debt and potential future equity.
The company plans to use part of the proceeds to pay down its Term Loan Credit Facility. The rest is earmarked for general corporate purposes, while giving bondholders the option to convert into common stock at a premium.
Recent trading tells a mixed story. The share price is up 31.52% over 90 days and has a 127.80% year to date share price return, yet it fell 13.16% over the past week. This suggests some investors are reassessing risk as Delek US Holdings layers in new convertible debt.
Compare this move from Delek US Holdings with other refiners reshaping their balance sheets by scanning our hand picked list of list of solid balance sheet and fundamentals (24 results).
Delek US Holdings now has a larger refinancing tool in place and a share price that has run hard over the past year. The real tension is simple: Do those fundamentals and this new debt structure still justify today’s valuation?
Most Popular Narrative: 9.5% Undervalued
On the most followed view of Delek US Holdings, a fair value of $75 sits above the last close at $67.84. This frames this new convertible issue against a stock that screens as modestly cheap on that lens.
Substantial investment in logistics and midstream infrastructure, especially the ramp-up of growth projects at DKL, is expected to materially lower feedstock and transportation costs, while growing third-party business and unlocking new earnings streams, positively contributing to net margins and EBITDA.
See why 9 investors see Delek US Holdings as 10% undervalued.
Result: Fair Value of $75 (UNDERVALUED)
Still, Delek US Holdings leans heavily on traditional refining and carries meaningful debt. As a result, tougher regulation or weaker fuel demand could quickly undercut this valuation story.
Find out about the key risks to this Delek US Holdings narrative.
Another View On Delek US Holdings’ Valuation
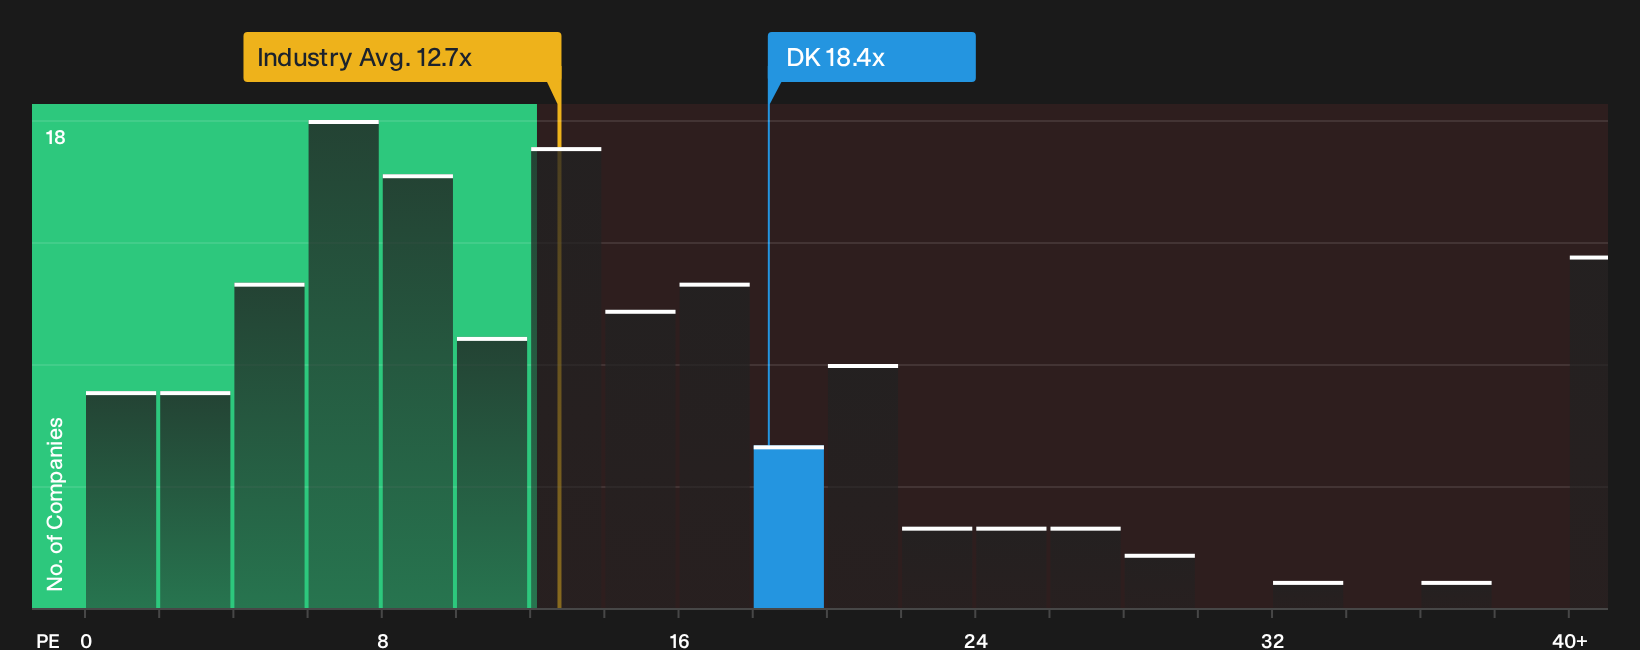
Analysts see Delek US Holdings as modestly undervalued at a fair value of $75, but the pricing on simple earnings multiples tells a different story. The current P/E of 18.4x is well above the US Oil and Gas sector on 12.7x, and it is also rich versus a fair ratio estimate of 7.9x. That gap points to meaningful valuation risk if expectations or sentiment fade.
This kind of disconnect matters for anyone weighing fresh capital. It raises a practical question: Does the analyst target still feel comfortable once you factor in a premium P/E against both peers and the fair ratio the market could move towards over time?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed sentiment is clear around Delek US Holdings, and the data is available for you to stress test both the bullish and the cautious views yourself. To see how that balance of optimism and concern compares, review the 1 key reward and 4 important warning signs
Looking For More Investment Ideas Beyond Delek US Holdings?
If you stop with Delek US Holdings, you only see one angle. Widen your watchlist with focused stock ideas shaped by clear fundamentals and risk filters.
- Target potential value opportunities by scanning companies that line up on strong quality and pricing signals using the 32 high quality undervalued stocks.
- Lock in ideas for income-focused investing by reviewing the 8 dividend fortresses that screen for higher yield opportunities with staying power.
- Protect your downside by concentrating on resilient balance sheets through the 30 resilient stocks with low risk scores that filter for sturdier financial profiles.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com