
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Micron Technology (MU) Could Be 46% Undervalued As AI Memory Bets Face Earnings Test
Micron Technology (MU) heads into its fiscal fourth quarter update with sentiment running high, as investors weigh record gross margin guidance, multi year fixed price contracts, and progress on new 512GB DDR5 server memory.
Micron Technology’s momentum has been powerful, with a 30 day share price return of 16.02% and a year to date gain of 243.12%. The 1 year total shareholder return is very large at roughly 6x, signalling strong enthusiasm around AI driven demand and the upcoming earnings update, despite a softer 90 day patch where the share price fell 5.50%.
Scan beyond Micron Technology and see how other AI infrastructure suppliers are setting up into earnings with the curated 85 AI infrastructure stocks.
Micron Technology now trades with a very large one year return and record margin guidance already on the table. Does that backdrop still leave enough upside in the risk reward, or is most of the good news priced in before the valuation work even starts?
Most Popular Narrative: 46% Undervalued
The most followed Micron Technology thesis pegs fair value at $2,018 per share, well above the last close at $1,082.28. That gap is driving a view that the market is still discounting how central high bandwidth memory could be to Micron’s cash generation.
The primary engine driving Micron's forward revenue growth is the industry-wide transition to vertically stacked HBM4 architectures. The high physical complexity of HBM manufacturing introduces a steep 3x physical wafer consumption penalty over standard planar DDR5. This wafer penalty reduces the global supply of standard commodity memory, creating a persistent supply deficit. This structural tightness allows memory manufacturers to transition away from annual fixed-price agreements toward compressed monthly contracts with retroactive, spot-linked post-settlement clauses that are designed to maximize capital returns.
See why 138 investors see Micron Technology as 46% undervalued.
Result: Fair Value of $2,018 (UNDERVALUED)
Still, Micron Technology’s AI memory story depends on smooth 1-gamma and HBM4 execution and disciplined global capacity; any stumble here could quickly puncture that 46% undervaluation pitch.
Find out about the key risks to this Micron Technology narrative.
Another View on Micron Technology’s Valuation
That 46% undervalued narrative leans on a rich fair value per share. The SWS DCF model presents a different perspective, with Micron Technology trading above an estimated future cash flow value of $578.24, which appears overvalued within that framework.
Investors using cash flow driven models may ask whether current enthusiasm already leans too heavily on optimistic margin and growth assumptions, or whether the market is simply discounting the cyclicality risk that the DCF is attempting to capture.
Look into how the SWS DCF model arrives at its fair value.
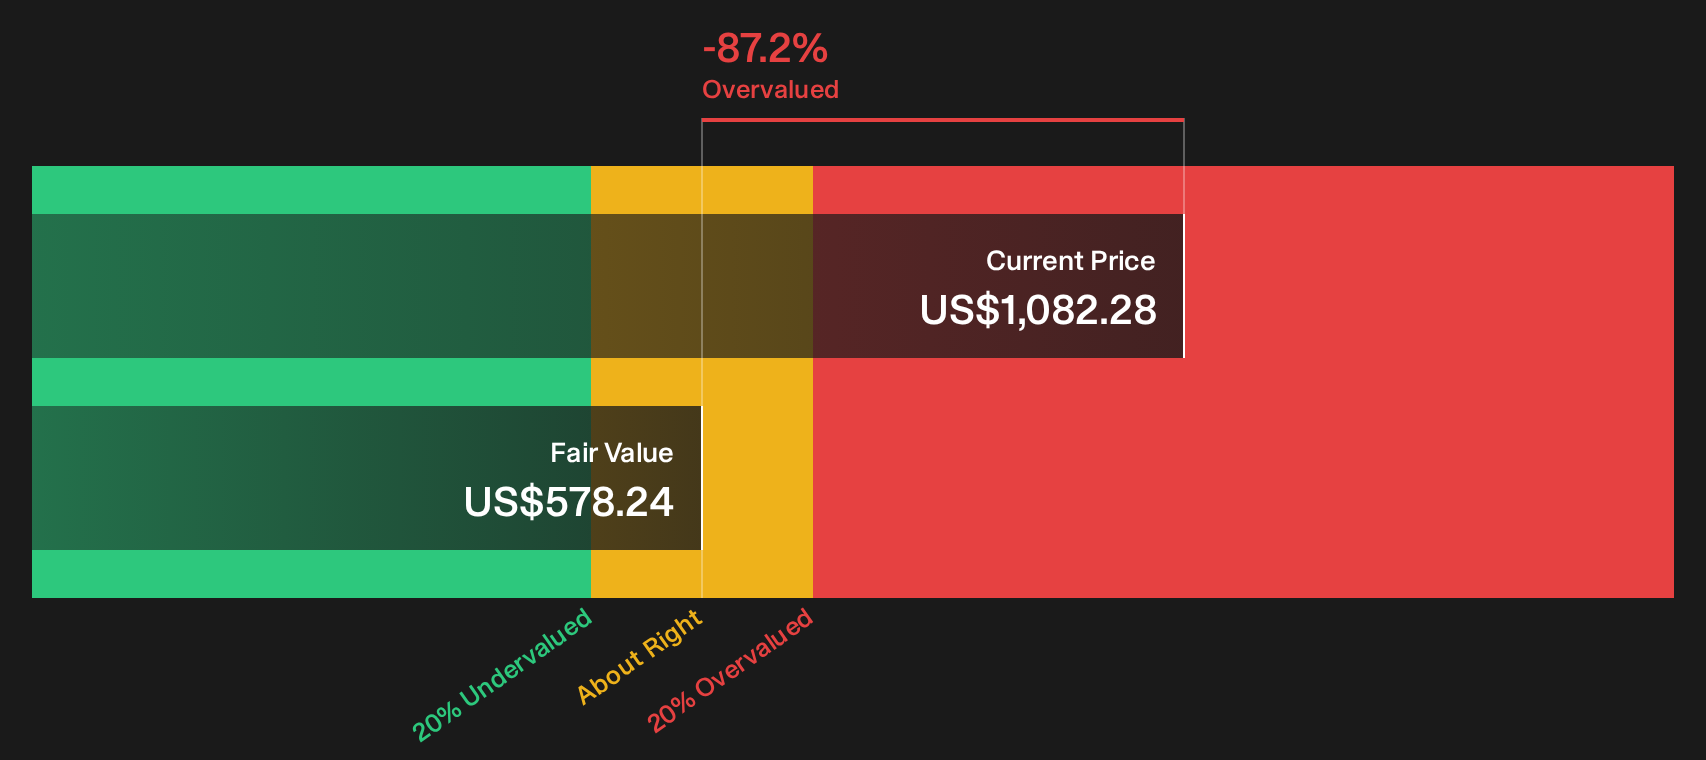
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Micron Technology for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 32 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Sentiment around Micron Technology is clearly split, with strong optimism and real concerns running side by side, so move quickly and examine the full picture yourself. To weigh both sides of the argument in one place, start with the 4 key rewards and 3 important warning signs.
Looking for more Micron Technology style ideas?
If you stop with Micron Technology, you risk missing other opportunities that fit your approach. Use the screener and keep your idea list working harder for you.
- Target resilience first by filtering for companies with strong finances and durable balance sheets through the list of solid balance sheet and fundamentals (24 results).
- Hunt for mispriced potential by scanning a curated pool of 32 high quality undervalued stocks that combine quality fundamentals with appealing valuations.
- Spot early stage potential by reviewing a focused set of 6 elite penny stocks with strong financials that already show stronger financial traits than typical micro caps.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com