
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
DHL (XTRA:DHL) Raises India Express Prices On A Valuation That Already Looks Full
DHL (XTRA:DHL) just told customers in India that Express shipment charges will rise 8.9% from 1 January 2027, reflecting higher inflation linked costs and a focus on service resilience.
DHL’s decision comes as investors have already seen a 9.7% 90 day share price return and a 21.9% share price gain year to date, while the 1 year total shareholder return of 56.6% and 3 year total shareholder return of 70.6% suggest momentum has been strong rather than fading.
Scan beyond DHL to see how other logistics and freight operators are pricing in similar cost pressures with our hand picked list of solid balance sheet and fundamentals (201 results).
For DHL, the pricing call in India and the strong recent share performance both point to a business that is flexing its pricing power, not just riding sentiment. How far does the current valuation already reflect that?
Most Popular Narrative: 4.5% Overvalued
The most followed valuation view now puts DHL’s fair value at €54.73, a touch below the €57.20 last close, which implies modest optimism already in the price.
Structural growth in e-commerce remains intact, with Deutsche Post maintaining targeted investments in its eCommerce division and logistics automation. This positions the company to benefit from the continued global shift to online retail, supporting long-term revenue growth.
Growing focus on sustainable logistics, evident in targeted organic and M&A investments, strengthens Deutsche Post's value proposition for customers seeking greener supply chains and enables premium pricing and potential market share gains. This positively impacts revenue and margin resilience.
See why 110 investors see DHL as 5% overvalued.
Result: Fair Value of €54.73 (OVERVALUED)
Still, DHL’s Express volumes face pressure from de minimis rule changes in the U.S., and ongoing trade volatility could challenge the earnings path that analysts are modeling.
Find out about the key risks to this DHL narrative.
Another View: DHL On Earnings Multiples
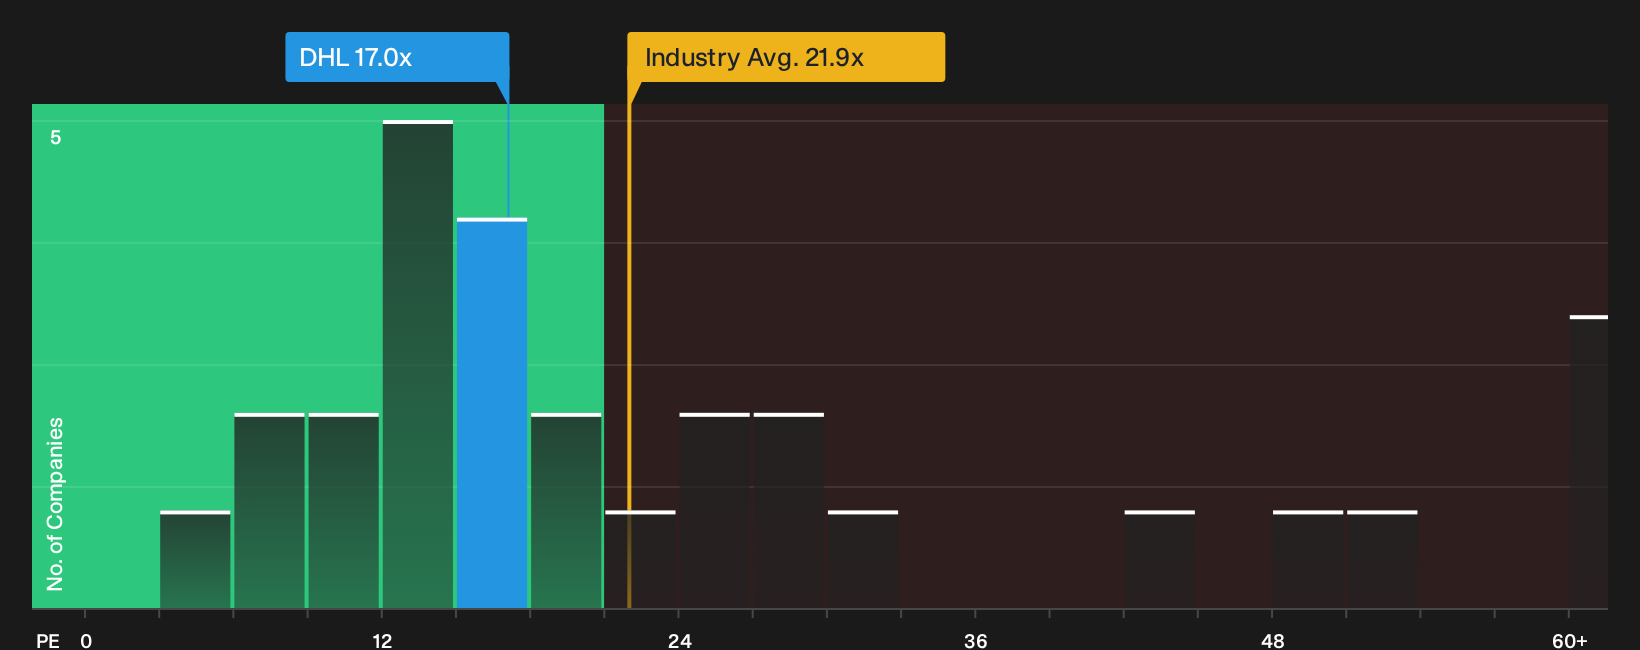
The crowd narrative has DHL as roughly 4.5% overvalued at €54.73, yet the current P/E of 17x tells a different story. That ratio sits below the European Logistics average of 21.9x and only just under a fair ratio of 17.7x. This points to limited excess optimism and some valuation cushion if sentiment cools.
For a closer look at how that P/E gap compares to peers in practice, and what it might mean for future re-rating risk or opportunity, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Sentiment around DHL is leaning confident, so consider moving quickly and weighing the data against your own expectations before that mood shifts. To see what investors are optimistic about in the current setup, review the 4 key rewards
Looking for more DHL-sized investment ideas?
If DHL has sharpened your focus on pricing power and resilience, do not stop here. Use the Simply Wall St Screener to uncover other opportunities before the crowd catches up.
- Target dependable cash generators by scanning for companies with robust balance sheets and clean fundamentals through the list of solid balance sheet and fundamentals (201 results).
- Hunt for potential value opportunities by running a screen that highlights 184 high quality undervalued stocks that combine quality metrics with compressed valuations.
- Prioritise durability by seeking 226 resilient stocks with low risk scores that score well on financial strength, earnings consistency, and measured volatility.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com