
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Did Renewable Insurance Launch Just Shift Aon (AON) Investment Narrative?
- Aon has launched a global insurance facility focused on onshore renewable energy projects, offering coverage across construction and operational phases to developers, owners and contractors.
- The new facility targets growing demand for risk transfer in renewable infrastructure, tying Aon’s reinsurance, advisory and analytics capabilities more tightly to energy transition spending.
- This development may shape how investors interpret Aon’s positioning in relation to the global onshore renewables insurance market.
Scan beyond Aon to identify other insurance and risk advisers that may be positioned for significant shifts in renewables and infrastructure by reviewing our curated 40 power grid technology and infrastructure stocks
Aon Investment Narrative Recap
Aon appeals to shareholders who believe its mix of risk, reinsurance and human capital services can keep generating solid cash flow even if insurance pricing softens or clients rein in spending. The biggest near term swing factor is execution on large integrations such as NFP and the renewables push, while keeping service quality high enough to protect retention.
The key risk right now is balance sheet stretch. Debt is elevated, new term loans and bonds add further leverage, and interest expense matters more if revenue momentum slows. The recent leadership moves in Germany and EMEA look more like continuity than a material change to short term catalysts or risk.
The most relevant recent development for these catalysts is the new US$4b delayed draw term loan and US$3b revolving credit facility that sit alongside almost US$5.5b of fresh long dated bonds. This is a funding stack that supports the USI Advantage acquisition and continued M&A, while locking in committed liquidity.
That funding comes with covenants around interest coverage and net leverage, which put execution in the spotlight. Management needs the combined operations of Aon, NFP, USI Advantage and the expanded reinsurance and Life Solutions franchises to deliver enough EBITDA to keep those ratios within agreed ranges as macro conditions, pricing and forex move around.
Aon's narrative projects US$23.0b in revenue and US$3.9b in earnings by 2029. This implies 9.4% yearly revenue growth, with earnings expected to stay at US$3.9b, in line with current earnings.
Uncover why Aon's fair value indicates a 37% potential upside to its current price that could narrow quickly.
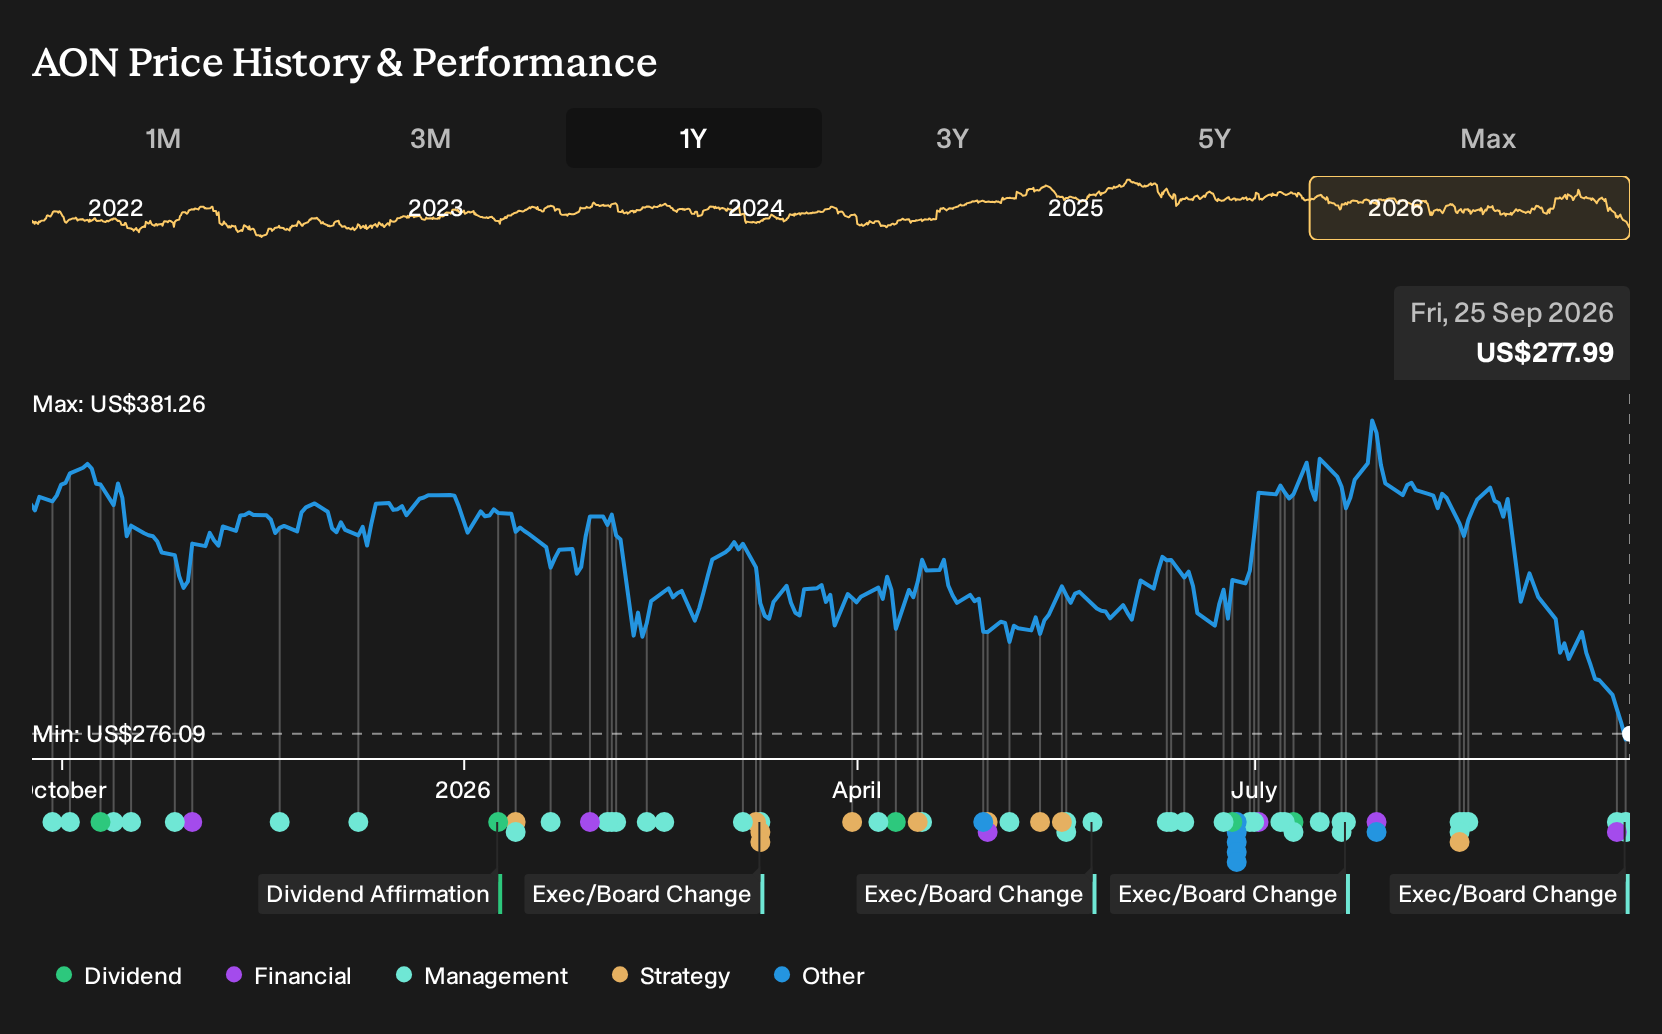
Exploring Other Perspectives
Two fair value estimates from the Simply Wall St Community cluster between US$381 and about US$393 per share, which already hints at differing expectations for Aon. Those retail perspectives do not yet factor in the fresh leverage stack or senior leadership changes across reinsurance and Life Solutions, so treat them as starting points and explore several contrasting views.
Explore another Aon fair value estimate, including one that suggests it could be worth just $381.00!
The Verdict Is Yours
Disagree with existing narratives? Extraordinary outcomes rarely come from following the herd, so go with your instincts.
- A great starting point for your Aon research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Aon. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Aon's overall financial health at a glance.
Looking For More Ideas Beyond Aon?
If Aon has sharpened your thinking about risk, capital and cash flow resilience, you can use that same lens across other opportunities with the Simply Wall St Screener. Start by focusing on the type of companies you want in your portfolio, then let the data narrow the field for you.
- For investors who care most about valuation support and quality fundamentals, start with companies flagged as 32 high quality undervalued stocks, which may offer a margin of safety backed by solid balance sheets and cash generation.
- If capital preservation and smoother returns matter more than excitement, look at businesses filtered as 30 resilient stocks with low risk scores that score well on financial strength and earnings stability.
- To uncover less crowded ideas with robust fundamentals, explore the 16 high quality undiscovered gems list that combines quality metrics with lower market attention.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com