
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Corning (GLW) After New AI Connectivity Deals Looks Undervalued But Is It Priced In
Corning (GLW) has entered the AI plumbing conversation through two new collaborations that focus on high-density optical links. Both projects target the wiring challenges inside modern data centers.
For context, Corning’s share price has climbed 72.9% year to date to US$156.74, helped by recent AI connectivity headlines, even though the 90 day share price return is down 38.7% and longer term total shareholder returns over 3 and 5 years remain very large by comparison to those shorter moves.
Scan beyond Corning’s AI wiring push and size up other potential beneficiaries of the same build out with our curated list of 85 AI infrastructure stocks.
Corning has already run hard on AI plumbing hopes, then pulled back sharply. Does that recent swing justify stepping in now, or does it argue for patience and a better entry before the numbers do more of the talking?
Most Popular Narrative: 18% Undervalued
On the current narrative, Corning is priced at $156.74 against an implied fair value of $191.40, so the gap between story and screen is already clear before digging into the drivers behind it.
Corning's Springboard plan aims to add more than $4 billion in annualized sales by 2026, driven by strong demand in Optical Communications and Solar sectors due to powerful secular trends, positively impacting revenue growth.
The company sees substantial growth in Optical Communications, particularly in innovations for Gen AI data centers, which are expected to drive incremental revenue and accelerate operating margin improvements toward 20% by the end of 2026.
See why 91 investors see Corning as 18% undervalued.
Result: Fair Value of $191.40 (UNDERVALUED)
Still, Corning’s reliance on non GAAP metrics and its exposure to tariff and trade shocks could quickly challenge today’s AI heavy narrative.
Find out about the key risks to this Corning narrative.
Another View on Corning’s Valuation
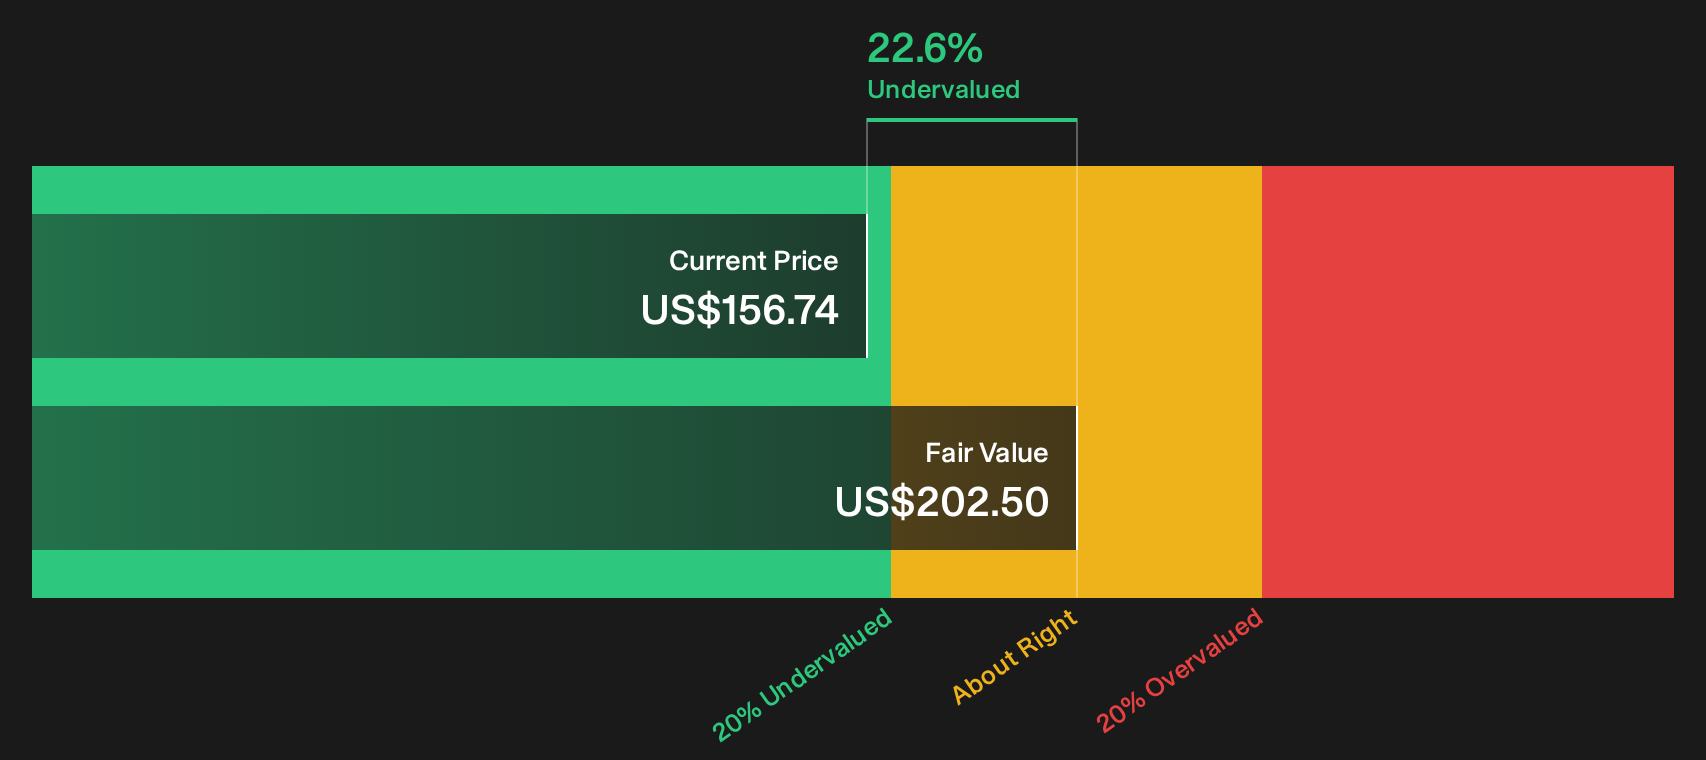
For Corning, the SWS DCF model points to a fair value of $202.50, which is higher than both the current $156.74 share price and the earlier $191.40 fair value narrative. This second lens still lands in the undervalued camp but raises the question of how much future cash flow optimism you are comfortable incorporating.
Look into how the SWS DCF model arrives at its fair value.
Next Steps
Mixed messages on Corning and AI wiring are one thing; your own conviction is another. Move quickly, stress test the upside and downside, then ground your decision in the 4 key rewards and 3 important warning signs.
Looking for more Corning style investment ideas?
If Corning has sharpened your focus on pricing power and balance sheet strength, do not stop here. Broaden your watchlist and give yourself better options.
- Hunt for quality at a discount by scanning our curated set of 32 high quality undervalued stocks.
- Stack your portfolio with potential income payers by reviewing a focused group of 8 dividend fortresses.
- Dial down portfolio stress by filtering for companies in our 30 resilient stocks with low risk scores.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com