
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
3 Dividend Stocks With Cash Flow Support As Treasury Yields Hit 5.23%
Surging U.S. Treasury yields and persistent inflation concerns are shaking the foundations of traditional equity pricing, and high-dividend, cash-rich stocks suddenly look very different when the 10-year pays 5.23%. Income investors now face a real choice between steady payouts and government paper. This article walks through three stocks our screener flags as potentially well positioned for this new rate reality and explains why their cash flows may be especially important in the current environment.
The stocks highlighted below are just a small sample. The full screen surfaced 34 more large, income-oriented companies in developed markets with equally compelling cash flow and dividend narratives that are not covered here. To identify and analyze the ideas that best fit your own risk and income goals, head straight to the High-Dividend, Cash-Generative Value Stocks in Developed Markets screener.
Verizon Communications (VZ)
Verizon Communications fits the screener brief as a large, dividend-focused telecom that leans on hefty U.S. cash flows rather than aggressive growth promises. Its current network buildout gives income investors something tangible to watch.
Verizon Communications generates about US$107.2b in Consumer revenue and US$29.4b from Business services, with the rest from corporate and eliminations, almost entirely in the United States, and the stock is valued at roughly US$195.6b in market cap.
"The rapid expansion of fixed wireless access and fiber broadband, now supported by Verizon Communications being on track for more than 32 million fiber passings by the end of 2026 and a medium term target of 40 million to 50 million passings, together with broadband net adds and the Frontier integration, supports further connectivity share gains that can lift service revenue and ARPU."
The real swing factor is how one pressure point shapes the balance between those cash-rich network assets and future margin potential.
That balance will decide how much of Verizon Communications' cash engine flows back to you versus into future buildout, and the full narrative for Verizon Communications shows how that trade-off could be accelerating.

American Water Works Company (AWK)
American Water Works Company brings a different kind of income story to this high-dividend, cash-generative screen. Its regulated water and wastewater assets aim to swap growth glamour for essential service reliability at a time when higher yields are challenging riskier parts of the market.
American Water Works Company runs regulated water and wastewater systems across 14 U.S. states, generating about US$4.9b from regulated businesses and US$409 million from other services, and the stock is valued at roughly US$26.0b.
"Heightened regulatory and societal focus on water quality and infrastructure modernization now aligns with a roughly US$48b capital plan over 10 years and US$1.8b already deployed in the first half of 2026."
The key question is what happens to earnings and dividend headroom if a single unseen pressure on that spending and recovery cycle shifts even slightly off script.
If that risk is front of mind, the full narrative for American Water Works Company sets out how American Water Works Company’s capital plan, regulation and inflation pressures could be quietly decoupling.

TransAlta (TSX:TA)
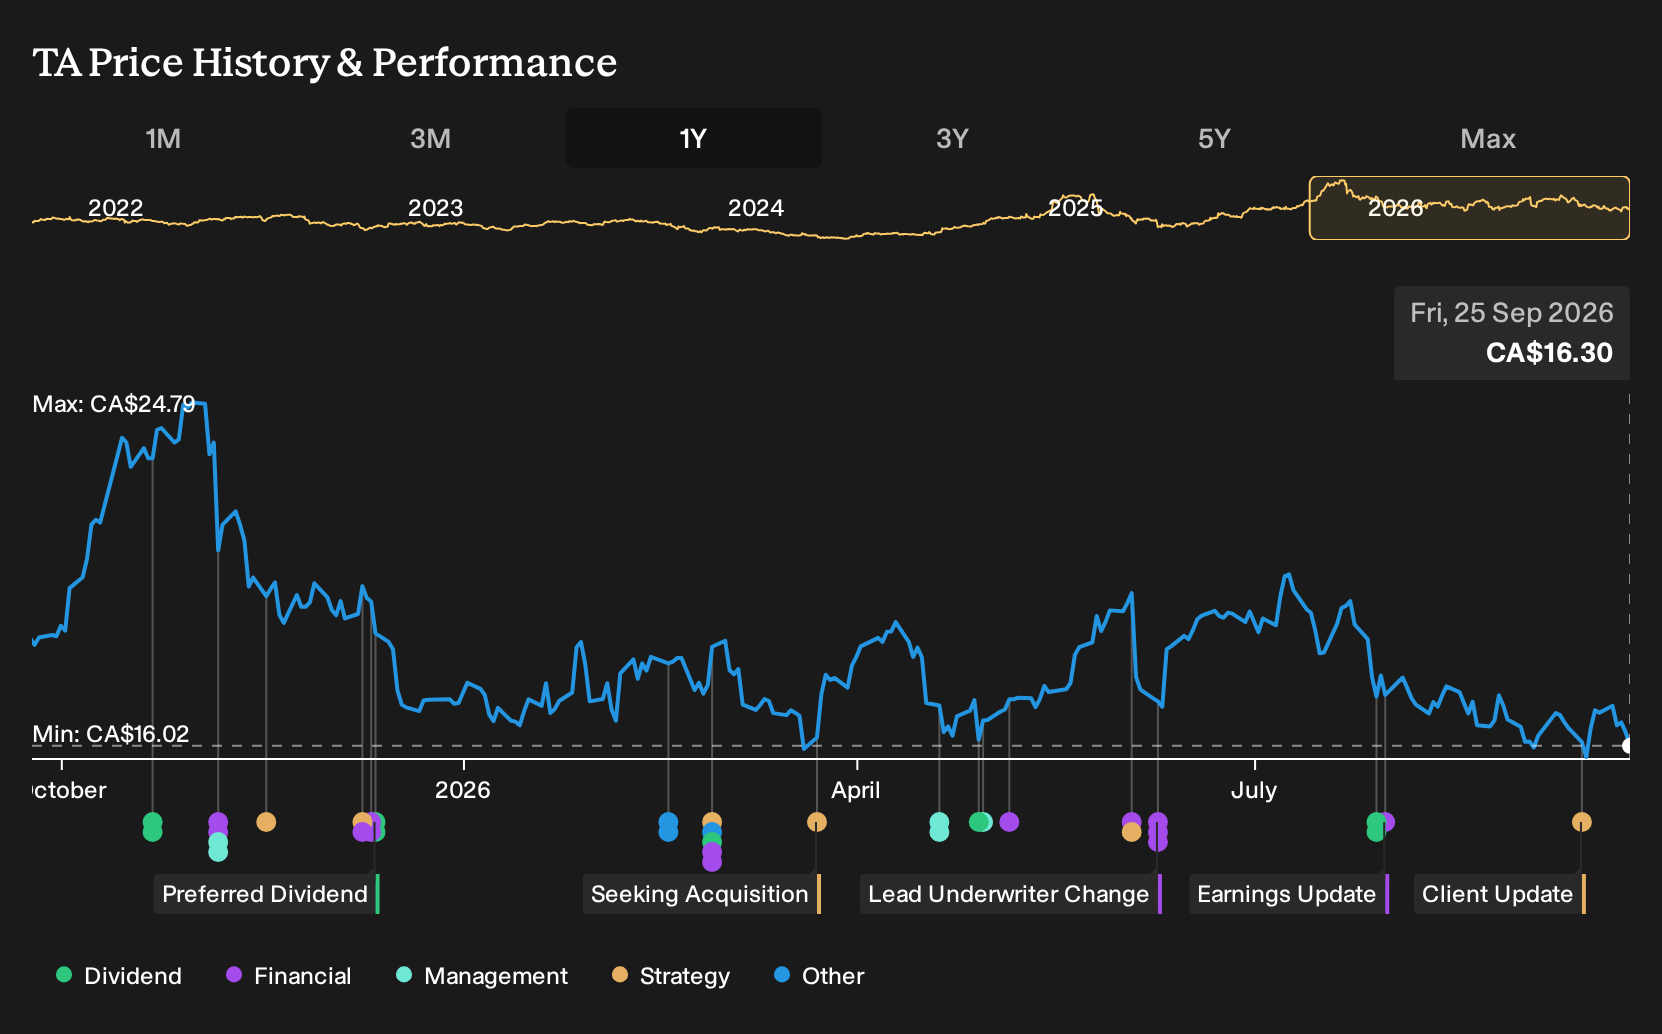
TransAlta is a long-running Canadian power producer that fits this high-dividend, cash-generative screen through its utility-like contracted assets and exposure to a developed-market customer base. The group earns CA$1.3b from Gas, CA$310 million from Hydro, CA$301 million from Wind & Solar, CA$273 million from Energy Transition, and CA$131 million from Energy Marketing, and the stock carries a market value of about CA$5.2b.
For income-focused investors searching for durable cash flows as rates stay higher, TransAlta offers a mix of contracted power, renewables and transition assets that links directly to long-term electricity demand rather than market mood. This sets up the Keephills data centre opportunity as a potentially important swing factor.
"Data center load growth in Alberta is expected to materially increase electricity demand over the next decade, with TransAlta well positioned to benefit thanks to capacity allocations, fleet optionality, and ongoing negotiations for long-term contracts, which will support sustained revenue growth and improved earnings visibility."
What really moves the needle is how one unresolved piece of that growth story ultimately flows through to pricing power and margin resilience.
That missing piece of the puzzle is where the full narrative for TransAlta pulls everything together and shows whether TransAlta’s Keephills opportunity is quietly accelerating or masking risk.
Seeking Fresh Alternatives Before They Fly?
Some of the best breakout stories start quiet, then move fast as momentum builds and prices run. Scan these fresh ideas before the crowd reacts, then consider your options promptly.
- Spot resilient cash generators while they are still under the radar for now by running the 32 high quality undervalued stocks and see which balance sheets look built to last.
- Track where AI momentum meets actual profits, not hype, by reviewing the curated list inside the 37 profitable AI stocks that aren't just burning cash and see which tickers are already turning code into cash.
- Position ahead of potential metals supply tightness by scanning the 36 best rare earth metal stocks and find producers tied to EVs, chips, and high tech manufacturing before pricing pressure emerges.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com