
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Is Debt Buyback Altering The Investment Case For ONEOK (OKE)?
- ONEOK reported that its operating subsidiary reached the full US$2b cap in a cash tender offer for multiple series of senior notes, following strong early participation before the September 14, 2026 early tender deadline.
- The move concentrates on long dated bonds; this can reshape ONEOK's interest cost profile and maturity schedule, affecting future financial flexibility and capital allocation choices.
- We will examine how ONEOK's investment narrative is affected by this US$2b debt tender that fully met early participation.
Scan how ONEOK’s US$2b bond tender compares with other balance sheet moves by large issuers and see which companies made our list of solid balance sheet and fundamentals (24 results) for potential resilience under pressure.
ONEOK Investment Narrative Recap
To own ONEOK, you need to believe in steady demand for U.S. natural gas and NGL infrastructure, plus continued utilization of its pipes, plants and export links. The US$2b tender for mostly long dated notes looks more like balance sheet housekeeping than a change to the operating story, so the core midstream thesis is largely intact.
The near term swing factor remains how volumes and commodity spreads feed into earnings after management trimmed the 2026 EBITDA outlook by about 2%. The biggest risk is still leverage and interest coverage. If volatility in spreads persists while debt stays high, that can pressure cash generation and limit room for new projects.
The tender announcement sits alongside earlier commentary that debt is not well covered by operating cash flow and that the dividend is not fully backed by free cash. Those flags put extra focus on how ONEOK handles maturities, coupon costs and refinancing terms over the next few years.
Analysts describe ONEOK as trading well below their DCF estimate, so execution on debt management becomes a practical catalyst. Cleaner maturities and clearer interest expense can support that trajectory, while any setback in integration of past acquisitions or weaker spreads would keep leverage risk in the foreground.
ONEOK's current earnings are about US$3.7b, with analysts expecting earnings of US$4.4b and revenue of US$40.4b by 2029. This implies earnings growth of roughly US$0.7b from today and a flat top-line profile over the forecast period.
Uncover why ONEOK's fair value indicates a 14% potential upside to its current price, which could occur faster than the balance sheet can adjust.
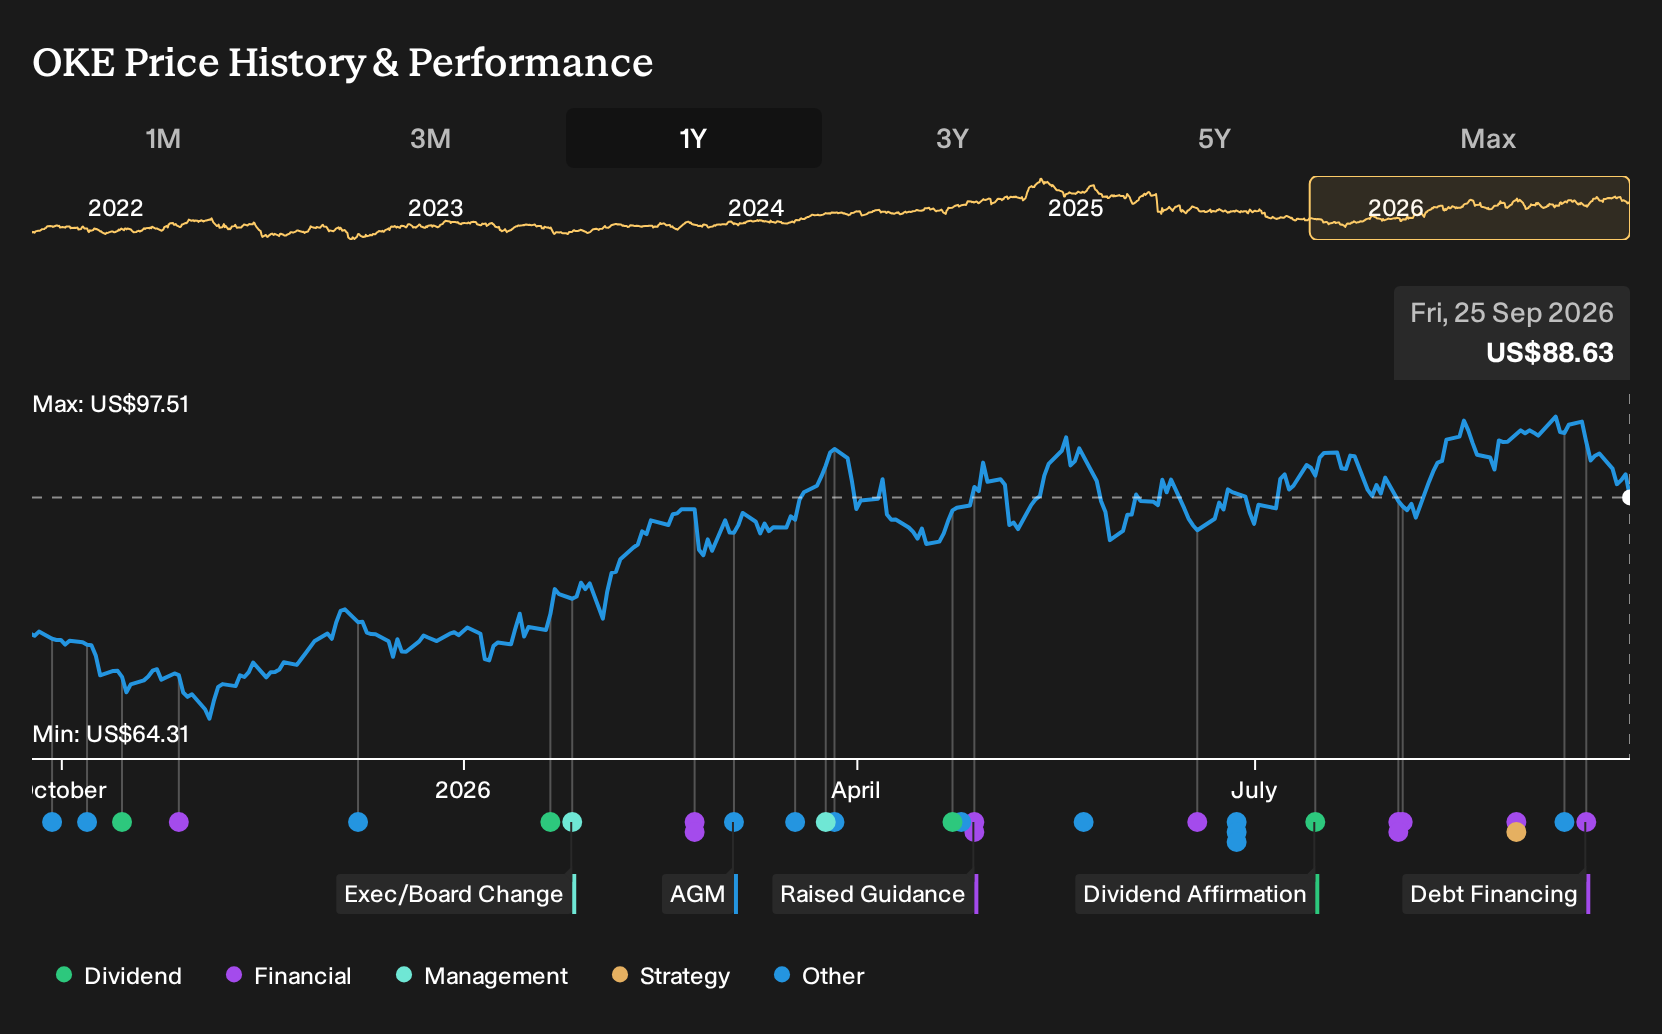
Exploring Other Perspectives
Not every analyst sees the ONEOK story through the same lens. The most pessimistic group focuses on long term energy transition risk, and before this tender they were modelling revenue falling toward about US$27.2b by 2029 with earnings near US$3.8b. That is a much tougher script. Treat this debt move as a fresh prompt to compare those assumptions with your own and to explore several competing views.
Explore 4 other ONEOK fair value estimates, including one that suggests it could be worth just $88.00.
Decide For Yourself
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your ONEOK research is our analysis highlighting 3 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for ONEOK. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate ONEOK's overall financial health at a glance.
Looking For More Ideas Beyond ONEOK?
If the ONEOK story has you thinking about portfolio balance and future cash generation, it can help to line it up against other businesses with clear financial profiles and different risk and income angles.
- For investors who want quality plus a valuation that still looks reasonable, scan a curated set of companies through 32 high quality undervalued stocks that combine stronger fundamentals with pricing that some might see as appealing.
- If resilience matters more to you than excitement, filter for balance sheets that look sturdier by running a screen on the 30 resilient stocks with low risk scores and see which businesses have lower overall risk scores.
- For those who care most about reliable income, review a focused pool of high-yield payers using the 8 dividend fortresses and compare their payouts and coverage metrics before committing capital.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com